

You've been renting in Fresno, watching monthly costs rise, and wondering whether the money leaving your account could help you become a homeowner instead. Buying may feel out of reach today, but you may also worry that a rent-to-own agreement could lock you into unclear terms, expensive repairs, or money you can't recover.
That tension explains why rent to own homes in Fresno attract attention. Fresno has a large renter population, a meaningful gap between renting and buying, and households looking for time to improve credit, save, or qualify for a mortgage. But rent-to-own isn't “rent now, own later.” The contract determines whether you receive a useful bridge to ownership or take on obligations without a realistic path to closing.
Introduction to Rent to Own Homes in Fresno
A Fresno renter may manage a monthly housing payment yet still fall short of mortgage approval. Credit repair, savings, income records, or uncertainty about a neighborhood can delay buying. A rent-to-own agreement may create time to address one of those obstacles while preserving a possible path to the home.
The arrangement is a contract, not a promise that renting automatically becomes ownership. You may owe an upfront option fee, a monthly payment above ordinary rent, or both. The agreement might credit part of those payments toward the purchase, but the written terms must state how credits are calculated, when they apply, and whether you lose them if you do not buy.
Fresno's renter-heavy housing situation helps explain the interest in this model. 53.2% of Fresno households are renter-occupied, compared with 45.9% statewide and 36.4% nationally, according to Fresno housing data from AreaVibes. Those figures describe demand for rental housing, not proof that a rent-to-own contract will be affordable or fair.
A renter needs a specific plan before signing. Identify the barrier to buying, estimate how long it will take to address, and check whether the option period gives enough time. California rules can also affect the practical cost of the arrangement, including rent-cap limits where applicable, inspection responsibilities, and the timing of the purchase option. Those details belong in the contract rather than in a verbal promise.
A conventional lease may be safer if income is uncertain, savings are limited, or there is no workable plan for improving credit. For a practical look at renting a property that may later be sold, review this rental strategy from Cyber Homes. The guiding question is simple: Can you remove the obstacle to buying before the option expires?
How Rent to Own Actually Works
Think of rent-to-own as a rental agreement with a reserved lane toward purchase. You live in the home as a tenant, pay according to the lease, and receive either a right or an obligation to buy later. The contract should identify the home, the rental term, the purchase price or pricing formula, the option period, payment credits, and default rules.
California arrangements generally use two legally distinct paths. Under one structure, the renter completes the scheduled periodic payments and ownership transfers according to the agreement. Under another, the renter can exercise a purchase option after the first payment. The California Department of Consumer Affairs guide to installment land contracts explains why the payment schedule and option period matter so much.
The two contract formats
A lease-option gives you the choice to buy. You can exercise the option if your finances and property evaluation support closing, but you may lose specified fees or credits if you walk away. This flexibility has value, though it isn't free.
A lease-purchase creates a stronger commitment to buy. The seller generally agrees to sell, while you agree to complete the purchase under the stated terms. Missing the financing goal at the end can create a serious default problem, so don't treat a lease-purchase as a casual trial rental. A plain-language explanation of this distinction is available in this guide to lease options.
The money behind the promise
Most agreements separate the monthly payment into ordinary rent and a possible rent premium or credit. For example, a contract might state that the standard rental charge is one amount and that an additional amount is credited toward the purchase price. The example only matters if the agreement specifies whether the credit applies automatically, requires on-time payment, sits in escrow, or disappears after a default.
The purchase price can be fixed at signing or calculated using a stated formula. A fixed price offers certainty, but it can become unfavorable if the home's value changes downward. A formula can track a later valuation, but it creates a different kind of uncertainty.
Before signing, compare the proposed arrangement with a broader creative real estate financing guide and ask a California real estate attorney to review the actual documents. Marketing language can't replace a contract that clearly answers when you may buy, what you must pay, and what you lose if the transaction fails.
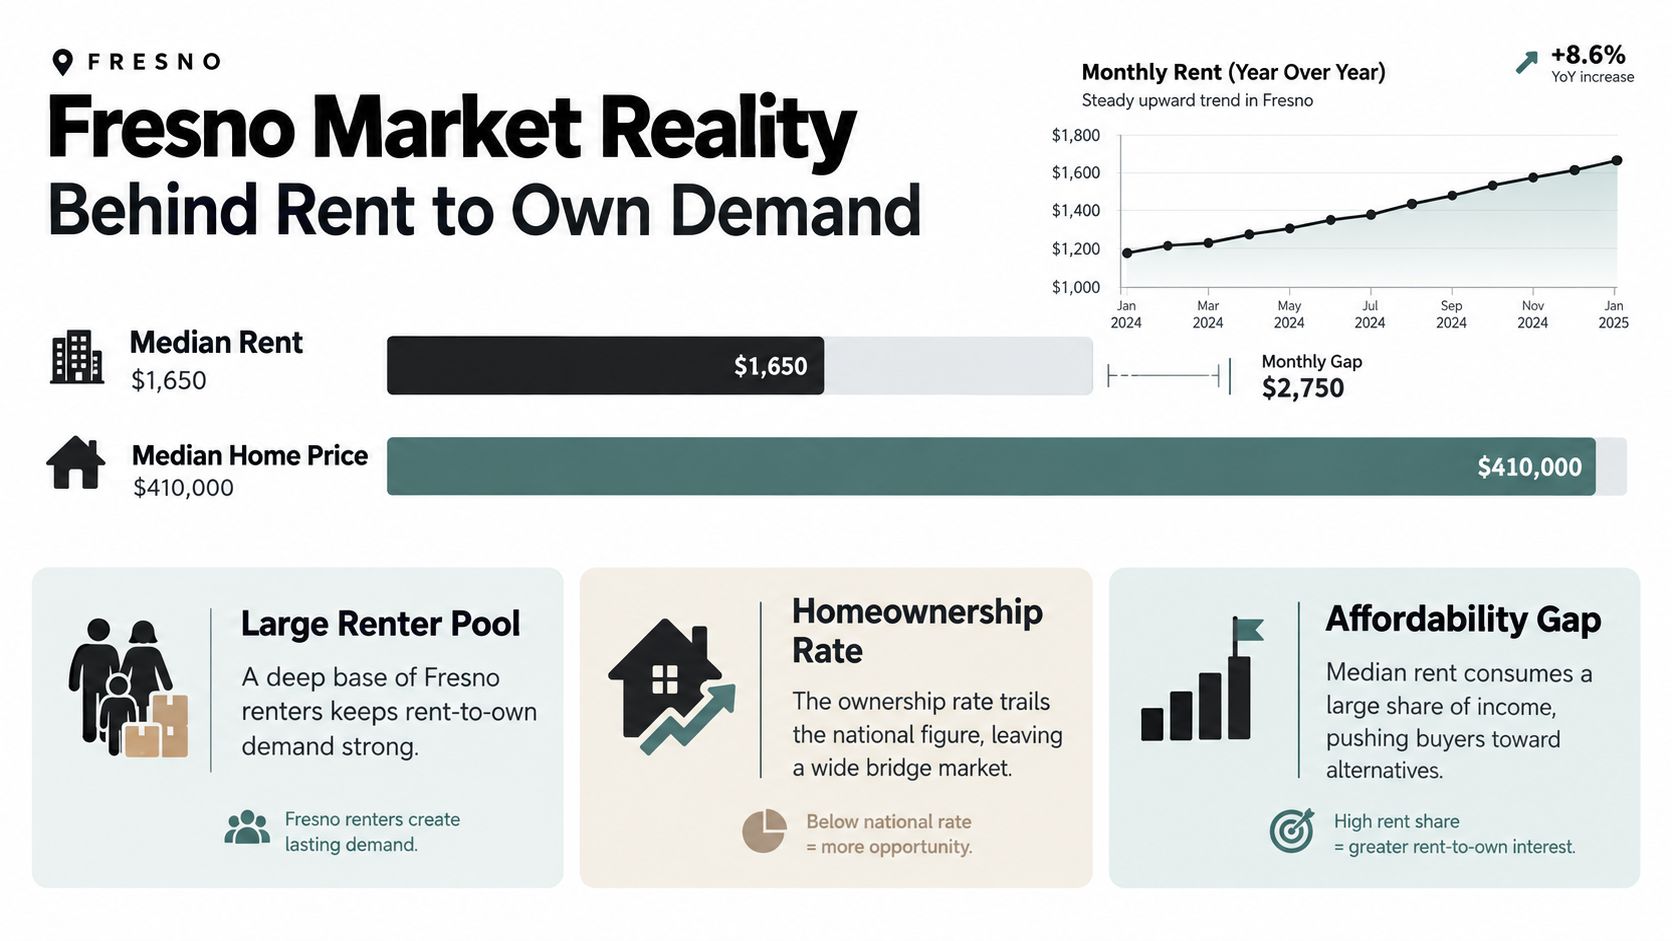
Fresno Market Reality Behind Rent to Own Demand
A Fresno renter can handle a monthly housing payment and still fall short of mortgage approval. The gap usually comes from credit history, available cash, or lender requirements. That mismatch helps explain interest in rent-to-own arrangements, especially in a city where renters make up a large share of households.
One local housing snapshot lists a median rent asked of $1,576, a median home price of $454,265, and renters occupying 53.2% of households. These figures do not promise a rent-to-own opportunity. They show why some households may seek a bridge between a standard lease and an immediate purchase. The underlying comparison appears in the Fresno market figures from AreaVibes.
More recent local reporting described a 71% homeownership premium, approximately $1,275 per month. Homeowners averaged $3,071 in monthly housing costs, compared with $1,796 for renters. The report also cited Fresno median rent at $1.8K, up 13.27% year over year, alongside 431 rental listings. These figures come from ABC30's Fresno housing coverage.
Why the gap matters
Rent-to-own works like a bridge, but a bridge only helps if it reaches the other side. The waiting period should give the buyer a measurable path toward mortgage approval, such as improving credit, saving funds, or resolving documentation issues. An extra monthly payment without that progress can leave the renter paying more while remaining unable to buy.
A fixed purchase price may provide planning value if rents and housing costs rise. It can also create risk. If the home's later market value falls below the agreed price, the buyer may need additional funds, seek a renegotiation, or leave the deal under its contract terms.
Fresno County reporting has listed median rent at about $2.0K with 586 rentals available, reinforcing that rentals serve a central role in the broader local housing market. County figures should be compared carefully with city-level numbers because they measure a wider area.
What renters should take from the data
The market may support demand for rent-to-own, but the numbers do not decide whether a particular contract works. A renter should ask whether the arrangement shortens the path to lender approval or merely adds a rent premium, option cost, and maintenance responsibility.
Sellers face a related question: does delaying the sale provide enough value to justify waiting for the buyer's financing? California rules and the written agreement can affect rent increases, option timing, inspections, and responsibility for repairs, so the local market figures are only the starting point.
The useful comparison is ordinary rent plus savings and credit repair versus rent-to-own payments, option costs, maintenance obligations, and the likelihood of closing.
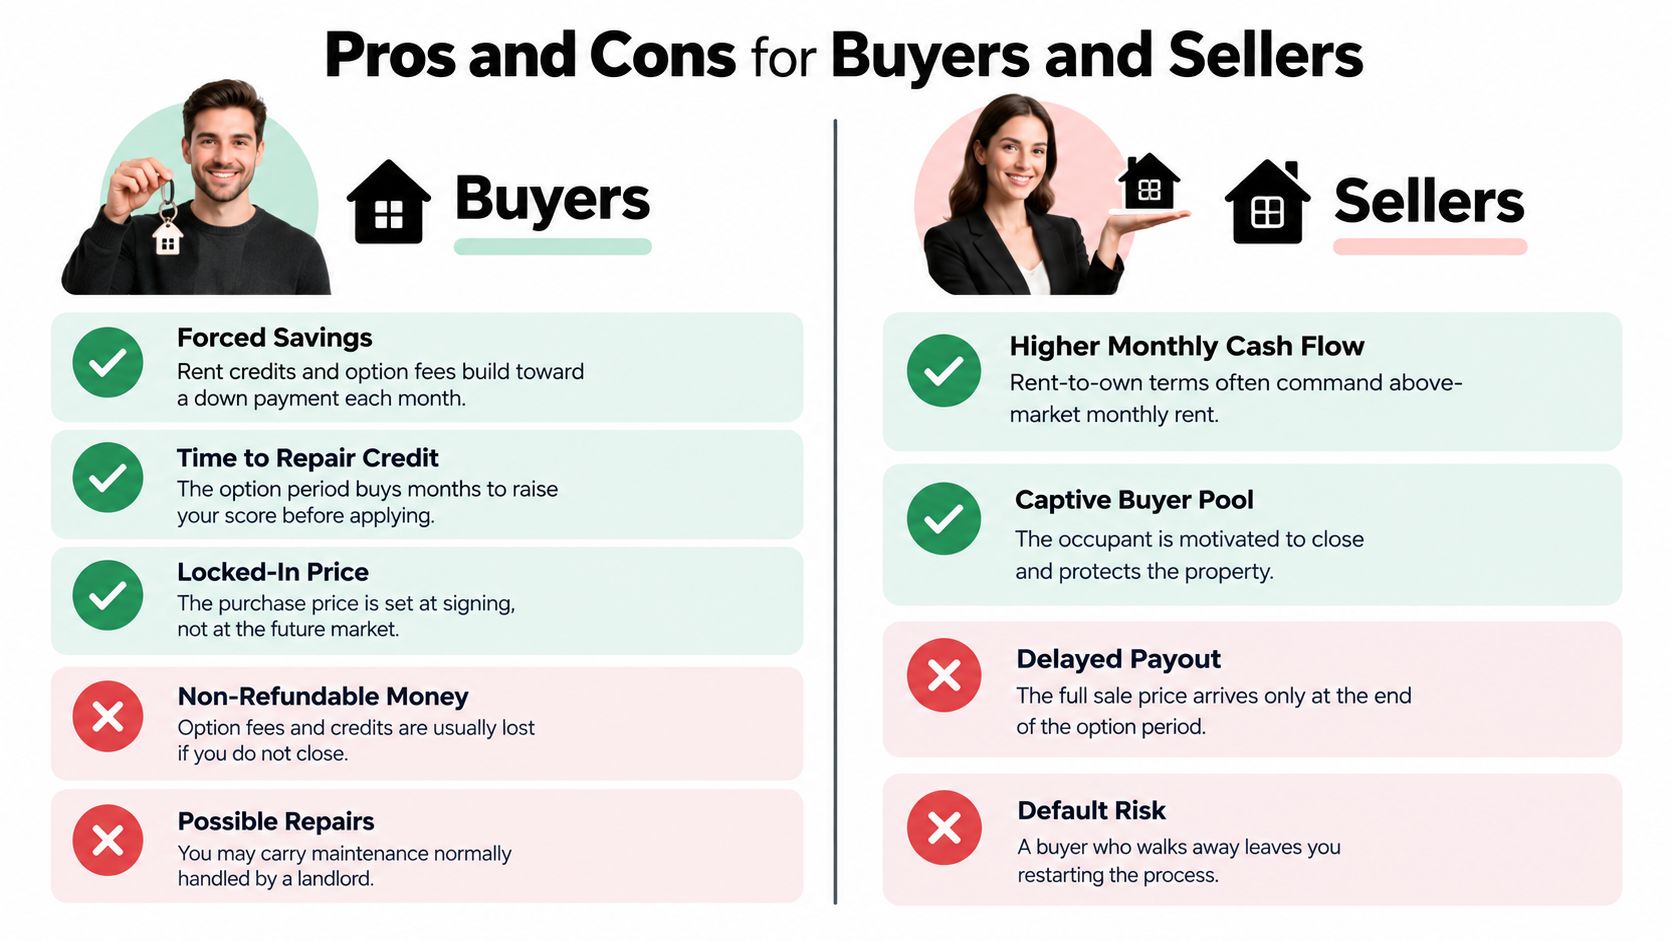
Pros and Cons for Buyers and Sellers
Rent-to-own can solve a timing problem, but it can also transfer risk from one party to the other. Buyers receive time and a possible purchase path. Sellers receive an occupant with a stated interest in buying, but they delay the full sale and still face default risk.
Buyer perspective
The strongest buyer benefit is time with a purpose. A lease-option may give you time to address credit issues, save cash, inspect the property through actual occupancy, and prepare for lender review. The arrangement can also make the future price easier to plan when the price is fixed clearly at signing.
The risks are just as concrete. Option fees may be nonrefundable. Rent credits may depend on perfect payment performance. A buyer may also become responsible for repairs that a normal landlord would handle, particularly if the agreement contains an “as-is” clause.
Seller perspective
A seller may receive higher monthly cash flow because the contract includes a rent premium. The occupant may also take greater care of the property because that person hopes to buy it. Those benefits come with delayed liquidity, ongoing ownership expenses, and the possibility that the buyer can't obtain financing.
| Perspective | Key Advantage | Key Risk to Manage |
|---|---|---|
| Buyer | Time to improve finances and prepare for a mortgage | Losing fees or credits if the purchase doesn't close |
| Buyer | A clearly stated purchase price can improve planning | The price may later exceed the property's market value |
| Seller | A motivated resident may reduce turnover concerns | The seller waits for the final sale and carries default risk |
| Seller | A rent premium may increase monthly cash flow | The seller remains responsible for ownership obligations assigned by law or contract |
When the structure may fit
Rent-to-own may be reasonable when the buyer has a written financing plan, stable income, a realistic repair budget, and enough time to meet the option deadline. It may also suit a seller who doesn't need immediate sale proceeds and is prepared to manage the property during the term.
Traditional renting may be safer when the buyer's timeline is unknown or the contract demands money that would otherwise fund savings. For a seller who wants a clean, immediate transaction, an ordinary sale may be more suitable than waiting for a future closing.
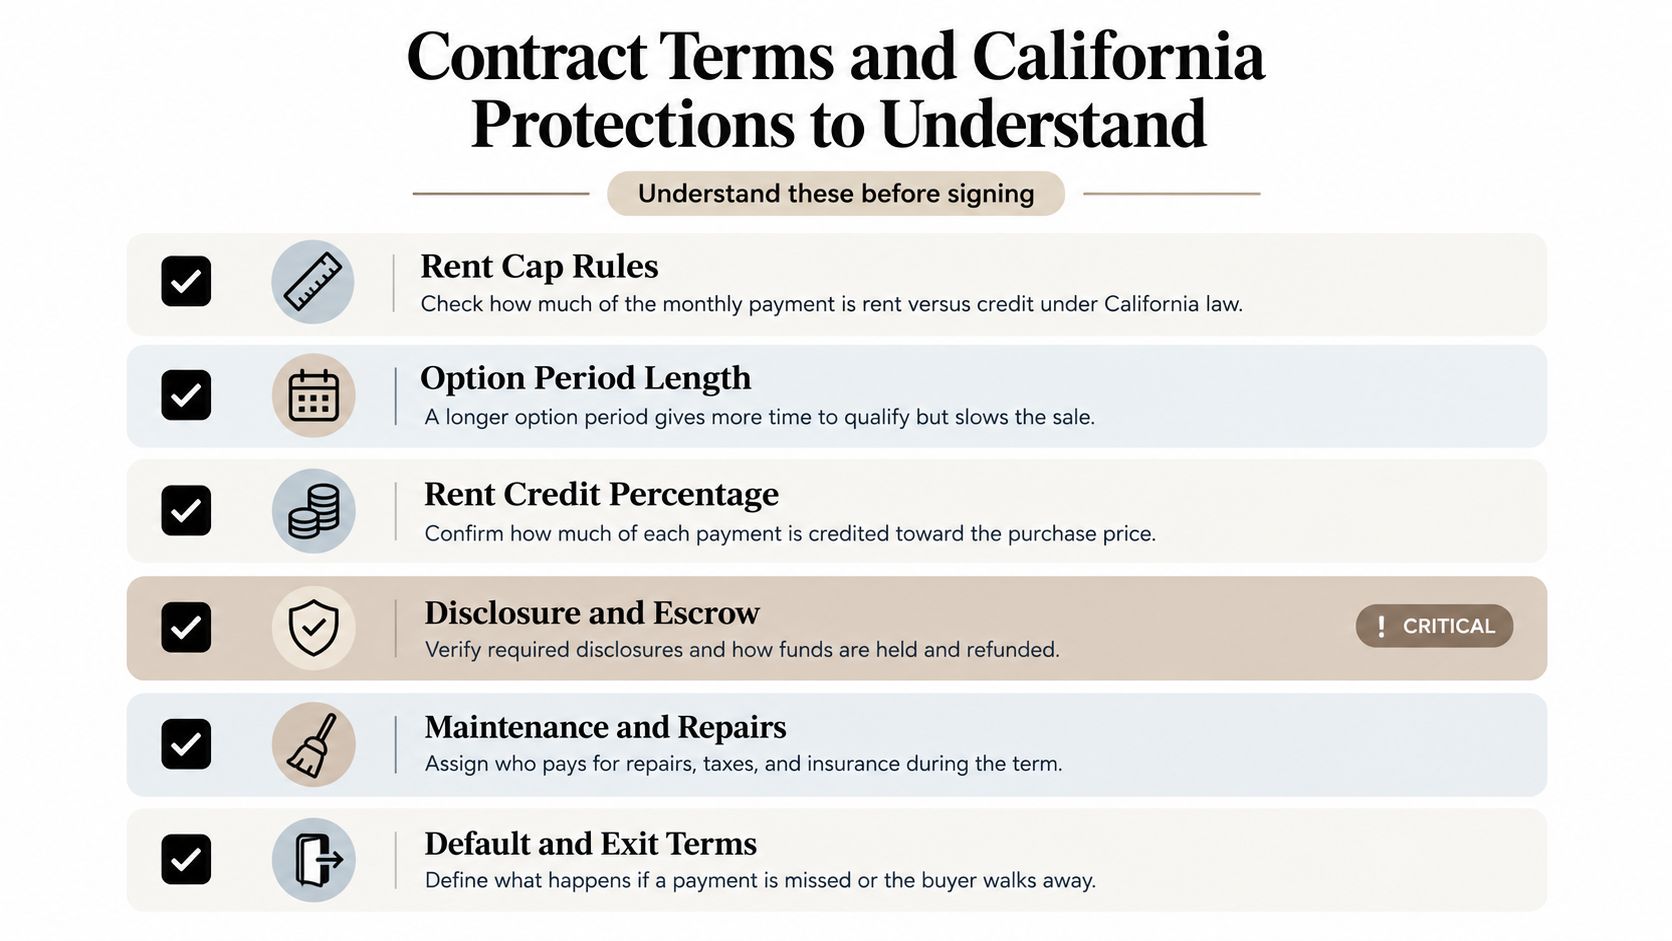
Contract Terms and California Protections to Understand
The contract is the product. The house is only one part of the decision. Before you pay an option fee or move in, read every clause that controls payment credits, repairs, deadlines, and exit rights.
Start with the payment structure
California tenant rules limit annual rent increases to 5% plus inflation, capped at 10%, with state guidance published through July 31, 2026, as described in the California tenant rights guidance from the Attorney General. A rent-to-own agreement still needs careful review because the monthly total may combine rent, a premium, and other charges. Ask the seller or manager to show each component separately.
Confirm these points in writing:
- Option fee: Is it refundable, credited to the purchase, or forfeited if you don't close?
- Rent credit: What exact portion of each payment applies to the future purchase?
- Payment condition: Does one late payment erase accumulated credits?
- Purchase price: Is the price fixed, appraised later, or calculated by a formula?
- Option deadline: How and when must you exercise the purchase right?
Assign responsibility before a problem occurs
Repair language often causes the greatest surprise. An “as-is” provision may require the tenant-buyer to pay for conditions that consume money intended for a down payment. The contract should distinguish routine upkeep from major systems, habitability issues, taxes, insurance, and structural work.
The California landlord-tenant law resource can help you identify questions, but it isn't a substitute for legal advice about your specific agreement. Have counsel review the documents before signing, especially if the arrangement combines a lease, option, installment payments, or seller financing.
Apply a due-diligence filter
Fresno Housing's homeownership pathway shows how strict eligibility and property review can be. Eligible homes may include single-family homes, condos, or mobile homes only when the land is owned or subject to at least a 40-year lease. The buyer must use a fixed-rate mortgage from a licensed lender, without a balloon or seller-financed loan, and must pass both an HQS inspection and an independent professional inspection. The program also gives a 120-day search window after prescreening, according to Fresno Housing's HCV homeownership information.
A private deal may not follow that program, but the due-diligence logic remains useful. Verify title, liens, land tenure, property condition, insurance, lender eligibility, and the consequences of missed payments before treating the property as a path to ownership.
How to Find and Structure a Rent to Own Deal in Fresno
Start with the buyer, not the listing. Write down the obstacle preventing a mortgage today, the action required to address it, and the evidence you'll use to measure progress. A vague goal such as “fix my credit” isn't enough. You need a practical plan for income documentation, debt management, savings, and lender conversations.
Then screen the property as if you were buying it immediately. Check ownership, title, taxes, insurance, liens, physical condition, neighborhood suitability, and comparable pricing. Don't assume a rent-to-own listing is fairly priced because it includes a future purchase right.
A workable search sequence
Find a legitimate owner or representative. Confirm who owns the property and who has authority to negotiate. Never send an option payment to an unknown party without verifying the property and documents.
Ask for the complete proposed agreement. Review the lease, option, disclosures, payment schedule, repair provisions, and default language together. A verbal promise about credits has little value if it isn't written.
Pre-screen financing. Speak with a licensed lender before choosing the option period. The lender can identify the work needed to qualify and help determine whether the future purchase price is plausible.
Inspect before committing. Use both a professional inspection and any applicable program standards. A home that looks comfortable as a rental may still require ownership costs you can't carry.
Negotiate the formula, not only the headline price. Clarify the option fee, monthly rent, credit amount, exercise procedure, appraisal treatment, repair allocation, and exit terms.
Use local support carefully
A Fresno brokerage or property manager can help locate rental inventory, coordinate showings, screen applicants, and prepare compliant lease documents. Edinhart's real estate attorney services in Fresno may be relevant when a transaction requires legal review, but every buyer should understand who is representing which party and who is responsible for legal advice.
For owners, Edinhart Realty and Property Management offers full-service management and placement-only services, including marketing, applicant screening, lease drafting, repair coordination, and property reporting. For buyers, the important point is independent review. The person helping market a property may not be the person advising you about whether the contract is financially sound.
Making the Right Choice With Edinhart Guidance
A rent-to-own home deserves the same seriousness as a purchase because the contract can affect your housing, savings, and future borrowing ability. Before agreeing, answer five questions clearly:
- What prevents me from qualifying today?
- What specific action will address that obstacle?
- How much money could I lose if I don't close?
- Who pays for repairs and other ownership costs during the term?
- What happens if the property value, my income, or my financing options change?
If the answers are documented and your timeline is realistic, rent-to-own may serve as a bridge. If the answers rely on promises, uncertain credits, or a purchase price you may not be able to finance, continuing to rent while saving and preparing may be the safer choice. Sellers should make the same assessment from the other side, weighing delayed proceeds against a committed occupant and the risk of restarting the sale process.
Local guidance can help with property screening, pricing, marketing, tenant placement, and California-compliant documentation. The decision should still be based on the actual property, actual contract, and actual financing plan, not on the label “rent-to-own.”
Edinhart Realty and Property Management can help Fresno-area owners market and place residents, manage rental operations, and evaluate buying or selling options connected to a rent-to-own strategy. Visit Edinhart Realty and Property Management to discuss the property, review your goals, and take the next step with a clear plan.


