

Let’s cut right to the chase: single-family homes are a uniquely powerful investment. They offer a fantastic mix of asset growth, steady income, tangible control, and some serious tax advantages.
I like to think of it like planting a tree. It grows in value year after year (that's your appreciation), but it also gives you consistent fruit along the way (that's your rental income). This blend of stability and return is a well-trodden path to building real, sustainable wealth.
The Enduring Appeal of Single Family Home Investing
Unlike stocks or other paper assets that can feel abstract, a single-family home is a real, tangible thing you can see, touch, and improve. A huge part of why buying single family homes can be a good investment is the direct control you have. You're in the driver's seat—you pick the tenants, you decide on the renovations, and you choose when to sell. That level of command just isn't possible with most other investments.
This image really breaks down the core pillars of what makes single-family home investing work so well.
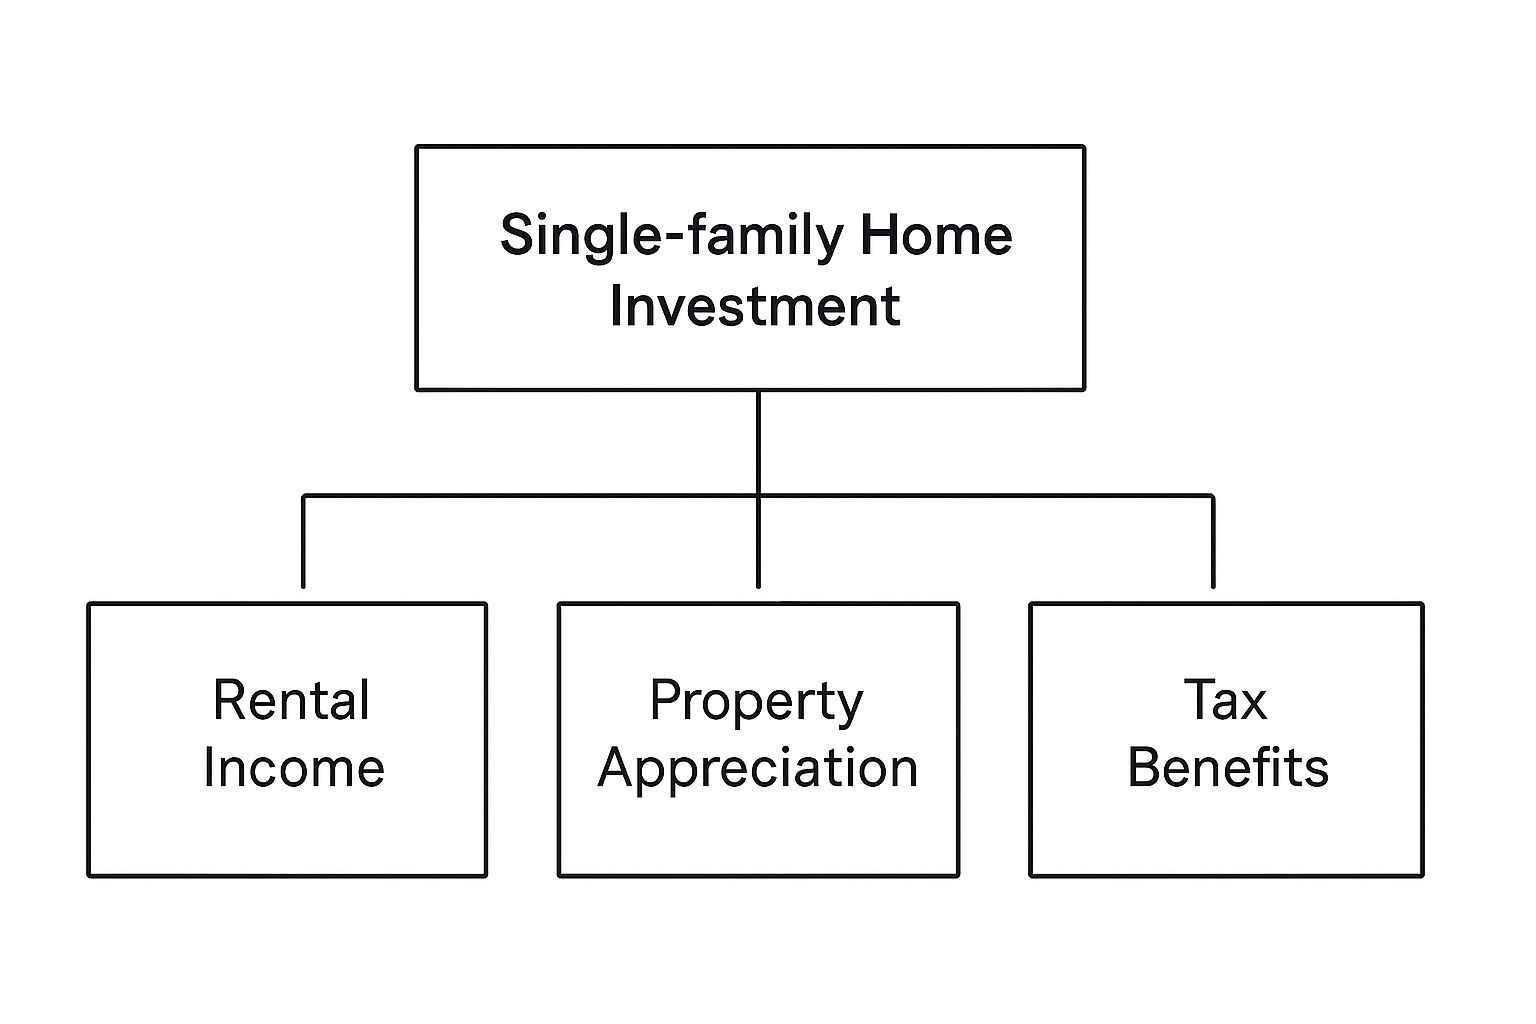
As you can see, the real magic happens when rental income, property appreciation, and tax benefits all start working together. It creates a powerful financial engine.
Key Pillars of a Solid Investment
To really grasp the appeal, it helps to see how single-family homes stack up against other types of residential properties. It's a common debate for investors—many spend time weighing the pros and cons when investing in condos vs. single-family homes to figure out what fits their strategy. More often than not, single-family homes come out on top because of the greater autonomy and wider tenant appeal.
The secret sauce for single-family rentals is their incredibly high demand from a stable tenant base: families. These tenants typically stay longer, which means less turnover, fewer vacancy gaps, and lower costs for you. That directly boosts your bottom line.
To make it even clearer, let's break down the main reasons these properties are such an attractive option for investors.
Key Reasons Single Family Homes Are a Good Investment
This table sums up the primary financial and strategic advantages you get when you add single-family rentals to your portfolio.
| Investment Pillar | Description |
|---|---|
| Rental Income | Generates consistent monthly cash flow to cover expenses and provide profit. |
| Property Appreciation | The home’s value grows over time, building your long-term equity. |
| Tax Benefits | Allows deductions for mortgage interest, property taxes, and depreciation. |
Each of these pillars is strong on its own, but when you combine them, you get a robust investment strategy that has proven itself time and time again.
Building Wealth Through Steady Appreciation
Think of a single-family home as more than just a place to live. It's a silent wealth-building engine, and one of the core reasons why buying single family homes can be a good investment is their tendency to grow in value over time. This process is called appreciation.
This isn’t a matter of luck; it's driven by timeless market forces. People will always need a place to live, and families consistently want the space, privacy, and yard that a single-family home offers. This constant demand, coupled with the fact that they aren't making any more land, naturally pushes property values upward. Your home can quietly compound in value in the background, steadily building your equity without you having to lift a finger.
This steady growth often outpaces other types of residential properties. Over the last decade in the U.S., for instance, single-family home values have appreciated around 3-5% annually on average. That's a solid rate powered by consistent demand in growth markets.
Spotting Markets with High Growth Potential
While appreciation is a broad trend, you can really sharpen your returns by picking the right location. Not all markets are created equal. The key is finding areas that are poised for future growth, which can turn a good investment into a truly great one.
Here are a few forward-looking indicators to keep an eye on:
- Growing Job Markets: A thriving local economy is magnetic. It attracts new residents, which in turn increases housing demand and supports higher rental prices.
- Quality School Districts: Never underestimate the power of good schools. They are a huge draw for families, creating a stable tenant pool and supporting strong property values.
- Community Development: Look for signs of local investment. New parks, retail centers, or public transit projects are all signs that an area is on the upswing.
Appreciation is a long-term game. It's the "slow-and-steady" part of real estate investing that creates generational wealth. While cash flow pays the bills month-to-month, appreciation is what significantly grows your net worth over years.
Understanding this balance is crucial. Appreciation is what boosts your equity, but it’s the rental income that makes sure your investment is sustainable day-to-day. To see how these two pieces work together, you need to have a handle on your potential earnings. You might be interested in our guide on how to calculate rental yield to get a clearer picture of your property's financial performance.
Generating Reliable Cash Flow from High Demand Rentals
While building long-term wealth through appreciation is great, it’s the consistent monthly cash flow that really pays the bills and puts profits in your pocket. This reliable income stream is a huge reason why buying single family homes can be a good investment. Honestly, it's like owning a small, stable business that spins off predictable revenue month after month.
The demand for single-family rentals is just incredibly resilient. You've got a whole range of tenants, from families needing a yard for the kids to professionals who now work from home and crave some privacy. This steady demand is what keeps your property filled and those costly vacancies at bay.
Even when the economy gets a little shaky, the single-family rental (SFR) market has shown remarkable strength. Rental growth has frequently beaten inflation, protecting the real value of your income. We're also seeing the build-to-rent sector expand to keep up with demand from both young families and older renters. The data speaks for itself.
Securing Your Financial Stability
Here’s a simple truth: the key to positive cash flow is minimizing tenant turnover. The core demographic for single-family homes—families—tend to stick around for the long haul. They put down roots in the community and local schools, which means you spend a lot less time and money on marketing, cleaning, and screening new applicants.
That stability has a direct, positive impact on your bottom line. To make sure your investment is solid from day one, you need to understand the numbers lenders look at. For instance, Understanding the Debt Service Coverage Ratio (DSCR) is crucial for getting a loan and confirming your property can easily cover its own mortgage.
The formula is simple but powerful: Longer tenancy equals lower costs and higher profits. Every single month a good tenant stays past their initial lease is a win for your investment.
Of course, managing this all effectively is what separates a successful investment from a headache. For many investors, bringing in a professional is the smartest move to keep the property occupied and handle all the day-to-day details. Partnering with a skilled team for your Fresno property management can protect your asset and truly optimize your cash flow, turning a good investment into a great one.
Taking Advantage of Strategic Tax Breaks and Direct Control
Beyond the obvious benefits of rent checks and rising property values, two of the most compelling reasons to invest in single-family homes are the direct control you have and the significant tax benefits that come with ownership. Think about it: when you own a stock or a mutual fund, you're just along for the ride. With a rental property, you're firmly in the driver's seat.
You get to make every important call. You hand-pick the tenant, you set the rent, you decide which upgrades will actually boost your property's value, and you choose the perfect moment to sell. This hands-on control is a huge leg up over passive investments because you can actively steer your investment toward better performance.
Unlocking Powerful Tax Benefits
The U.S. tax code is surprisingly friendly to real estate investors, and these benefits can directly fatten your wallet. As a landlord, you can legally write off a whole host of operating expenses, which lowers your taxable income for the year.
Some of the most common deductions include:
- Mortgage Interest: The interest you pay on your loan each month.
- Property Taxes: Your annual tax bill from the local government.
- Insurance Premiums: The cost of your landlord insurance policy.
- Repairs and Maintenance: Every dollar you spend keeping the place in great shape.
To really squeeze every drop of profit out of your property, you need to understand the crucial tax deductions for real estate investors available. This knowledge turns everyday expenses into powerful money-saving opportunities.
But the real game-changer is depreciation. The IRS lets you claim this "phantom expense" for the wear and tear on the property over time—even if you didn't spend a dime out-of-pocket. This non-cash deduction can slash your tax bill in a big way.
Navigating these tax rules can feel a bit overwhelming at first, but it’s absolutely essential to get it right. For a deeper dive, check out our guide on how to prepare for tax season when you own a rental. Once you master these advantages, your property isn't just an asset; it's a highly efficient financial machine working for you.
Understanding the Resilience of the Single Family Market
One of the best reasons why buying single family homes can be a good investment is their incredible stability, especially when the rest of the economy feels shaky. I like to think of this market like an ocean liner, not a speedboat—it's built to weather the big waves without getting tossed around.
This resilience comes down to something very simple: human nature.
The constant engine driving housing demand is major life events. People get married, start families, or land a new job in a different city. These things don't just stop happening when the stock market dips. If anything, the huge shift toward remote work has put an even bigger premium on the space and privacy that only a single-family home can really offer.
Built on a Foundation of Consistent Demand
Even when interest rates are all over the place, the basic need for a place to live keeps the market strong. The data backs this up, showing that demand for single-family homes holds up surprisingly well against economic headwinds.
With roughly 86.9 million owner-occupied single-family units in the U.S., their market dominance is undeniable. This demand isn't just from buyers; it's also fueled by renters looking for more space in the suburbs. In fact, construction is still expected to grow despite market uncertainty. You can dig deeper into these U.S. housing market growth trends on Morningstar.com.
All of this consistent demand creates a reliable safety net for your investment capital.
A single-family home isn't just a financial asset; it's a "life-event" asset. Its value is anchored to the biggest and most predictable milestones in people's lives, making it a uniquely recession-resilient investment that provides a safe harbor for your capital.
This underlying stability means you can invest with a lot more confidence. You know your asset is backed by real-world needs that aren't going away, not just speculative trends that can vanish overnight.
Common Questions About Single Family Home Investing
Diving into real estate for the first time can feel like trying to learn a whole new language. To help cut through the noise, we've put together answers to the most common questions we hear from new investors. Getting clear, simple answers is the best way to get past "analysis paralysis" and finally make your first move with confidence.
These are the real-world questions, from figuring out the money side of things to understanding the actual risks you'll face. Let's break them down.
How Much Money Do I Really Need to Start?
Most people are surprised to learn they don't always need a 20% down payment. That number gets thrown around a lot, but options like FHA loans, negotiating seller financing, or even partnering up with someone can drastically lower the cash you need to bring to the table.
The trick is to figure out your "all-in" number. This isn't just the down payment. It also includes:
- Closing costs, which usually land somewhere between 2-5% of the purchase price.
- A contingency fund to cover at least six months of curveballs, like unexpected repairs or a tenant moving out.
Is a Single Family Home Better Than a Duplex?
This one really comes down to your personal goals and how much you want to take on. Single-family homes are fantastic because they tend to attract long-term tenants, like families, which means less turnover for you. They're also simpler to manage and have a huge pool of potential buyers when you decide to sell—you're not just selling to other investors, but to regular homebuyers, too.
A duplex or other small multi-family property, on the other hand, can bring in more cash flow. But they almost always come with more management headaches and a bigger price tag upfront. For a first-timer, a single-family home is often the most manageable way to get your feet wet.
The bottom line is this: Single-family homes offer simplicity and a wider exit strategy, while duplexes can provide more monthly income but demand more from you as a landlord.
What Are the Biggest Hidden Risks to Avoid?
Every investment has risks, but the good thing about real estate is that most of them are predictable. The three biggest gremlins you need to watch out for are a property sitting empty for too long, a sudden and expensive repair, and—the biggest one—choosing the wrong location.
Here’s how you guard against them:
- Keep a healthy cash reserve. You need enough stashed away to cover at least six months of the mortgage, taxes, and insurance, no matter what.
- Always, always get a professional home inspection. This is your best defense against finding out later that the roof or HVAC system is on its last legs.
- Do your homework on the location. Look at the local job market, the quality of the schools, and the general demand for rentals. A strong, stable area is your best insurance policy.
Answering these questions is a great first step, but having an expert partner to guide you can be a game-changer. At Edinhart Realty and Property Management, we provide professional, reliable real estate services to help you find and manage properties that achieve exceptional returns and peace of mind. Learn more about how we can help at https://edinhart.com.


