

A Fresno landlord usually doesn't meet a problem tenant at the application stage. The applicant is friendly, answers questions quickly, and hands over a pay stub that appears complete. The trouble starts later, after the lease is signed and the first rent payment arrives late. By then, the landlord has already made the most important decision.
The answer to what makes a good tenant isn't charm, a polished application, or one impressive credit number. It's a pattern of verifiable payment behavior, stable finances, accurate documents, responsible tenancy, and consistent communication. A reliable screening process finds those patterns while respecting California and federal fair-housing requirements.
The Cost of Picking the Wrong Tenant
A Fresno duplex owner once told me about an application he approved after a pleasant showing and a recent pay stub. He skipped the background check because the applicant seemed responsible, had answered every question politely, and appeared eager to move in.
The first payment arrived late. The next one did too. Within several months, the owner was dealing with five months of late rent, two skip-trace fees, and a $4,800 eviction filing. Those figures came from that individual situation, not a universal estimate, but they show how quickly a weak approval can consume cash and attention in the Central Valley.
The financial damage wasn't limited to unpaid rent. The owner also lost time coordinating notices, locating the tenant, communicating with vendors, preparing the unit, and managing the uncertainty that follows a failed tenancy. A property can look profitable on paper while one avoidable screening mistake disrupts the entire year.
Practical rule: A friendly interview is useful for communication, but it isn't evidence of payment reliability.
The question is not whether every applicant with a thin file will become a problem. The question is whether the landlord has gathered enough independent evidence to make a consistent decision. The Consumer Financial Protection Bureau's tenant-screening report explains that screening commonly involves identity, income and employment, credit, criminal, eviction, rental-payment, bankruptcy, and civil-judgment information.
That layered approach would have raised better questions before move-in. Did the identity match the application? Did the income reconcile with bank activity? Did prior landlords confirm timely payments? Was there an eviction or judgment that a standard credit file didn't show? Good screening doesn't eliminate uncertainty, but it gives a landlord a defensible basis for approving or declining an application.
Traits That Define a Good Tenant
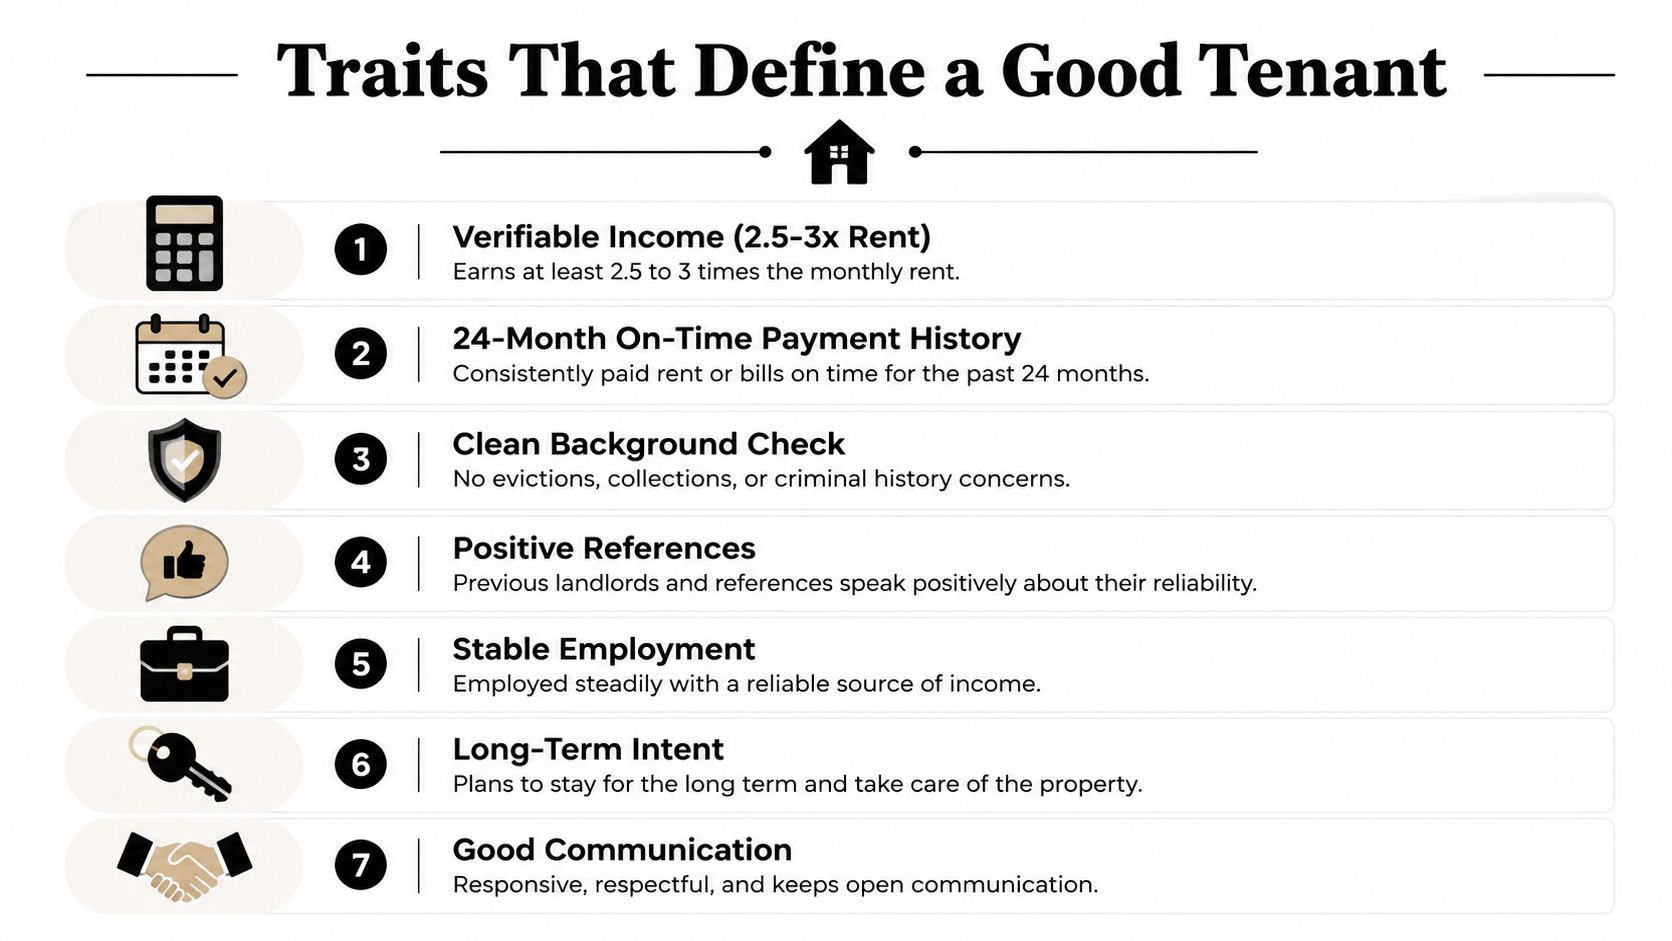
A good tenant is defined by evidence of responsible tenancy, not by personality. During screening, turn every favorable impression into a question that documents or third-party contacts can answer.
- Can the applicant afford the home? Use a gross-income standard of about 2.5 to 3 times monthly rent, a common affordability benchmark described in landlord guidance. Verify wages, benefits where legally required, or self-employment income rather than relying on an unverified application entry.
- Do they pay housing costs on time? Seek rental-payment records covering a meaningful period, ideally including 24 months of on-time payment history when that information is available. Rental history can reveal behavior that a general credit file misses.
- Is income reasonably stable? Confirm the employer, position, start date, hours, and expected continuity. For self-employed applicants, compare tax documentation, invoices, and bank activity instead of accepting a single attractive month.
- Do prior landlords describe responsible conduct? Ask about payment timing, lease compliance, property condition, notices, and disputes. A clean reference should come from an independently verified contact, not only a number supplied by the applicant.
- Does the household fit the property? Confirm the number of occupants and apply the same written occupancy standard to every applicant. Household size should relate to the unit and applicable rules, not personal assumptions.
- Can the identity and documents be verified? Compare the government-issued identification, application details, address history, income documents, and authorized screening data. A strong-looking file becomes risky when those pieces contradict one another.
- Does communication remain respectful and clear? Timely responses, complete documents, and straightforward answers often make the tenancy easier to manage. They're screening observations, not substitutes for verification.
California landlords also need to ask legal questions in the right order. The Fair Chance Act generally limits inquiries into criminal history before a conditional offer, so a landlord shouldn't build a pre-offer process around questions that California law restricts. Screening policies should be reviewed for current state and local requirements before they're used.
Property responsibilities matter after approval too. Clear lease language can prevent disputes over routine care and maintenance, including responsibility for pest-related issues. Landlords who want a practical example can review lease clauses for pest control Florida, while remembering that California leases and local requirements need California-specific review.
These traits connect directly to the two strongest financial questions: can the applicant afford the rent, and have they demonstrated that they pay housing costs reliably?
Why Payment History and Income Benchmarks Matter Most
Income tells you whether an applicant has money coming in. Payment history tells you how that applicant has handled obligations when money was due. You need both.
The CFPB reports that rental-payment information is poorly represented in mainstream consumer-reporting files, with industry estimates covering only 1.7% to 2.3% of U.S. renters. That gap means a landlord who relies only on a conventional credit report may miss the most housing-specific evidence available, especially for applicants who pay rent consistently but have limited traditional credit.
A practical starting point is gross monthly income at 2.5 to 3 times the monthly rent, a benchmark commonly used by independent landlords and property managers. It isn't a guarantee. Someone can meet the income rule and still have unpaid housing obligations, unstable spending, or an unresolved rental dispute.
Verify the number behind the application
For a salaried or hourly employee, compare recent pay records with employer confirmation and, where appropriate, a W-2. For a contractor or self-employed applicant, review 1099 records, tax documentation, business deposits, and bank statements. Don't treat one unusually strong deposit as recurring income.
A co-signer or guarantor can make sense when the applicant has an explainable income shortfall but otherwise satisfies the written policy. The guarantor needs independent verification and a properly drafted agreement. Changing the standard informally for one applicant, while denying another under the same circumstances, creates both financial and fair-housing risk.
| Benchmark | Qualifying Threshold | Documentation Required | Common Pitfall |
|---|---|---|---|
| Income | About 2.5 to 3 times monthly rent | Pay records, employer verification, W-2, 1099, tax or bank records | Counting unverified or irregular deposits |
| Rental payment history | Documented on-time housing payments | Prior landlord confirmation, rental ledger, or rental-payment data | Assuming a credit score proves rent payment behavior |
| Employment continuity | Verifiable current work or self-employment | Employer contact, employment records, contracts, tax or banking evidence | Accepting a recent pay stub without confirming its source |
| Exceptions | Written guarantor or co-signer standard | Independent financial and identity verification | Negotiating case by case without documentation |
Landlords who need a more detailed process can use this tenant income verification guide as a reference. The strongest process applies the same threshold, accepts legally permitted income sources consistently, records exceptions, and explains adverse decisions accurately.
A Layered Screening Process That Works
A single background check leaves blind spots. A defensible process checks identity, finances, rental conduct, and legally permitted records in separate stages, then compares the results for contradictions.
Start with identity
Request government-issued identification and compare the name, date of birth, address history, and application details. A live selfie match or equivalent identity check can help confirm that the person submitting documents is the person named in them. Mismatched addresses and unexplained changes deserve a direct question. Record the applicant's explanation rather than making an assumption.
Verify income independently
Review recent pay documentation, W-2s or 1099s, and a recent bank statement when permitted and necessary. Confirm the employer through an independently sourced contact, not only the phone number printed on the application. The income benchmark is a starting filter. Contradictory evidence still requires investigation.
Review credit, eviction, and public-record information
Use a reputable provider that complies with the Fair Credit Reporting Act for credit and screening reports. Confirm that the identifying information and Social Security number match the application. Examine payment patterns, collections, judgments, bankruptcies, and housing-related records only where they are legally reportable and permitted.
The CFPB tenant-screening market report explains that screening can include credit reports, eviction records, rental payment history, and civil judgments. It also documents more than 26,700 tenant-screening complaints handled from January 2019 through September 2022. Accurate reports and a consistent review process protect both the applicant and the landlord.
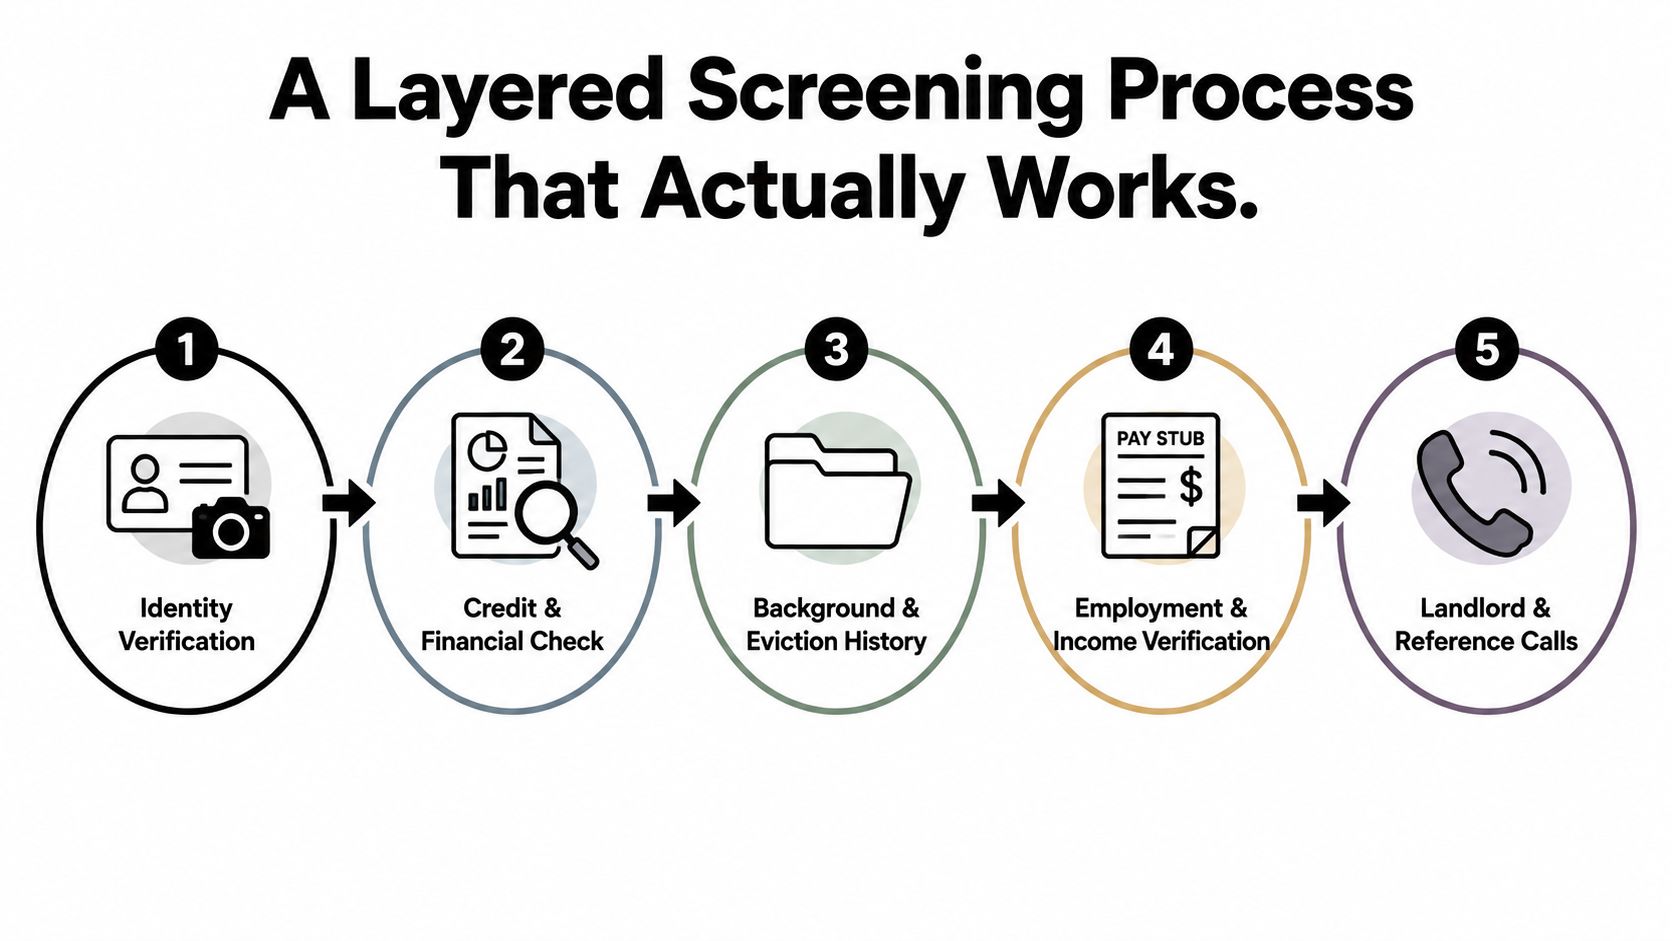
Call landlords with the same script
Call the current and prior landlord using independently verified contact details. Ask:
“Did the applicant pay rent on time and in full under the lease?”
Then ask, “Were there lease violations, repeated complaints, or property-condition issues?” Finish with, “Did the applicant give proper notice, and would you rent to them again?” Record the date, the person's role, the answers, and any uncertainty.
Prior landlord information shows actual housing behavior. Industry screening guidance on landlord and eviction records identifies prior court actions, landlord inquiries, and lease-performance history as useful parts of rental-risk assessment.
Apply criminal screening lawfully
Run any permitted criminal screening consistently and close to the decision date. In California, do not ask restricted criminal-history questions before the appropriate stage. Do not apply a blanket rule that ignores the nature, relevance, and timing of a record. Use one written policy for every applicant, and consult qualified counsel when the law is unclear.
Landlords formalizing these steps can review a practical guide to screening tenants and adapt the workflow to their property, screening provider, and local requirements.
Application Fraud and the New Rules of Screening
A clean credit report doesn't prove that an application is authentic. Industry coverage reports that roughly 1 in 8 rental applications contains some form of fraud, with fake pay stubs identified as the most-forged document and AI-generated document fraud reported as jumping about 500% in 2025. See the rental application fraud guidance from RentButter for the documented context behind those figures.
The practical lesson is simple. Compare documents against independent data. Check whether the employer exists, whether the pay frequency makes sense, whether deposits align with stated earnings, whether addresses reconcile, and whether landlord references belong to real property owners or managers. A synthetic identity or borrowed credit profile can look polished until the application is checked from several directions.
| Fraud Signal to Look For | What a Landlord Can Legally Do |
|---|---|
| Pay stub formatting, totals, or employer details don't reconcile | Request lawful verification through the employer or an appropriate third party |
| Applicant's address history conflicts with the application | Ask for clarification and document the response |
| Reference contact cannot be independently confirmed | Seek an independently sourced landlord or management contact |
| Identity information doesn't match across reports | Pause the decision and follow the provider's identity-resolution process |
| Applicant discloses a material issue after the report finds it | Evaluate the explanation under the same written criteria used for others |
The legal framework is changing as well. Asurint's tenant-screening webinar recap discusses reusable tenant reports, fair-chance housing laws, and restrictions affecting criminal and eviction records, including legislation in Maryland, Illinois, and Colorado that enables reusable or portable reports.
For a Fresno landlord, that means a screening policy can't be a frozen checklist copied from an old form. California's Fair Chance Act affects when criminal-history questions may be asked, while local rules and changing eviction-record practices can affect what information is usable. Use only relevant, legally permitted criteria, provide required notices, protect applicant data, and keep records showing that every applicant went through the same process.
Two Tenants, Two Outcomes
Consider two fictional Central Valley applicants. Profile A has a 720 credit score, income at 3.2 times rent, an impressive résumé, and polished references. On the surface, this is the easy approval.
A direct call to a prior landlord reveals a settled eviction that never appeared on the credit file, along with repeated late payments caused by nonsufficient-funds transactions. The applicant left both facts out of the rental history. The problem isn't just the old event. It's the mismatch between the application and independently verified housing behavior.
Profile B has a 640 credit score and income at 2.7 times rent. The applicant works at a local hospital, has two years of on-time rent confirmed by the prior landlord, and permits a clean move-out inspection to be verified. The credit score deserves review, but the rental-specific evidence is stronger.
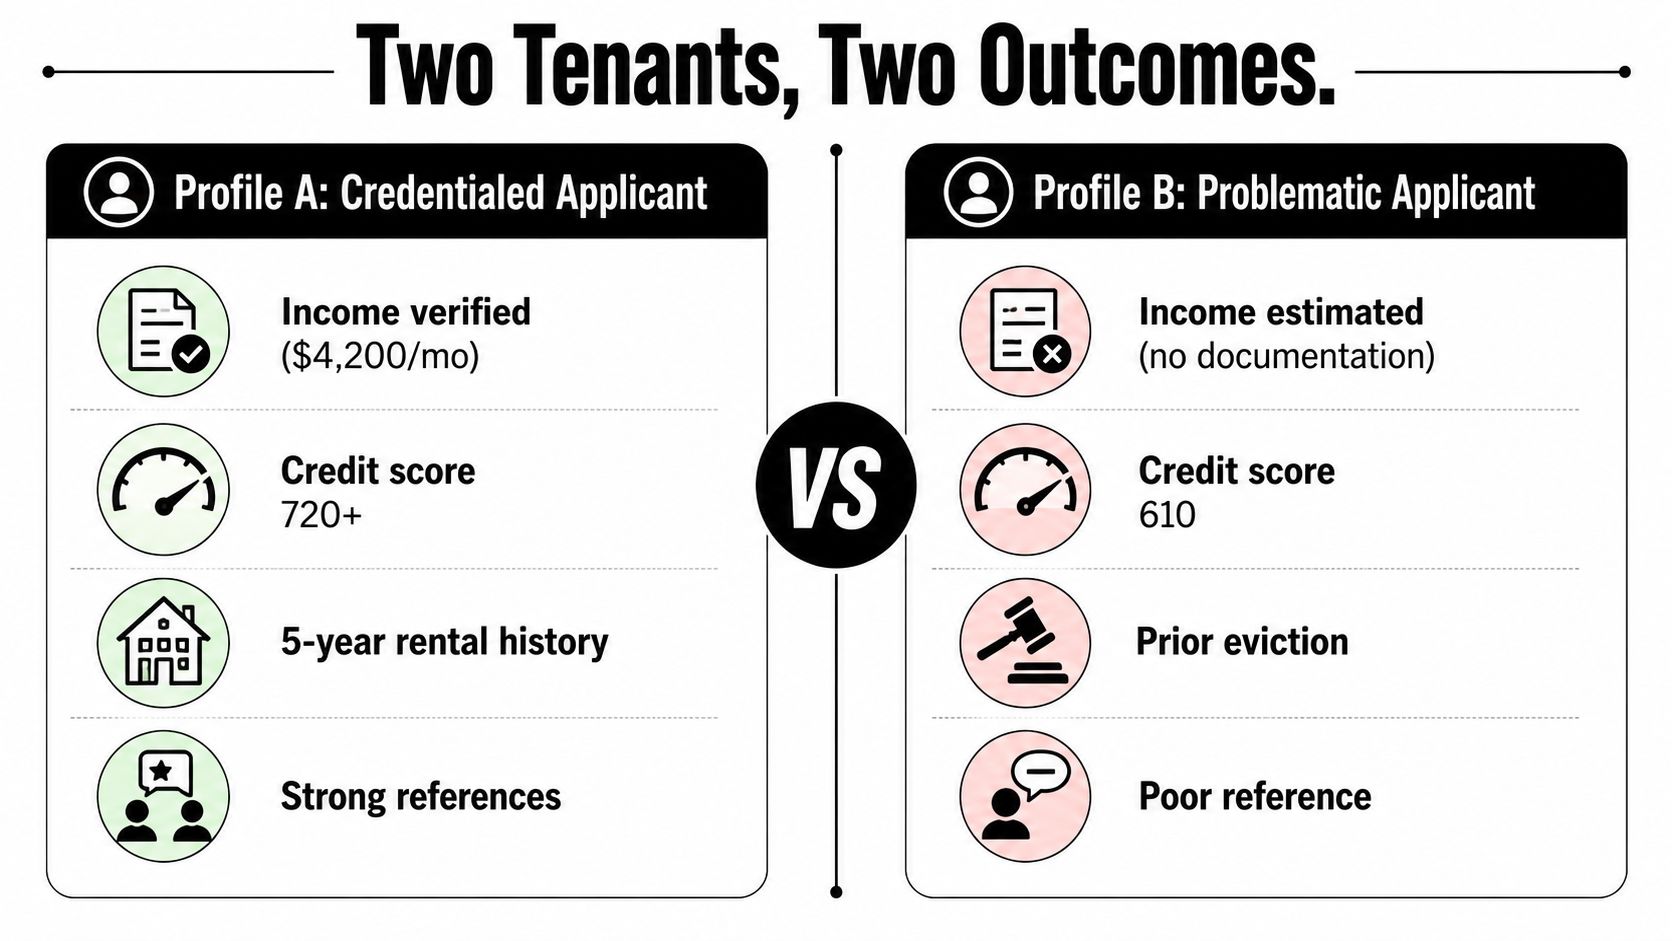
This comparison shows why a score should be one input, not the decision. Experian's rental-history analysis found a 1.56% default rate for applicants with a VantageScore of 700 or higher, compared with 11.20% for applicants in lower score tiers in that study. The source is Experian's rental-history analysis, and it supports using credit as a meaningful risk signal while still combining it with landlord and rental-history checks.
Profile B may require closer financial review, but verified rent payments and consistent employment answer the question that matters most: how has this applicant handled housing obligations? Profile A demonstrates the opposite risk, a strong presentation that fails when the story is checked.
The screening decision should follow the written criteria, not a preference for the more polished résumé.
How to Keep Good Tenants for the Long Haul
Good screening gets the lease started. Good management gives reliable tenants a reason to stay.
Begin with a written move-in condition report. Walk the unit with the tenant, note existing wear, and store timestamped photos in a shared portal. That record protects both parties because maintenance questions and deposit discussions can be measured against the same starting condition.
Make service predictable
Set clear communication standards before problems arise. A tenant portal can centralize rent, messages, notices, and service tickets, while a simple triage system helps the owner decide what needs immediate attention and what can be scheduled.
- Emergency issues: Respond as quickly as the situation requires and coordinate appropriate access.
- Urgent repairs: Acknowledge the request promptly, explain the next step, and keep the tenant updated.
- Routine maintenance: Give a realistic schedule instead of allowing the request to disappear.
A tenant who receives no response may stop reporting small problems. Those small problems can become expensive repairs. Clear communication also creates a record, which is useful when owners, tenants, vendors, and managers remember an event differently.
Renew deliberately
Start renewal conversations well before the lease ends. Review the tenant's payment record, property care, communication, and maintenance history, then apply lawful rent and notice requirements. Covered properties may be subject to California's AB 1482 just-cause and rent-cap rules, so renewal decisions and rent changes should be checked against the property's status and current legal guidance.
For owners building a repeatable retention program, these tenant retention strategies provide a useful operational reference. Practical gestures can reinforce a sound relationship, but they should support, not replace, reliable maintenance and accurate accounting.
A modest renewal improvement, a thoughtful note after a difficult repair, or a convenient portal won't rescue poor management. They can, however, show dependable tenants that the owner notices their cooperation and intends to manage the property professionally.
A Simple Checklist for Fresno Landlords
Use the same sequence for every applicant. A short, repeatable checklist is safer than making exceptions from memory.
- Confirm identity: Match identification, application details, address history, and the screening file.
- Verify income: Use employer, payroll, tax, and bank documentation appropriate to the applicant's work structure.
- Apply the affordability rule: Test gross income against the written 2.5 to 3 times rent standard, while handling permitted income sources consistently.
- Run compliant reports: Obtain applicant authorization and use a Fair Credit Reporting Act compliant provider for credit, background, and eviction screening.
- Check rental conduct: Call two prior landlords where available. Ask about payment timing, lease compliance, property condition, and notice.
- Resolve discrepancies: Pause rather than guess when documents, addresses, identity details, or references conflict.
- Record the decision: Keep the criteria, verification notes, reports, communications, and any required adverse-action notice.
- Manage after approval: Complete a documented move-in inspection, schedule an early check-in, track maintenance, and calendar renewal review.
The written policy should identify qualifying income, report requirements, identity standards, reference questions, occupancy rules, and the process for adverse decisions. It should also state which questions are asked before and after a conditional offer, particularly for criminal-history information in California.
Edinhart Realty and Property Management offers Fresno-area owners both full-service management and placement-only support, including marketing, applicant screening, employment and income verification, rental-history review, lease preparation, rent collection, maintenance coordination, and renewals. If you want a consistent screening process without handling every verification and compliance task alone, visit Edinhart Realty and Property Management to discuss the right management model for your property.
Before approving your next applicant, compare the application against independent identity, income, payment, and landlord-reference evidence. A consistent process won't make every tenancy predictable, but it will give you a far better basis for choosing the tenant most likely to pay, communicate, and care for the home.


