

When you get into real estate investing, you hear a lot about the big-ticket items: cash flow, appreciation, and finding the right tenants. But one of the most powerful wealth-building tools is a little less glamorous: depreciation.
So, what is it? Think of it as an annual tax deduction the IRS gives you to account for the wear and tear on your property. It’s a paper loss that reduces your taxable income each year, but here's the best part—it doesn't actually take a dime out of your pocket.
Understanding Rental Property Depreciation
At its heart, depreciation is the government’s way of saying, "We get it. Buildings don't last forever." Just like a car loses value with every mile, your rental property is slowly aging thanks to tenants, weather, and time. This concept allows you to systematically write off the cost of the building over a set period.
What's really incredible is that you can take this deduction even while your property’s market value is going up. This creates a fantastic advantage for investors. You get to report a non-cash expense that can dramatically lower your tax bill, which means more capital in your hands to reinvest and grow. This is why digging into the numbers, including depreciation, is a key part of any ultimate due diligence checklist before you sign on the dotted line.
The Land vs. The Building
Here’s a crucial distinction every investor needs to get right from day one: you can only depreciate the building, not the land it sits on. The IRS sees land as something that doesn't wear out, so it’s not eligible for the write-off.
This means one of your first tasks is to split the property's total value into two buckets:
- The Building: This is your depreciable asset.
- The Land: This is not depreciable.
You can typically find this breakdown on your local property tax assessment or by getting a professional appraisal.
Why This Deduction Is a Game-Changer
For serious investors, mastering depreciation is non-negotiable. In the U.S., residential rental properties are depreciated over a standard 27.5-year schedule.
Let’s run a quick example. Say the building portion of your new rental is valued at $275,000. By dividing that number by 27.5 years, you get an annual depreciation deduction of $10,000. That’s $10,000 you can subtract from your rental income, lowering your tax liability. Just keep in mind that when you eventually sell, the IRS will want some of that back through a process called "depreciation recapture," but that's a topic for another day.
To make these core ideas easier to grasp, here’s a quick summary table.
Depreciation At a Glance Key Concepts
| Concept | What It Means for Investors |
|---|---|
| Depreciation Deduction | An annual tax write-off for the building's wear and tear. It’s a "paper loss." |
| Useful Life | The IRS-set period for depreciation. For residential rentals, it's 27.5 years. |
| Cost Basis | The value of the building (not the land). This is the number you'll depreciate. |
| Taxable Income Reduction | Depreciation directly lowers your taxable rental income, saving you money on taxes. |
| Depreciation Recapture | When you sell, the IRS may tax the total depreciation you've claimed over the years. |
This table provides a snapshot of the key terms you'll encounter. Getting comfortable with them is the first step toward building a smarter, more profitable real estate portfolio.
How the IRS Defines Depreciation for Rentals
To really get the most out of depreciation, you have to play by the official rulebook—the one written by the IRS. The government has a specific checklist your property needs to satisfy before you can start claiming this powerful deduction. Think of these rules as the foundation of your entire tax strategy.
First, you have to own the property. Seems obvious, but it’s the non-negotiable first step. Second, the property must be used to produce income, which means it’s a rental, not the home you live in or a personal vacation spot.
Finally, it needs a "determinable useful life," which is just a formal way of saying it wears out over time. Luckily, for residential real estate, the IRS has already figured this part out for us.
The MACRS Framework Explained
The system that governs all of this is called the Modified Accelerated Cost Recovery System, or MACRS. It sounds complicated, but its purpose is simple: it’s the framework that tells you exactly how to depreciate your assets over time. If your property was put into service after 1986, MACRS is the only system you need to worry about.
Under MACRS, every asset gets a "recovery period"—IRS-speak for its useful life. This is simply the number of years you get to spread the asset's cost over.
Key Takeaway: The MACRS system gives investors a clear, standardized timeline for deducting a rental property's cost. For any residential rental in the U.S., that recovery period is a firm 27.5 years.
This fixed timeline is a huge help. You don't have to guess how long your property will last or justify your numbers. The IRS lays out a clear path for every residential investor, which brings consistency and predictability to your tax planning.
Demystifying Key IRS Terminology
To really master MACRS, you just need to get comfortable with three core concepts. Once you understand these terms, you’ll have the confidence to apply the rules to your own portfolio and know exactly what rental property depreciation means from a tax perspective.
- Cost Basis: This is your starting number for any calculation. It's the total amount you have invested in the property—the purchase price plus certain closing costs, but always excluding the value of the land itself.
- Placed in Service Date: Depreciation doesn't kick in the day you get the keys. It starts on the date the property is ready and available for a tenant to move in. That might be the day you close, or it could be months later if you’re doing renovations.
- Recovery Period: As we mentioned, this is the asset’s lifespan according to the IRS. For the building itself, it's 27.5 years. For other things like appliances or a new fence, the recovery period is much shorter.
Interestingly, these rules can change based on where your property is. The depreciation rules for properties outside the U.S. are quite different, with foreign residential rentals typically depreciated over a 30-year period. This longer schedule can open up unique tax strategies for investors with an international portfolio. If you own or are thinking of buying abroad, it's worth exploring these insights about international property depreciation.
Getting a handle on these foundational IRS rules is the crucial next step. With this knowledge in your back pocket, you’re ready to move from theory to practice and start running the numbers.
Calculating Your Annual Depreciation Deduction
Alright, now that we've covered the IRS rules, let's roll up our sleeves and put this into practice. Figuring out your annual depreciation deduction is actually pretty simple once you have the right numbers in front of you. This is where you turn your property's value into a real, tangible tax benefit that trims your taxable income every single year.
The entire calculation starts with one crucial number: your property's cost basis. And no, this isn't just the price you paid for the house. Your cost basis is the total amount you've sunk into acquiring the property, which can include certain closing costs, but it never includes the value of the land itself.
This infographic breaks the whole thing down into three easy-to-follow steps.
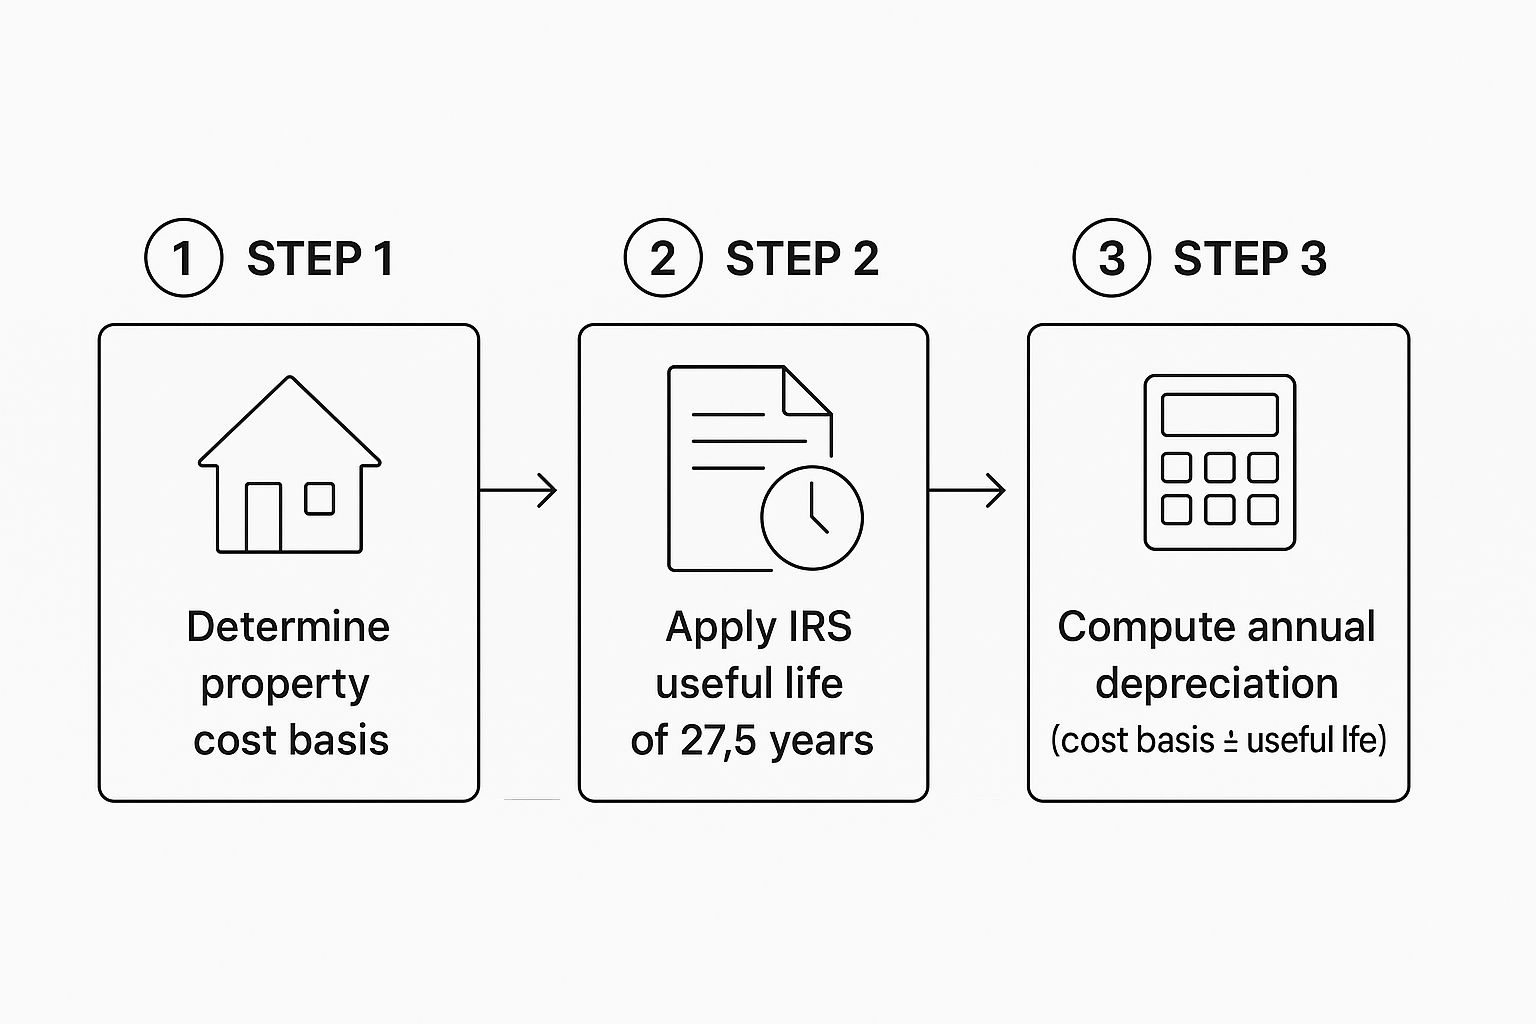
As you can see, the process is logical. You establish your basis, apply the standard 27.5-year useful life, and out comes your annual deduction. Simple as that.
Step 1: Determine Your Cost Basis
First things first, we need to nail down the full cost basis of the property. This includes the purchase price plus any other expenses you paid to get the deal done.
- Purchase Price: This one's easy—it's what you paid for the property.
- Closing Costs: You can often add certain fees from the sale, like legal fees, recording fees, and title insurance.
- Abstract Fees: These are the costs associated with researching the property's title history.
Let's use an example. Say you bought a rental home for $400,000. You also paid $10,000 in closing costs that qualify. That brings your total cost basis for the entire property (both the land and the building) to $410,000.
Step 2: Separate Land Value from Building Value
This next step is absolutely critical. As we've mentioned, the IRS doesn't let you depreciate land. You have to split that total cost basis between the land and the actual building.
A common, IRS-approved way to do this is to check your property tax assessment. Your local assessor has already done the work for you. Let's imagine your assessment values the land at 20% of the property's total value and the building at 80%.
Now, let's apply this to our $410,000 cost basis:
- Land Value: $410,000 x 20% = $82,000 (This portion is not depreciable.)
- Building Value: $410,000 x 80% = $328,000 (This is your depreciable basis.)
So, the magic number we'll use for our final calculation is $328,000.
Pro Tip: Keep meticulous records of every single acquisition cost. Using the https://edinhart.com/best-accounting-software-for-rental-properties/ can make tracking these figures a breeze, ensuring you lock in the correct cost basis from day one.
Step 3: Calculate the Annual Deduction
With your depreciable basis locked in, the final math is straightforward. We'll use the straight-line method, dividing the building's value by its IRS-mandated useful life of 27.5 years.
The formula looks like this: Depreciable Basis / 27.5 Years = Annual Depreciation Deduction
Plugging in our numbers:
- $328,000 / 27.5 Years = $11,927.27 per year
That's it! You can deduct $11,927.27 from your rental income for every full year you own the property. It's a powerful "on-paper" expense that directly lowers your tax bill. As you grow your portfolio, modern asset depreciation software can make this whole process even easier.
Understanding the Mid-Month Convention
There's one last little quirk from the IRS to keep in mind: the mid-month convention. Essentially, the IRS assumes you placed your property in service in the middle of the month you bought it, no matter the actual date.
This means that for your first year, you'll only claim a partial deduction. For instance, if your property goes into service in October, you get to claim depreciation for 2.5 months—half of October, plus all of November and December.
The same rule applies in the year you sell the property. You'll claim a partial deduction based on the month of the sale. It’s the IRS's way of making sure the first and last years of ownership are calculated fairly.
Depreciating Improvements And Other Assets
When you start depreciating your rental property, it’s easy to focus only on the main building. But savvy investors know the real power lies in looking closer at all the other assets that make up the property.
Think of it this way: the building's structure is like the body of a car—it lasts a long time and loses value slowly. But what about the tires, the stereo system, or the custom floor mats? They wear out much faster. The IRS sees your rental property in a similar light, recognizing that different components have different lifespans.
This is a game-changer because it allows you to claim bigger deductions much sooner, boosting your cash flow right when you need it most.
Capital Improvements vs. Personal Property
The first step is to stop seeing your property as one big expense and start viewing it as a collection of individual assets. The IRS puts these items into two main buckets, each with its own depreciation schedule.
Capital Improvements: These are the big-ticket items that substantially upgrade the property, extend its usable life, or adapt it for a new purpose. We’re talking about a brand-new roof, a complete kitchen overhaul, or adding a second bathroom. These are considered part of the building and get depreciated over 27.5 years.
Personal Property: This is everything else that isn't structurally bolted down. Things like refrigerators, dishwashers, carpets, and even blinds fall into this category. Since these items have a much shorter life, the IRS lets you write them off faster—typically over 5 or 7 years.
Zeroing in on these shorter-lived assets is the secret to accelerating your depreciation and maximizing your tax savings year after year.
The Power of Cost Segregation
There's a formal name for this strategy of identifying and separating property components to speed up their depreciation: cost segregation. It might sound like a complex accounting term, but the idea is simple. You’re just giving every asset its own, more accurate (and shorter) depreciation timeline instead of lumping it all into the 27.5-year building category.
A cost segregation study is hands-down one of the most impactful tax strategies for real estate investors. By breaking down a property's components, you can pull deductions forward, which directly improves your immediate cash flow and shrinks your current tax bill.
For example, without cost segregation, you’d depreciate a whole kitchen remodel over 27.5 years. But with it, you can get specific: the new cabinets might be 27.5-year property, but that new stove, fridge, and microwave are 5-year personal property.
This approach front-loads your tax savings, putting more money in your pocket today to reinvest, rather than waiting nearly three decades to get the full tax benefit.
Comparing Depreciation Timelines
Laying out the different recovery periods side-by-side really makes the financial impact of this strategy pop. An investor who takes the time to properly classify assets will see far larger tax deductions in the early years compared to one who doesn't.
Here’s a quick breakdown of how different rental property assets are treated under the MACRS framework.
Depreciation Timelines for Different Rental Property Assets
| Asset Type | Typical Recovery Period (MACRS) | Example |
|---|---|---|
| Residential Building | 27.5 years | The structure, roof, walls, and foundation |
| Land Improvements | 15 years | Fencing, driveways, and landscaping |
| Personal Property | 7 years | Office furniture or fixtures |
| Personal Property | 5 years | Appliances, carpeting, and window blinds |
The numbers don't lie. If you correctly classify a $5,000 appliance package as 5-year property, you get a $1,000 annual deduction (before applying tax conventions). But if you mistakenly lump it in with the building's 27.5-year schedule, your deduction shrinks to just $182. That’s a huge difference that adds up quickly.
Ready to Speed Things Up? Advanced Deduction Strategies
The standard 27.5-year depreciation schedule is great, but what if you could get more of your tax savings sooner? For savvy investors, there are ways to do just that.
Think of it as front-loading your deductions. Instead of patiently waiting nearly three decades to write off certain assets, advanced strategies let you claim a huge chunk of the cost in the very first year. This can give your cash flow a serious, immediate boost.
We're mainly talking about the "stuff" inside your rental here—things with a useful life of 20 years or less, like appliances, new carpet, and light fixtures. Two of the most powerful tools for this are bonus depreciation and the Section 179 deduction. Let's break down how they work.
Tapping Into Bonus Depreciation
Bonus depreciation has long been a favorite tool for real estate investors. It lets you deduct a massive percentage of an asset's cost right away, in the year you put it into service. This isn't a slow trickle; it's a tidal wave of a deduction that can drastically reduce your taxable income.
For example, say you spend $10,000 on new appliances for your rental. If the current bonus depreciation rate is 80%, you could deduct $8,000 of that cost on this year's taxes. That’s a much bigger win than the small deduction you'd get from the standard 5-year MACRS schedule.
The Tax Cuts and Jobs Act of 2017 famously supercharged this by allowing a 100% deduction for a time. While that rate has since been adjusted, bonus depreciation remains a go-to strategy. Tax laws are always shifting, so keeping an eye on the current rules is key. You can dig deeper into the latest rules for bonus deductions on wipfli.com.
Understanding the Section 179 Deduction
Section 179 is another fantastic way to write off property-related purchases. It was designed to help small businesses by allowing them to deduct the full purchase price of qualifying equipment and software in the year it's acquired.
Important Note for Landlords: This one comes with a catch for residential rentals. You generally can't use the Section 179 deduction for assets inside the home itself, like the stove or refrigerator.
So, where can you use it? It typically applies to items used for the business side of your rental operations, but located outside the actual rental unit.
- Office Furniture: A desk and chair for your separate property management office.
- Computers & Software: The laptop and software you use exclusively to manage your portfolio.
- Equipment: Lawnmowers, tools, and other machinery you use for property maintenance.
While you can't use it for that new dishwasher, Section 179 is still a valuable tool for the equipment that keeps your rental business running. Because these advanced strategies have specific rules, it’s always smart to talk with a tax professional. They can help you figure out exactly what you qualify for and make sure you’re getting every last deduction you're entitled to without getting into hot water with the IRS.
Understanding Depreciation Recapture When You Sell
Depreciation is an amazing tool for lowering your taxable income each year, but every savvy investor needs to play the long game. The tax breaks you enjoy today will directly impact your tax bill when you finally sell the property. This is where a concept called depreciation recapture enters the picture.
Think of it as the IRS's way of balancing the books. They've let you take deductions for years, which lowered your taxes. So, when you sell for a profit, they want to "recapture" a portion of that benefit. It’s not a penalty—it’s just a different way of taxing the specific part of your gain that came from all those depreciation deductions.
Getting a handle on this process is absolutely fundamental for smart, long-term financial planning with your real estate investments.
How Recapture Works on Your Cost Basis
Every single dollar of depreciation you claim chips away at your property's adjusted cost basis. Why does that matter? A lower cost basis means a larger taxable profit when you sell.
Here’s an analogy: Picture your cost basis as the starting line in a race. Each year, your depreciation deduction pushes that starting line further back. When you eventually sell and cross the finish line (the sale price), the distance you've "run"—your taxable gain—is much longer simply because of where you started.
This bigger gain is then split into two distinct buckets for tax purposes: the capital gain and the recaptured depreciation.
The Depreciation Recapture Tax Rate
This is where things get interesting. The IRS applies a special tax rate to the portion of your gain that comes from depreciation. While long-term capital gains are usually taxed at friendly rates of 0%, 15%, or 20%, recaptured depreciation gets treated differently.
The part of your gain attributed to depreciation is taxed at your ordinary income tax rate, up to a maximum of 25%. This is a critical number every investor needs to remember when forecasting the net cash from a future sale.
Any profit left over beyond the recaptured amount is treated as a standard capital gain and gets taxed at those lower capital gains rates. This two-part tax treatment is exactly why calculating your final bill isn't always a simple affair.
A Real-World Recapture Example
Let’s walk through a clear example to see how this all shakes out.
- Purchase and Basis: You buy a rental property, and the building's cost basis is $328,000.
- Depreciation Claimed: Over 10 years, you claim a total of $119,273 in depreciation deductions.
- Adjusted Basis: Your new, adjusted cost basis is now $208,727 ($328,000 – $119,273).
- Sale Price: You sell the property, and your net proceeds after closing costs are $500,000.
- Total Gain: Your total taxable gain is a whopping $291,273 ($500,000 sale price – $208,727 adjusted basis).
Now, the IRS steps in and splits that gain:
- Depreciation Recapture: The first $119,273 of your profit is taxed at the recapture rate (your income tax rate, capped at 25%).
- Capital Gain: The remaining $172,000 ($291,273 – $119,273) is taxed at the much more favorable long-term capital gains rate.
This knowledge is power. It lets you plan for your future tax liability instead of being surprised by it. For investors looking to kick that tax can down the road entirely, it’s worth learning more about the powerful benefits of a 1031 exchange to roll your gains into a new investment property.
A Few Final Questions About Depreciation
As we wrap up, it's totally normal to have a few lingering questions. Let's run through some of the most common ones we hear from investors to make sure you're ready to put these ideas into action.
Do I Really Have to Claim Depreciation on My Rental Property?
Yes, you absolutely do. The IRS doesn’t really see this as an optional deduction you can just skip. It all comes down to their "allowed or allowable" rule.
What this means is that even if you don't take the depreciation deduction each year, the IRS will still calculate your property's final basis as if you had when you eventually sell it. You can't sidestep depreciation recapture by simply not claiming the deduction. The IRS reduces your basis either way, so you might as well take the tax break you're entitled to.
Can I Depreciate the Land My Rental Is On?
That's a hard no. The IRS views land as something with an infinite lifespan—it doesn't wear out or get used up like a building does. Because of that, it's never depreciable.
This is why you have to split your property's total cost between the land and the building itself.
A simple and widely accepted way to do this is by looking at your local property tax assessor's statement. It usually provides separate values for the land and the structure. An official appraisal will also get the job done.
What Happens If I Make a Major Improvement?
Big upgrades that add real value or extend your property's life—think a brand-new roof or a full kitchen remodel—are handled like new assets. You'll start a fresh depreciation clock for that specific improvement in the month you put it into service.
Typically, that improvement gets its own 27.5-year depreciation schedule, just like the original building. It's crucial to keep these capital improvements separate from routine repairs and to understand the full range of landlord tax write-offs available to you.
Juggling depreciation rules can feel like a lot, but you don’t have to go it alone. The experts at Edinhart Realty and Property Management are here to help you navigate the financial side of your investments, making sure you maximize every return while staying compliant. See how we can help at https://edinhart.com.


