

When you’re buying a house, you’ll hear the term earnest money deposit thrown around a lot. So, what is it? Think of it as a good-faith payment that tells the seller, "Hey, I'm serious about buying your home." It’s not some extra fee you have to cough up; it’s actually part of the total cash you'll need for the purchase.
This money gets held in a neutral account (more on that later) until closing day, kind of like a security deposit when you rent an apartment. Putting down this deposit gives the seller the confidence they need to take their home off the market and start the closing process with you.
What Is an Earnest Money Deposit Anyway?
Imagine you’re shaking hands on a deal. The earnest money deposit is the financial version of that firm handshake. It’s a powerful, tangible way to show the seller you aren't just kicking tires—you genuinely intend to follow through and buy their property. Once your offer is accepted, this deposit essentially puts a "reserved" sign on the house for you. This stops the seller from entertaining other offers while you get your ducks in a row with inspections and financing.
Now, don't mix this up with your down payment. While they're related, they aren't the same thing. The earnest money is paid right after the purchase agreement is signed, while the much larger down payment is paid at the final closing. The great news? In almost every case, your earnest money gets credited right back to you, usually going toward your down payment or closing costs. This means less cash you need to bring to the table on the big day.
For a quick overview, here's a simple breakdown of what an earnest money deposit involves.
Earnest Money Deposit at a Glance
| Key Aspect | Brief Explanation |
|---|---|
| What It Is | A "good-faith" payment made by a buyer to a seller. |
| Main Purpose | To show the buyer is serious and financially committed. |
| Typical Amount | Usually 1% to 3% of the home's purchase price. |
| Who Holds It | A neutral third party, like a title or escrow company. |
| What Happens to It | Typically applied toward the buyer's down payment or closing costs. |
| Is It Refundable? | Yes, if the buyer backs out due to a contingency in the contract. |
This table provides a snapshot, but let's dig into why this deposit is so crucial for both sides of the deal.
The Purpose Behind the Deposit
So, what’s the main job of this deposit? It really serves two key purposes, protecting both the buyer and the seller in the transaction.
- For the Seller: It's financial peace of mind. If a buyer gets cold feet and walks away for a reason not covered by the contract, the seller often gets to keep the deposit. This compensates them for the time and potential buyers they lost while their home was off the market.
- For the Buyer: It makes your offer stand out, especially when you're up against other buyers. In a hot market, a solid deposit can be the very thing that convinces a seller to pick your offer over someone else's.
An earnest money deposit is a tangible sign of commitment that builds trust between both parties. It transforms a simple offer into a secured agreement, paving the way for a successful transaction.
The whole system is designed to be fair and square. The money isn't handed directly to the seller. Instead, it’s held by a neutral third party, like a title company or an escrow agent. This makes sure your money is handled exactly as laid out in your purchase agreement, keeping your investment safe until the deal is done.
The Role of Earnest Money in a Real Estate Deal
An earnest money deposit does more than just show you're serious about buying a home. Think of it as your opening move in a high-stakes game. It doesn't win the whole thing on its own, but it definitely sets the tone for every move that follows, showing your commitment right from the start.
This deposit sends a powerful message to the seller. In a market full of casual lookers and half-hearted inquiries, your earnest money tells them you’re a real player, ready to put actual funds on the line. It's the proof they need to confidently take their home off the market, trusting that you won’t just disappear.
This single act of financial commitment is what turns an offer from a piece of paper into a real, binding agreement with skin in the game for everyone involved.
Building Trust and Proving You’ve Got the Funds
In any major deal, trust is everything. An earnest money deposit is a fast way to build it. It instantly proves two critical things to the seller: you have the money to back up your offer, and you're serious about seeing this through.
Sellers take a huge risk when they accept an offer. They pull their marketing, stop showing the house, and say "no" to other potential buyers. Your deposit is their safety net, assuring them you’re just as invested in closing as they are. It’s a clear signal you’ve done your financial homework and are ready for homeownership.
A strong deposit can make a seller feel a whole lot better about moving forward, especially if they have any doubts about a buyer's qualifications.
Gaining an Edge in a Bidding War
Imagine a seller gets three similar offers. How do they pick one? While the price is obviously a huge factor, the earnest money deposit often becomes the tiebreaker. In a hot market, a bigger deposit can make your offer shout "I'm the reliable choice!" louder than the rest.
Let's break down a quick scenario:
- Buyer A offers the asking price with a 1% earnest money deposit.
- Buyer B offers a little over the asking price but still with a standard 1% deposit.
- You (Buyer C) offer the asking price but put down a 3% earnest money deposit.
Even though Buyer B offered more cash, the seller might go with your offer. Why? Your larger deposit signals that you're less of a risk. It suggests you're financially solid and less likely to get cold feet, giving the seller the peace of mind they need to say yes. A good real estate agent can explain how to find a realtor who gets these local dynamics and can help you craft an offer that stands out.
A substantial earnest money deposit is one of the smartest ways to make your offer shine in a multiple-bid situation. It’s a strategic move to show the seller you are the most dependable choice.
In competitive markets all over the world, earnest money deposits have a real impact on how quickly and successfully deals close. The data shows that a deposit of 3% or higher can seriously boost your offer's chances, particularly in seller's markets like San Francisco and Miami where sellers often expect it.
More Than Money—It's a Negotiation Tool
At the end of the day, your earnest money is a key part of your negotiation strategy. It’s not just a box to check; it’s a statement. By adjusting the amount, you can signal different levels of seriousness and financial strength, which can be a huge advantage in tricky negotiations.
This deposit is woven into the very fabric of the home buying process, acting as the financial backbone of the agreement until closing. To get the full picture, it's helpful to see how this fits into the broader UK house buying process step by step, which is built on similar principles. From building that initial trust to sealing the deal in a competitive market, earnest money is the indispensable element that keeps everything moving forward.
How Much Earnest Money Should You Offer?
Figuring out the right amount for your earnest money deposit is less about following a rigid rule and more about smart strategy. It’s your first real financial signal to the seller, telling them just how serious you are about buying their home. While there’s no magic number, there are some solid industry benchmarks to get you started.
Most of the time, an earnest money deposit lands somewhere between 1% and 3% of the home's purchase price. So, for a $400,000 house, you'd be looking at a deposit between $4,000 and $12,000. But that's just a ballpark. The biggest factor that will push that number up or down is what’s happening in your local real estate market right now.
Adjusting Your Offer for Market Conditions
The real estate market is always shifting. Whether you’re in a hot seller's market, a cool buyer's market, or something in between will completely change what's considered a compelling offer. Getting a feel for these dynamics is key to making an offer that actually gets the seller's attention.
In a crazy seller's market, where homes get multiple offers and bidding wars are the norm, a standard 1% deposit just won't cut it. To stand out, you might need to bump your deposit up to 3% or even more. This tells the seller you're not just serious—you're financially solid and less likely to get cold feet.
On the flip side, in a buyer's market, the power shifts to you. With more houses than buyers, sellers are more flexible. A deposit on the lower end, around 1%, is usually perfectly fine. This frees up your cash for other upfront costs like the home inspection and appraisal, without making your offer look weak.
This infographic breaks down how the market temperature affects the expected deposit amount.
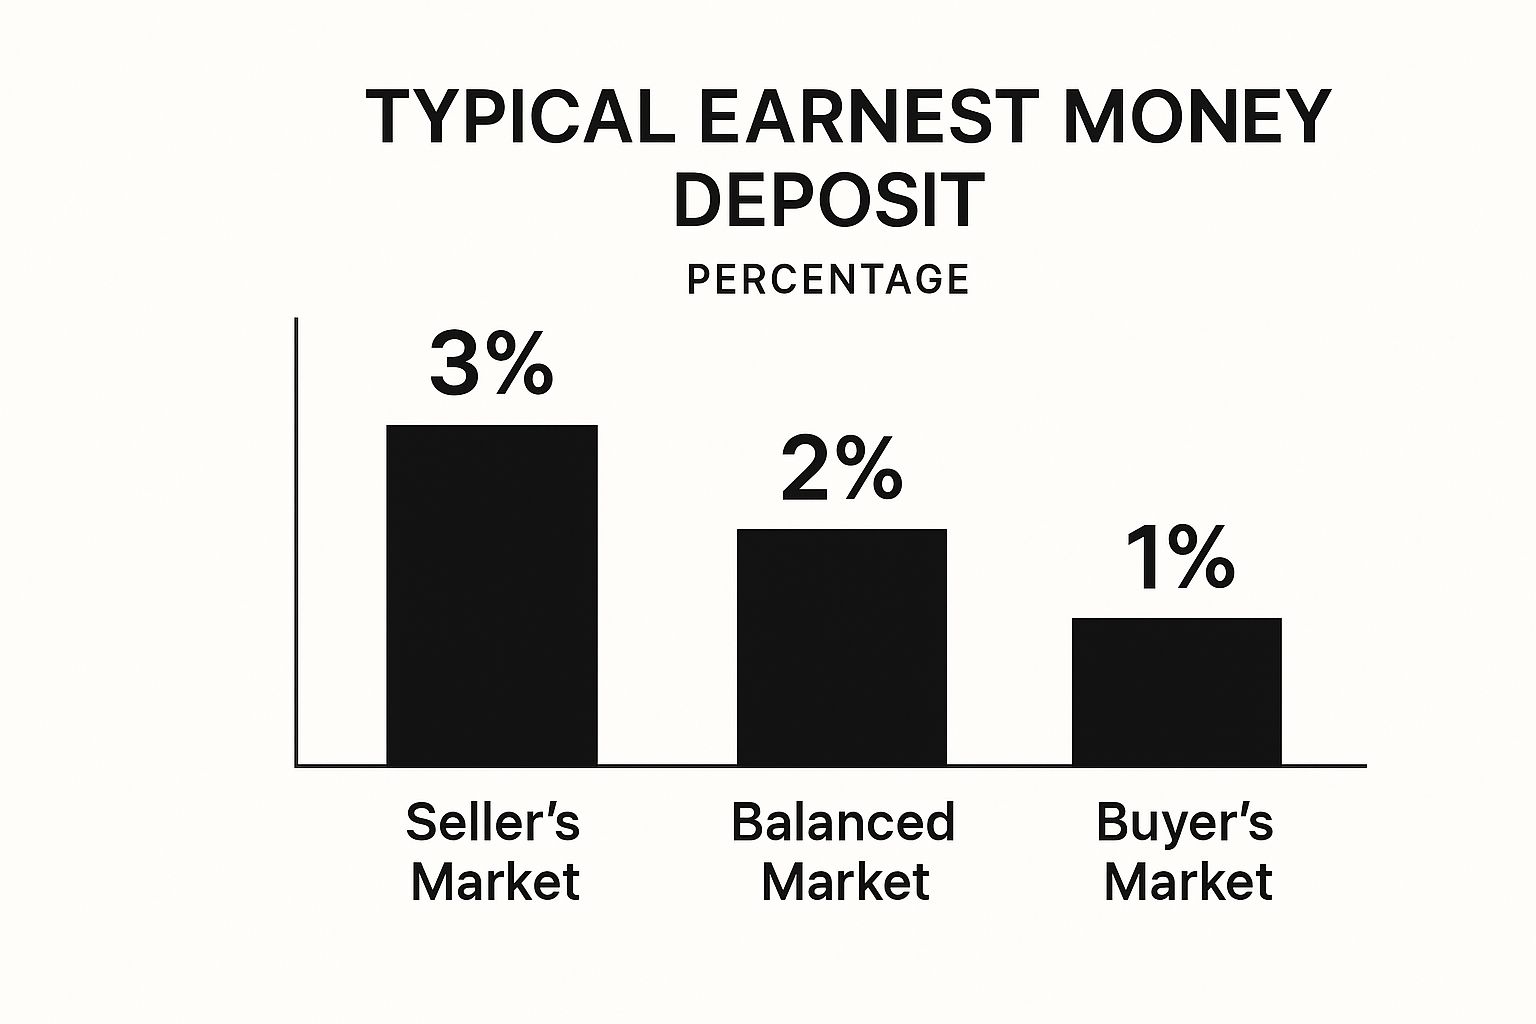
As you can see, the hotter the market, the bigger the good-faith deposit sellers will expect to see.
Before you decide on a final number, it's a good idea to look at how different market conditions influence the earnest money deposit.
A quick look at typical earnest money percentages can help you position your offer strategically.
Earnest Money Amount by Market Type
| Market Type | Typical Percentage | Strategic Consideration |
|---|---|---|
| Seller's Market | 2% – 5% or more | A higher amount shows you're a serious contender and can help you win a bidding war. |
| Balanced Market | 1% – 3% | The standard range is usually sufficient. Your agent can advise based on the specific property. |
| Buyer's Market | 1% | You have more leverage. A lower deposit is acceptable and keeps more cash in your pocket. |
Ultimately, the goal is to make an offer that is both competitive and comfortable for your financial situation.
National Averages and High-Cost Areas
Nationwide, earnest money deposits tend to hover between 1% and 5% of the sale price, with 3% being a common sweet spot. But in super competitive, high-end markets like those in South Florida, New York, or Silicon Valley, it's not unusual to see deposits climb as high as 10%.
Think about it: a 3% deposit on a median-priced $2.1 million home in Silicon Valley is a whopping $63,000. It just goes to show how much local conditions can shape what sellers expect.
This is where having a great real estate agent in your corner is priceless. They know the local customs and can guide you. For more tips on putting together a winning offer, check out these essential first-time home buyer tips.
Is a Larger Deposit Always Better?
Putting down a bigger earnest money deposit can definitely make your offer pop, especially in a competitive situation. It screams commitment. But it's a move you need to think through carefully.
Going big means you have more skin in the game—and more to lose. If you back out of the deal for a reason that isn't covered by one of your contingencies (like just changing your mind), you could say goodbye to that entire deposit.
Strategic Consideration: You have to find the right balance between making your offer attractive and protecting your money. Never offer more than you are prepared to potentially lose, and make sure your purchase agreement has clear contingencies to cover your bases.
Before you write that check, have a frank conversation with your real estate agent. They’ll have the inside scoop on what local sellers are looking for and can help you weigh the pros and cons of a larger deposit versus the risks involved.
Safeguarding Your Deposit Through Escrow
So, your offer got accepted—congratulations! The next big question is, where does that chunk of cash you’re putting down for earnest money actually go? It’s a common worry that it lands directly in the seller's bank account, but that couldn’t be further from the truth. Your deposit is carefully protected through a process called escrow.
Think of escrow as a secure, neutral holding zone for your money. It’s managed by an impartial third party, like a title company, an escrow agent, or even a real estate brokerage's trust account. This third party is like a referee in the transaction, holding onto your deposit until every condition in the purchase agreement has been met by both you and the seller.
This entire system is built on trust and fairness. It’s a critical safeguard that stops the seller from touching your money before the deal is done and guarantees it’s only used according to the legally binding contract you both signed.
How the Escrow Process Works
From the moment you wire your deposit to the day you get the keys to your new home, the escrow process follows a very clear, structured path. It's designed to be transparent and protect your financial interests every step of the way.
Here’s a play-by-play of your earnest money's journey:
- Deposit Submitted: Once your offer is accepted, you’ll have a few days to get your earnest money to the designated escrow holder, usually through a wire transfer or a certified check.
- Funds Secured: The escrow agent immediately deposits your funds into a dedicated trust account. This isn't the seller's account or the agent's personal account; it's a special, non-interest-bearing account created just for this purpose.
- Transaction Progresses: Your money sits safely in escrow while all the important stuff happens—home inspections, the appraisal, and securing your mortgage loan.
- Closing Day: When the deal successfully closes, the escrow agent applies your earnest money deposit directly toward your down payment or closing costs. You'll see this all laid out as a credit on your final settlement statement.
This process ensures your money is only used exactly as intended. It's also a crucial concept to grasp for more complex situations, like when you are buying and selling real estate using a trust.
Your earnest money deposit is held in trust, meaning it is legally protected and cannot be touched by the seller until the transaction is complete. This is the cornerstone of a secure and transparent real estate deal.
The Role of the Escrow Agent
The escrow agent or title company is way more than just a piggy bank. They are the transaction's administrator, and their main job is to follow the written instructions agreed upon by both the buyer and the seller in the purchase agreement.
Their key duties are pretty straightforward:
- Verifying Funds: They make sure your deposit is received and securely tucked away.
- Managing Paperwork: They hold onto critical documents, like the deed and title report, until it's time to exchange them.
- Following Instructions: They won't release a dime until all contract contingencies have been met or waived by the appropriate party.
- Overseeing Closing: They facilitate the grand finale—the final transfer of all funds and property ownership on closing day.
By having this neutral party manage these crucial steps, both you and the seller can move forward with confidence. You know the deal is being handled by a professional, impartial expert, which is what makes the earnest money deposit such a reliable and powerful tool for securing a property.
When You Can Get Your Earnest Money Back
This is the million-dollar question every home buyer asks: what happens if the deal falls through? Your earnest money deposit feels like a huge commitment, and the thought of losing it can be downright stressful. The good news is, your real estate purchase agreement isn't a trap; it's designed with built-in escape hatches.
Legally, we call these contingencies. Think of them as safety nets woven directly into your contract. They are specific conditions that absolutely must be met for the deal to move forward. If one of these conditions isn’t satisfied, you typically have the right to walk away from the purchase and—most importantly—get your earnest money back in full.
These clauses are your best friend during a transaction. They give you the breathing room to do your due diligence without risking your deposit if you uncover a major problem with the property or your ability to buy it.
Your Contractual Safety Nets
Contingencies create a specific timeframe for you to investigate different aspects of the purchase. If something goes wrong within that window, you can legally terminate the agreement. While contracts can be customized, there are three main contingencies that protect the vast majority of buyers.
Here’s how these common safety nets play out in the real world:
- The Home Inspection Contingency: This gives you a set number of days to have the property professionally inspected. If the inspection uncovers significant issues—like a cracked foundation, faulty wiring, or a leaky roof—you can ask the seller to make repairs, negotiate a lower price, or just cancel the contract and get your deposit back.
- The Financing Contingency (or Mortgage Contingency): This one protects you if you can't secure a home loan. Even if you’re pre-approved, final loan approval is never a guarantee. This clause gives you time to finalize your mortgage; if your lender denies the loan for any reason, you can back out without penalty.
- The Appraisal Contingency: Lenders will only loan you money based on the home’s professionally appraised value. If the home appraises for less than your agreed-upon purchase price, this contingency lets you renegotiate with the seller or walk away from the deal and reclaim your deposit.
These clauses transform your earnest money from a risky bet into a secure, good-faith gesture.
A well-written purchase agreement with clear contingencies is the single most important tool for protecting your earnest money deposit. It outlines the exact rules of the game, ensuring your funds are safe if legitimate issues arise.
Understanding these protections is key. Just remember that each contingency has a strict deadline, so staying on top of your timeline is absolutely critical.
How You Could Forfeit Your Deposit
While contingencies offer solid protection, it’s just as important to understand how you could lose your earnest money. Forfeiting your deposit almost always happens when you, the buyer, breach the contract without a valid, contingency-related reason. This is exactly why sellers see the deposit as a form of security.
Here are the most common ways a buyer might have to say goodbye to their deposit:
- Waiving Contingencies: In a hot market, some buyers waive contingencies to make their offer more attractive. This is a high-risk, high-reward strategy because it removes your legal safety nets. If you waive the inspection contingency and later find a major issue, you can't use it as a reason to back out.
- Getting Cold Feet: Real estate deals are emotional, but changing your mind for a personal reason not covered by a contingency (like finding another house you like better) won't fly. The seller is likely entitled to keep the deposit as compensation for taking their home off the market for you.
- Missing a Deadline: Real estate contracts are all about timelines. If you miss a key deadline—like failing to apply for your mortgage on time or not scheduling the inspection within the specified window—you could be found in breach of contract, putting your deposit in jeopardy.
There’s a reason you often see the phrase "time is of the essence" in real estate contracts; it legally emphasizes that meeting every deadline is a material part of the agreement. Ultimately, as long as you act in good faith and play by the rules laid out in your contract, your earnest money should be safe.
Navigating Earnest Money Disputes and Forfeiture
While most real estate deals close without a hitch, sometimes things just fall apart. When that happens, the big question becomes: who gets to keep the earnest money? It’s a situation that can quickly turn a hopeful process into a stressful one.
Fortunately, outright wars over the deposit are pretty rare. But knowing how they’re handled—and more importantly, how to avoid them in the first place—is the key to protecting your investment. The secret almost always lies in the fine print of your purchase agreement.
How Forfeiture Protects the Seller
From the seller's point of view, your earnest money deposit is a huge deal. Once they accept your offer, they pull their home off the market, potentially saying no to other great buyers. If you suddenly back out for a reason that isn't covered by a contingency, the seller loses precious time and marketing momentum.
This is where your deposit comes in. If you break the contract, the seller may be entitled to keep it. This isn't just a penalty; it’s legally known as liquidated damages.
Liquidated damages are a pre-agreed-upon sum meant to compensate the seller for their financial hit. It covers the time their property was tied up and the costs of having to relist it, offering a fair solution without dragging everyone to court.
This is exactly why sellers see your deposit as a serious sign of commitment. It’s their safety net, assuring them you won't just walk away without a legitimate, contractually-sound reason, forcing them back to square one.
The Dispute Resolution Process
If you and the seller can't agree on who should get the deposit, the escrow company can't just pick a side. They have to follow a specific process, which usually unfolds in a few stages.
- Negotiation: The first step is always to talk it out. Your agent and the seller's agent will try to find some middle ground. Often, a simple compromise, like splitting the deposit 50/50, is enough to resolve the issue and let everyone move on.
- Mediation: If talking doesn't work, a neutral third-party mediator might step in. The mediator’s job is to guide the conversation and help you and the seller find a solution, but they can't force anyone to agree.
- Legal Action: This is the last resort. If all else fails, one party might have to file a lawsuit. The case then goes to small claims court (or a higher court, depending on the amount), where a judge will make a final, binding decision based on the contract. It’s also the most expensive and time-consuming route.
Preventing Disputes Before They Start
Honestly, the best way to handle a dispute is to make sure it never happens. A well-written purchase agreement is your single best defense against misunderstandings and losing your deposit. When the contract is crystal clear, there’s no room for debate.
Here are the smartest moves you can make to protect yourself:
- Insist on Clear Contingencies: Make sure your inspection, financing, and appraisal contingencies are written in plain English with realistic deadlines.
- Document Everything: Keep a record of all your communications—emails, texts, and notes from phone calls. This paper trail is invaluable if a disagreement pops up later.
- Hit Every Deadline: In real estate, "time is of the essence" isn't just a saying; it's a contractual obligation. Missing a deadline can be seen as a breach of contract, which puts your deposit on the line.
- Don't Waive Contingencies Lightly: In a hot market, it can be tempting to drop protections to make your offer look better. Just understand that doing so dramatically increases your risk of forfeiture if something goes wrong.
By working closely with your real estate agent to craft a strong, unambiguous contract, you can move forward with confidence, knowing your earnest money is safe and sound.
Common Questions About Earnest Money
Even after you get the hang of what an earnest money deposit is, a few practical questions always seem to come up. Let's tackle some of the most common ones so you can move forward feeling confident in your home buying journey.
Is Earnest Money the Same as a Down Payment?
Not quite, but they're definitely related. Think of your earnest money as the initial good-faith gesture that gets the ball rolling. The down payment is the much larger chunk of money you'll bring to the table at closing.
The good news? Your earnest money isn't an extra fee tacked on at the end. When you close the deal, that deposit is credited right back to you, which means you'll need less cash for your down payment and closing costs.
What Happens to the Earnest Money at Closing?
On the big day, your earnest money shows up as a credit on your final settlement statement. The escrow or title company holding the funds will put that money toward your down payment or other fees, like title insurance or county recording charges.
Essentially, it comes right back to you by lowering the final check you need to write to seal the deal.
Your earnest money deposit is almost always credited toward your down payment or closing costs, reducing the amount of cash you need to bring on closing day.
Can I Lose My Deposit if My Loan Is Denied?
Typically, no—but only if you have a financing contingency in your purchase agreement. This clause is your safety net. It gives you a set amount of time to get your mortgage approved.
If your lender denies your loan application within that period and you follow the contract's rules for notifying the seller, you can walk away and get your full earnest money deposit back. Without that contingency, your deposit could be on the line. While we're focused on earnest money here, you can find answers to other frequently asked questions about real estate in this great resource.
Who Actually Holds the Earnest Money Deposit?
One thing is for sure: the seller never holds your deposit directly. To keep everything fair and secure, your funds are placed in a dedicated trust or escrow account managed by a neutral third party. This is usually:
- An escrow company
- A title company
- A real estate brokerage's trust account
This system protects your money completely. It guarantees the funds are only released once everyone has met their contractual obligations or when both you and the seller agree in writing.
Navigating the ins and outs of a real estate deal takes an expert guide. At Edinhart Realty and Property Management, we make sure our clients understand every single step, from writing the offer to getting the keys at closing. If you're looking to buy, sell, or manage a property in the Fresno area, contact us today to see how our professional team can help you achieve your real estate goals.


