

You're looking at an application that looks clean on paper. The credit is fine, the references are pleasant, and the pay stub seems to say the applicant can handle the rent. Then one small thing nags at you, the deposit pattern looks too neat, the dates feel slightly off, or the story in the documents doesn't quite line up with what the applicant said on the phone.
That's the moment where tenant income verification either protects the property or lets a problem walk through the door. In California's Central Valley, where I've reviewed hundreds of files, the applicants who cause the most trouble usually don't fail the first glance. They fail the cross-checks. The difference between a safe approval and a bad one is rarely gut instinct, it's a repeatable workflow that checks income from more than one angle and treats inconsistencies as signals, not nuisances.
Why Income Verification Is Your First Line of Defense
A polished application can hide a weak one. I've seen files where everything seemed right until the income docs were laid side by side, then the cracks showed up fast, a pay stub that didn't match the bank deposits, an employer line that couldn't be independently confirmed, or income that looked strong only because one document was doing all the work.
That's why income screening belongs at the front of the process, not as an afterthought after you've already liked the applicant. A bad approval doesn't just create a late payment headache, it can force the owner into a long cleanup cycle of missed rent, turnover work, and re-listing time. A disciplined process protects both sides, because a qualified applicant also benefits from a clear standard instead of arbitrary decisions.
The real value is consistency
The strongest screening files are the ones where every decision can be traced back to the same written rule. That usually starts with a published income standard, then a document package that supports it from multiple directions, and finally a verification note showing what matched and what didn't.
Practical rule: never let one clean-looking pay stub overrule the rest of the file.
For landlords who want a checklist-style system, an internal screening checklist like the one in this tenant screening checklist helps keep the process uniform. Uniformity matters because it's easier to defend, easier to train on, and harder for fraud to slip through.
The core habit is simple. Confirm the income exists, confirm it's stable, and confirm it's enough for the rent under the same standard you use for everyone else. If one piece doesn't fit, pause. If two or three pieces don't fit, the file usually needs a deeper review, not a quicker approval.
Calculating Rent-to-Income Ratios and Setting Standards
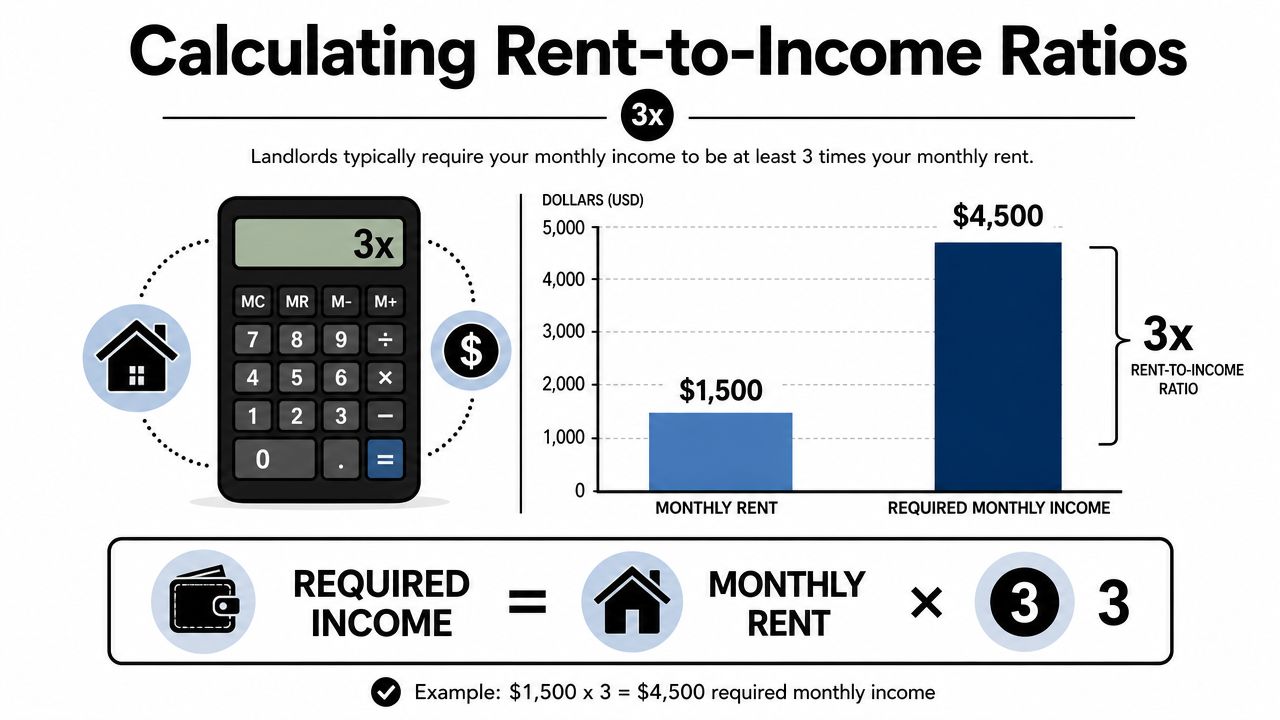
The cleanest way to start is with a written ratio before any application lands on your desk. The common benchmark in rental screening is gross monthly income of at least 3x monthly rent, so a tenant paying $1,500/month would need about $4,500/month in gross income, and industry guidance notes that some markets adjust that to about 2.5:1 in higher-cost areas or 4:1 for luxury rentals, while 3:1 remains the standard reference point in many markets. That benchmark is useful because it converts a messy income review into a simple affordability test, and it can be applied consistently across a large applicant pool. Tenant employment and income guidance
Publish the standard before you screen
Put the rule in writing before you review files. Applicants can self-screen when they know the standard up front, and that saves time for everyone involved.
For a typical W-2 employee, the practical evidence set is 2 to 3 recent pay stubs plus 2 months of bank statements that show matching payroll deposits. For self-employed applicants, the stronger package is the prior-year tax return with schedules plus 3 months of business and personal bank statements. The rent ratio itself should be applied to the verified gross monthly income, not to what someone says they make verbally. Practical rental screening workflow
Use the same rule for every applicant
The point isn't to make the ratio perfect for every household. The point is to make it predictable. If a household combines income, the math should still be documented the same way. If a co-signer is part of the file, the support should be clear in writing, not implied. If the applicant uses a voucher or other assistance, apply the standard to the tenant-paid portion of rent, because consistency around source of income matters.
One simple habit helps a lot. Write the standard, state the required documents by income type, and note how you treat variable income, household income, and subsidy income. That one page becomes the backbone of your screening policy.
Required Documents and What Each One Reveals
A good file isn't just a stack of documents. It's a set of documents that answer different questions. A pay stub shows current earnings, but it can be fabricated. A W-2 confirms annual wages, but it lags behind current reality. A bank statement shows actual cash flow, but it doesn't explain every deposit by itself. The power comes from pairing them.
Practical rule: one document proves very little, two documents prove more, and three documents that agree usually tell you the truth.
The table below is the way I think about each document type when I'm reviewing a file.
| Document Type | What It Confirms | Key Limitation | Best Paired With |
|---|---|---|---|
| Pay stubs | Current pay, pay cycle, and year-to-date totals | Can be altered | Bank statements and employer verification |
| W-2 forms | Annual wage history | Doesn't prove current pay | Recent pay stubs |
| Tax returns | Reported income history, especially for self-employed applicants | Requires interpretation | Bank statements and business records |
| Bank statements | Actual deposits and cash flow | Doesn't identify every income source on its own | Pay stubs, tax returns, or benefit letters |
| Employment verification letters | Current job status and compensation claims | Depends on employer responsiveness | Independent employer confirmation |
| Benefit letters | Fixed-income sources such as retirement or disability | Confirms benefit amount, not spending habits | Bank statements |
Match the documents to the applicant type
For W-2 employees, two to three recent pay stubs plus bank statements is usually the starting point, because the pay stub shows the claim and the bank statement shows whether the money landed. For self-employed applicants, tax returns are more valuable than a polished profit-and-loss sheet alone, because the tax return is anchored in prior reporting and can be compared against deposits. For retirees or applicants with fixed income, benefit letters and bank statements often tell the story faster than employment-style forms.
The important part is cross-referencing. If the pay cycle on the stub says one thing and the bank deposits look like another, that gap deserves attention. If the pay stub claims a net amount that never shows up in the account, that's not a small inconsistency, it's a warning sign.
For a separate credit review step, this credit-check guide fits well alongside income verification, because payment behavior and payment capacity are related but not the same thing.
Spotting Fraud and Document Tampering
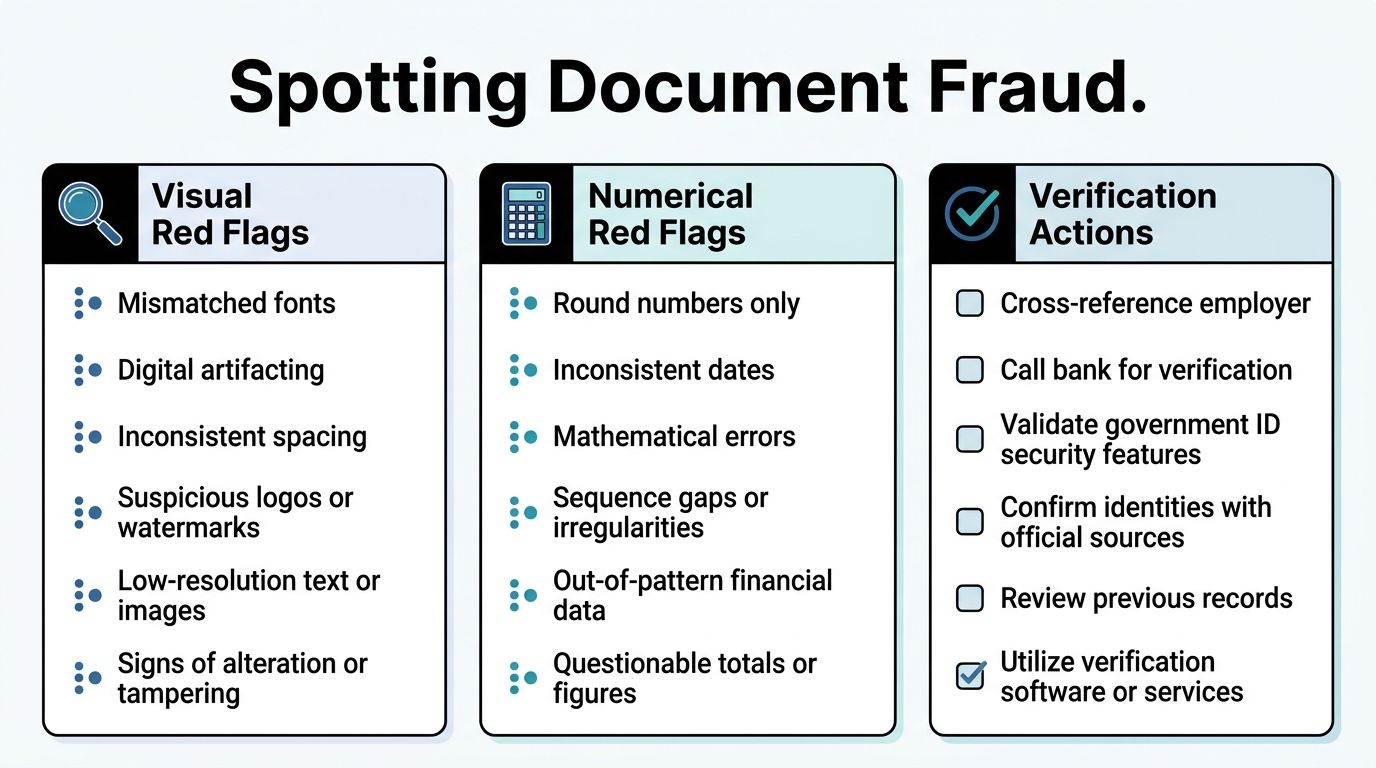
The biggest mistake I see is trusting the document because it looks clean. Fraudulent income files are often tidy, not sloppy. A fake pay stub can look better than a real one, and a fabricated employment letter can sound more official than an actual manager on the phone.
What jumps out first
The visual clues are usually the fastest to catch. Mismatched fonts, blurred or misaligned text, inconsistent dates, and missing year-to-date totals deserve a hard pause. The numeric clues matter just as much. Round-number deposits in bank statements, especially repeated round amounts that don't fit a normal payroll pattern, are worth checking against the claimed pay cycle. Best-practice reviews also flag net pay that repeats exactly when hours or schedules should vary. Tenant income verification best practices
Don't rely on contact info the applicant gives you
A common failure mode is calling the number on the employment letter or the phone number attached to the pay stub. That's too easy to game. Use an independently sourced employer number, ideally from the company's public website or another source outside the application packet, then document who you called and what was confirmed.
The same logic applies to bank deposits. If the stub says one thing and the statement says another, the file needs clarification before approval. I'd rather lose a good applicant than approve a fake one, because the fake one costs more to unwind.
A five-minute fraud check
- Check the header fields: Make sure the employer name, pay period, and employee name line up across documents.
- Read the totals: Confirm that year-to-date numbers are mathematically consistent with the listed pay periods.
- Scan for formatting drift: Fonts, spacing, and alignment should stay consistent within the same document.
- Compare deposits: Bank deposits should fit the pay schedule, not appear as unexplained round figures.
- Verify the source: Call an independently found employer contact, not a contact supplied in the file.
For a practical demonstration, the embedded video below is worth watching if your team trains new screeners and needs a fast visual reference.
Verifying Self-Employed and Gig Economy Applicants
Self-employed applicants aren't automatically risky, they're just different. The mistake is trying to screen them like salaried workers. A contractor, rideshare driver, or freelancer can have good income and still fail a W-2-style review if you don't adjust your verification method.
Start with the annual baseline
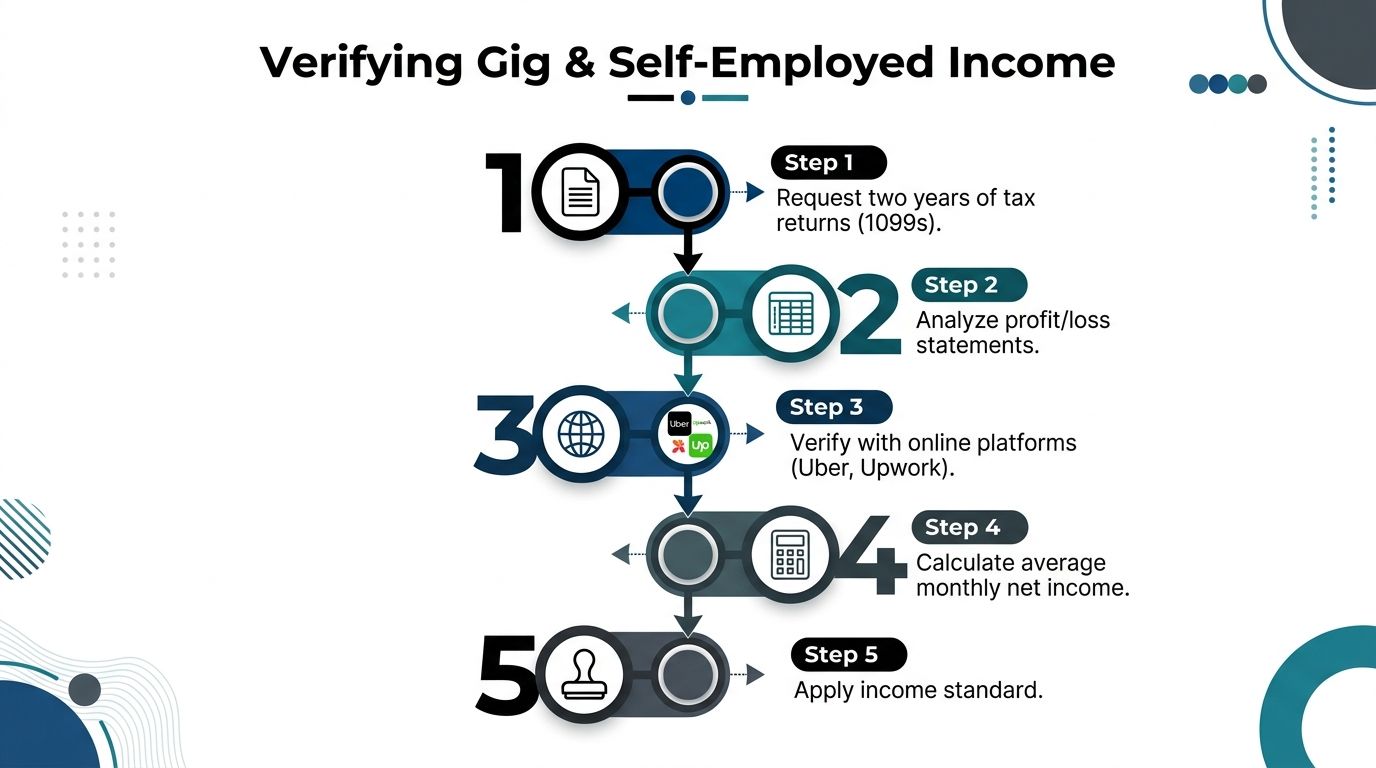
The strongest anchor is the last two years of tax returns for self-employed applicants, along with schedules where available. That gives you the reported income history before you try to interpret current deposits. Once that baseline is in hand, three to six months of business and personal bank statements can show whether the recent cash flow supports the rental ask. Tenant screening and income workflow
Treat variable income as an average, not a peak
Variable income can look strong in a good month and weak in a bad one. For irregular earners, a conservative average over 12 to 24 months is the cleaner way to estimate monthly capacity, because it smooths out volatility and avoids approval decisions based on a lucky stretch. That approach is especially useful for gig workers whose deposits may bounce around from week to week.
Gig-platform earnings, freelance invoices, and P&L statements can help, but they shouldn't stand alone. I want to see how the money lands in the account, not just how it was invoiced. If the platform earnings look high but the bank deposits don't support them, the file needs a slower review.
A practical workflow for non-traditional income
- Request tax returns first: Use them to establish the reported annual picture.
- Review deposits second: Look for consistency between claimed income and actual bank activity.
- Check supporting records: Invoices, business documents, or platform earnings reports can fill the gap.
- Average the income: Don't overvalue a peak month when the trailing pattern is weaker.
- Set the same cutoff: Apply your written income standard to the verified average, not the hopeful projection.
The goal isn't to exclude self-employed applicants. It's to verify them with the right documents so the decision is fair, defensible, and grounded in cash flow rather than optimism.
Legal Compliance and Fair Housing Considerations
Income verification has to be consistent or it can create legal exposure. The cleanest screening process is the one that treats every applicant under the same written standard, because that makes your decision easier to document and easier to defend. That consistency matters under federal Fair Housing rules, and it matters even more in California, where source-of-income issues need careful handling.
Keep the standard objective and documented
A written policy should say what income ratio you use, which documents you accept, and how you treat variable income, benefits, and subsidy payments. If you deny an applicant for falling below that standard, the file should show the calculation and the documents that supported it. If you issue an adverse decision tied to a consumer report, the file should also be handled with the proper notice process.
For a practical California reference, avoid fair housing violations is a useful guide for thinking about consistency and protected-class risk. For state-specific rental law context, California landlord-tenant law guidance is worth keeping on hand when you're updating screening procedures.
California-specific habits that protect you
In California, don't ask for more documentation than your policy requires just because an applicant's income source feels unfamiliar. That's where inconsistency creeps in. Keep your requests tied to the same income type, the same standard, and the same decision path for every file.
Privacy matters too. Income documents contain sensitive data, so your team should limit access, store them securely, and avoid casual forwarding or printing beyond what's necessary. When you're screening Central Valley applicants, the safest files are the ones with a clean paper trail and a narrow internal audience.
A compliance checklist that actually helps
- Apply one written income standard to every applicant.
- Request the same document set for the same income type.
- Record the reason for approval or denial in the file.
- Use independent verification contacts when calling employers.
- Store financial documents securely and restrict internal access.
- Handle subsidy income consistently with your written policy.
- Issue proper notices when a decision depends on a consumer report.
That's the standard I'd want in place before leasing a single unit, and it's the standard that scales when your portfolio grows.
Communication Scripts and Internal Workflows
A good screening file starts with a clear request. Applicants shouldn't have to guess what to send, and staff shouldn't have to improvise every time a file comes in incomplete. The best teams use the same message, the same order, and the same handoff every time.
A simple applicant request
“Please upload your most recent pay stubs, the matching bank statements, and any other income documents that apply to your household. If you're self-employed, include your tax return and recent bank statements. We review income documents only after all items are received, so sending the full set at once helps us move faster.”
That wording works because it's direct, specific, and not argumentative. If the applicant pushes back, the answer should stay calm and factual. “We use the same document request for every applicant with the same income type.”
Employer call notes that keep you focused
“Hi, I'm verifying employment for a rental application. Can you confirm whether the applicant is currently employed there, the job title, and whether the pay schedule matches the documents we received?”
Keep the call short. Log the date, the name of the person who answered, and exactly what they confirmed. If the number came from the applicant's paperwork, stop and find an independent number before you rely on the answer.
A workable internal workflow
- Receive the application. Confirm the income type before asking for documents.
- Send the standard request. Ask for the exact document set your policy requires.
- Review for consistency. Compare dates, totals, deposits, and pay cycles.
- Verify outside the packet. Use an independent employer or source contact.
- Document the result. Record the verified income figure and the decision.
- Escalate anomalies. Ask for clarification or decline when the file doesn't reconcile.
Teams that want a structured process can run this through their property management workflow, whether that's a full-service portfolio or a placement-only screening file. In practice, that kind of consistency is what keeps the phone quiet later, because the bad files never make it through the front door.
If you want a screening process that's strict, documented, and practical for Central Valley rentals, contact Edinhart Realty and Property Management to review your tenant income verification workflow and tighten the way your applications are screened.


