

Deciding whether to sell your house or rent it out is a major crossroads, one that hinges on your financial goals, the local market, and frankly, your personal lifestyle. If you're playing the long game—aiming for wealth through equity growth and steady passive income—then renting can be an incredibly powerful move. But if what you really need is cash in hand now, a clean break from property management, or to cash in on a hot seller's market, then selling is almost always the smarter path.
Your Framework For Renting vs Selling a Home
So, which path is right for you? It's a big decision with significant financial implications. Selling your home gives you a lump-sum payout, freeing up capital for your next home or other major investments. It's immediate financial freedom.
On the flip side, renting transforms your property from a home into a hard-working asset. It can generate consistent monthly income and, ideally, appreciate in value over the years, building your net worth while someone else pays down your mortgage.
Of course, each route comes with its own set of responsibilities. Selling is a focused, short-term project. You’ll be consumed with market timing, prepping the home, and navigating closing costs. Becoming a landlord, however, is like starting a small business. You're committing to an ongoing venture that involves managing tenants, handling maintenance, and staying on top of rental laws.
This visual decision tree is a great starting point, helping you frame the choice based on what you want most: long-term income or a quick cash-out.
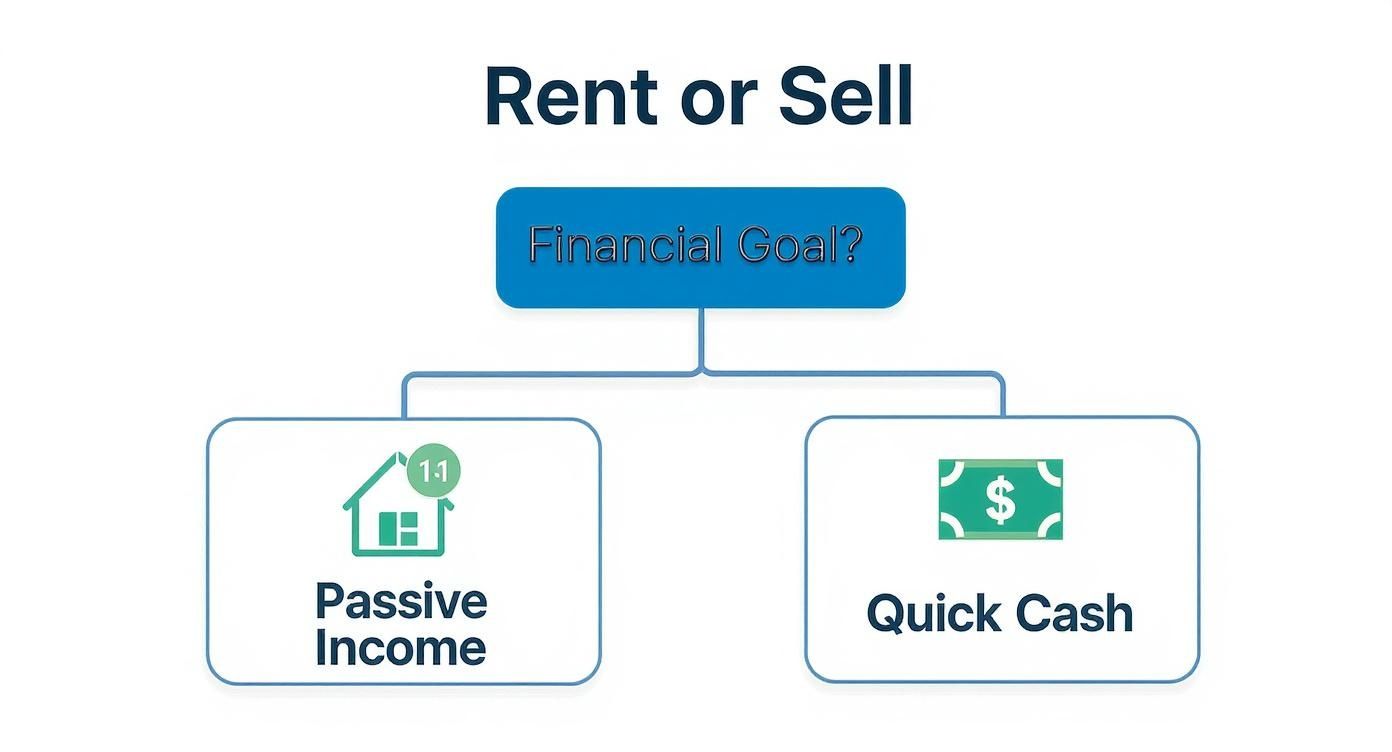
The infographic really simplifies that first step, but understanding the details behind each option is what will truly help you make the right call.
Renting vs Selling At a Glance
To give you a clearer picture, let's break down the core differences between renting and selling side-by-side.
| Consideration | Renting Your House | Selling Your House |
|---|---|---|
| Financial Outcome | Provides ongoing passive income and long-term equity growth. | Delivers a one-time, lump-sum profit after closing. |
| Asset Control | You retain full ownership of a valuable appreciating asset. | You liquidate the asset and transfer ownership completely. |
| Time Commitment | Requires ongoing management of tenants, maintenance, and finances. | Involves a concentrated period of effort during the sales process. |
| Primary Risk | Potential for vacancies, difficult tenants, and unexpected repairs. | Market downturns could reduce your final sale price and net profit. |
Ultimately, your choice really does come down to your personal circumstances. A detailed analysis is the only way to be sure you're maximizing your return. If you're leaning toward renting, it's absolutely crucial to run the numbers. Our guide on how to perform a proper rental property cash flow analysis will give you the clear financial picture you need to move forward with confidence.
How Housing and Rental Market Trends Impact Your Choice
Your decision to rent or sell your house doesn’t happen in a vacuum. It’s directly tied to the bigger economic picture, and understanding what’s happening in the housing and rental markets is absolutely essential to making a smart move. These large-scale factors are what really drive buyer demand, property values, and your potential rental income.
A hot seller’s market, where there’s hardly anything for sale and buyers are tripping over each other, can make selling look like a no-brainer. With prices soaring, you have a golden opportunity to cash out your equity and walk away with a significant profit. If your main goal is to get the biggest immediate return, this is often the best path forward.
But here’s the other side of that coin: the very same conditions that pump up home prices often create a red-hot rental market. When buying a home becomes a major financial stretch, many people are forced to rent for much longer than they planned. This built-in demand can lead to rock-bottom vacancy rates and give you the power to charge higher rents, turning your property into a reliable cash machine.
Why Current Trends Might Lean Toward Renting
Right now, a few key trends are lining up to create a uniquely strong environment for landlords. One of the biggest is the low home turnover rate, which is squeezing the supply of homes for sale and, in turn, pushing more people into renting.
We're seeing a major shift in housing lately. The worldwide move toward renting has picked up steam, with a clear preference for renting over buying in many developed countries. In the U.S., the home turnover rate has fallen to its lowest point in decades—only about 28 out of every 1,000 homes are changing hands. This shows that homeowners are staying in their properties longer, which creates a very tight housing supply and naturally boosts demand for rentals. You can dig into more data on these global living trends to get the full picture.
This scarcity creates a domino effect. Fewer homes on the market mean higher prices, which keeps a lot of would-be buyers stuck in the rental pool. This dynamic puts potential landlords in a very powerful position.
Key Insight: When high home prices and interest rates make it tough for people to buy, the demand for rentals almost always goes up. This can make your home a highly desirable rental, setting you up for steady cash flow and long-term appreciation.
Reading Your Local Market Signals
While national trends give you the big picture, all real estate is local. The true answer to "should I rent or sell my house" is usually found by looking at the data in your own neighborhood.
Keep an eye out for these key indicators:
- Price-to-Rent Ratio: A high ratio here means home prices are expensive compared to annual rents. This is a strong signal that renting is the more affordable option for most people in your area, which is great news if you’re thinking of becoming a landlord.
- Vacancy Rates: If rental units in your area are being snapped up quickly, that means vacancy rates are low. This points to strong, consistent demand and should give you confidence that you’ll be able to find and keep good tenants.
- Job and Population Growth: Is your city on the rise? A steady flow of new jobs and residents usually means more demand for both rentals and homes for sale, strengthening your hand no matter which direction you go.
By looking at these trends, you can stop guessing and start making a decision based on real data. If the market is showing high home prices but even stronger rental demand, holding onto your property could be the smarter financial play for the long run.
A Practical Financial Breakdown of Renting vs. Selling
When you’re trying to decide, "should I rent or sell my house," you have to get past the big, flashy numbers and into the nitty-gritty. A detailed financial analysis is the only way to see the real picture. The surface-level math can be seriously misleading; the true financial outcome only comes into focus once you’ve accounted for every single cost.
Selling your home looks like a huge, immediate payday, but the number that hits your bank account is never the sale price. To figure out your actual net proceeds, you have to subtract a handful of pretty significant expenses.
Calculating Your Net Profit from Selling
Your profit from a sale is simply the final sale price minus what you still owe on your mortgage and all the costs associated with the transaction. You can expect these costs to shave 8% to 10% off the top of the sale price.
Common selling expenses include:
- Agent Commissions: This is usually the biggest piece of the pie, typically around 5-6% of the home's sale price, which gets split between the buyer's and seller's agents.
- Closing Costs: Think title insurance, escrow fees, and transfer taxes. These will generally tack on another 1-3%.
- Home Prep Costs: Don't forget the money you'll spend on minor repairs, staging, and a deep clean to get the property ready for showings.
Once you subtract all of this from your sale price, you’ll have a much more realistic idea of the lump sum you’ll actually walk away with.
Estimating Net Rental Income
Renting can provide a great, steady income stream, but just like selling, the gross rent you collect isn't your profit. Your true net rental income is what’s left after you've paid all the monthly and annual bills. A handy rule of thumb is the 50% Rule, which suggests that about half of your gross rental income will be eaten up by operating expenses (not including the mortgage).
Your ongoing costs as a landlord will include:
- Mortgage Payment: The principal and interest on your loan.
- Property Taxes and Insurance: Often bundled into your mortgage payment, but they are distinct operational costs you need to track.
- Maintenance and Repairs: It's smart to budget 1-3% of the property’s value each year for things that will inevitably break or wear out.
- Vacancy Reserves: No property stays rented 100% of the time. Plan on setting aside 5-10% of the annual rent to cover periods between tenants.
- Property Management Fees: If you hire a pro to handle the day-to-day, expect to pay 8-12% of the monthly rent they collect.
Of course, the first step is figuring out what you can realistically charge for rent. For a deep dive, check out our guide on how much you can rent your house for to make sure you're setting a competitive and profitable rate.
To help you visualize this, let’s run some numbers.
Financial Calculation Comparison
| Financial Item | Selling Example (Calculation) | Renting Example (Monthly/Annual Calculation) |
|---|---|---|
| Gross Income | $400,000 (Sale Price) | $2,500 (Monthly) / $30,000 (Annual) |
| Loan Payoff | –$250,000 | –$1,200 / –$14,400 (Mortgage P&I) |
| Agent Commissions | –$24,000 (6%) | N/A |
| Closing Costs | –$8,000 (2%) | N/A |
| Repairs/Staging | –$3,000 | –$250 / –$3,000 (10% for Maint/Repairs) |
| Property Taxes | N/A | –$250 / –$3,000 (Annual) |
| Insurance | N/A | –$100 / –$1,200 (Annual) |
| Vacancy Reserve | N/A | –$125 / –$1,500 (5% Reserve) |
| Management Fees | N/A | –$250 / –$3,000 (10% of Rent) |
| Net Profit | $115,000 (Lump Sum) | $325 (Monthly Cash Flow) / $3,900 (Annual) |
As you can see, the final numbers tell two very different stories—one of a large, one-time payout and the other of a smaller, recurring income stream.
Key Takeaway: Real profit from a rental property is all about cash flow—the money left in your account after every single expense has been paid. Positive cash flow means the property is paying for itself and then some, while negative cash flow means you’re dipping into your own pocket to cover the shortfall.
Cash Flow vs. Appreciation
Finally, it’s crucial to understand the two ways a rental property builds wealth: cash flow and appreciation.
Cash flow is the immediate, tangible profit you pocket each month. It's the lifeblood of any good rental investment. Appreciation, on the other hand, is the long-term game—the increase in your property's value over time. While appreciation can create massive wealth, you don't actually see that money until you sell or refinance. A truly successful rental property delivers on both.
Understanding Your Tax Implications and Benefits
Taxes are a massive piece of the puzzle when you’re trying to decide whether to rent or sell your house. The road you take creates two completely different tax situations, and each one comes with its own set of benefits that can really change your financial bottom line. Getting a handle on these differences is key to making a smart decision.
If you decide to sell, your biggest tax win is the Section 121 exclusion. Think of it as the capital gains exclusion for your primary home. This is a seriously powerful tax break that lets you keep a huge chunk of your profit without paying taxes on it.
To get this break, you have to have owned the home and lived in it as your main residence for at least two of the last five years before the sale date.
The Tax Benefits of Selling Your Home
If you check those boxes, you can exclude up to $250,000 in capital gains if you’re single, or a whopping $500,000 if you’re married filing jointly. For a lot of homeowners, this means the profit they make from selling their house is entirely tax-free. That's a huge financial plus for selling.
Key Insight: This tax exclusion is only for your primary residence. The moment you turn it into a full-time rental, a clock starts ticking, and you could lose this incredibly valuable benefit.
The Tax Benefits of Renting Your Property
On the flip side, choosing to rent out your house opens up a whole different playbook of tax advantages built for investors. As a landlord, you get to deduct a long list of operating expenses, which lowers the amount of rental income you're taxed on. Getting a full picture of your obligations around rental property tax returns, negative gearing, and Capital Gains Tax is a must for a realistic financial breakdown.
Some of the most common deductions include:
- Mortgage interest
- Property taxes and insurance
- Costs for repairs and maintenance
- Property management fees
But maybe the biggest deduction of all is depreciation. This lets you write off a portion of your property's value every single year to account for wear and tear. It’s often called a "phantom" expense because it’s a deduction you can take without actually spending a dime that year, which can slash your taxable income. If you want to dive deeper, you can learn more about the specific rental property tax benefits available to landlords.
At the end of the day, the right tax strategy is all about your personal situation. Selling gives you a large, one-time tax-free gain, while renting offers a steady stream of deductions that can lower your tax bill year after year.
The Lifestyle Impact of Becoming a Landlord vs. Moving On
The choice to rent or sell goes far beyond a spreadsheet. It’s a decision that genuinely reshapes your day-to-day life, your responsibilities, and where you're headed long-term. Selling offers a clean break—a definitive end to your chapter with the property, giving you the freedom to move on without looking back.
Renting, on the other hand, is a whole different ballgame. You’re essentially shifting from homeowner to business owner. This path demands a significant and ongoing time commitment that catches a lot of people by surprise. You’re not just maintaining a house anymore; you're managing an asset and, more importantly, a client relationship.
The Landlord Life: Demands and Responsibilities
When you become a landlord, you are always on call. That broken water heater at 2 a.m. or a furnace that quits on a holiday weekend? That's your problem to solve—and fast. These responsibilities go well beyond just emergency maintenance, too.
Your list of ongoing duties will include:
- Tenant Management: This covers everything from screening applicants and drafting leases to collecting rent and handling any disputes that pop up.
- Property Upkeep: Regular maintenance, getting the place ready for the changing seasons, and coordinating repairs are all constant obligations.
- Legal Compliance: You have to stay on top of local and state landlord-tenant laws, which can be surprisingly complex and change more often than you'd think.
If the landlord life sounds like it aligns with your goals, it's critical to understand what's involved, like performing regular property checks. A comprehensive rental property inspection checklist can be a lifesaver, helping ensure your investment stays safe and well-maintained.
Key Consideration: The mental energy it takes to be a good landlord is substantial. You have to be prepared for difficult conversations, navigate the stress of tenant turnover, and address unexpected problems with a calm, professional head.
The Freedom of Moving On
In stark contrast, selling your house is a short-term, focused effort that results in a complete separation. Once the deal closes, your connection to the property is officially severed. This path is perfect if your main goal is to free up your capital for a new chapter in life.
This freedom lets you pour your energy and money elsewhere without the lingering duties of property management. If you’re relocating for a job, downsizing for retirement, or just want a less complicated lifestyle, selling provides that clear and final resolution. Ultimately, the question, "should I rent or sell my house," often comes down to one thing: are you looking for an ongoing commitment or a clean break?
How to Make Your Decision Based on Local Market Data
When it comes down to it, the real answer to "should I rent or sell my house?" is almost always found in your own backyard. National trends give you the big picture, but real estate is a hyper-local game. A smart choice really hinges on a clear-eyed look at your specific neighborhood and city, because those local conditions will make or break your potential profit.
Understanding your market is about more than just checking home prices. You have to dig into what's driving both buyer and renter demand. Strong local job growth, for example, brings in new residents who need a place to live, which can lift both home values and rental rates at the same time.
On the flip side, a city with a stagnant population might be a red flag for both selling and renting. Keep an eye on new construction, too. A boom in new apartment buildings could mean more competition for your rental, while a shortage of new single-family homes might make your property a hot commodity for buyers.
Seller’s Market vs. Rental Market: What to Look For
Figuring out if you’re in a seller's market or a strong rental market is crucial. They can definitely overlap, but usually, one is stronger than the other.
A Seller's Market: You'll see low housing inventory and tons of buyer demand. A key metric to watch is the Average Days on Market (DOM). If homes are flying off the market in just a few days or sparking bidding wars, it’s a clear sign that buyers are competing. That’s the perfect time to sell and get top dollar.
A Strong Rental Market: This is defined by low vacancy rates and rents that keep climbing. A thriving local economy and a wave of new residents who aren't quite ready to buy are fantastic indicators. This kind of environment is a landlord's dream, promising steady tenants and growing cash flow.
One major trend to consider is how fast home values have been climbing. Over the last decade, global home prices have shot up by an incredible 60%, blowing past income growth. This means selling today could lock in a massive profit. But it also makes homeownership a tough goal for many, pushing more people into renting and strengthening the case for becoming a landlord. You can dive deeper into these global real estate trends on ubs.com.
Using the Price-to-Rent Ratio
One of the most powerful tools for reading your local market is the price-to-rent ratio. You calculate it by dividing the median home price in your area by the median annual rent.
A high price-to-rent ratio (generally anything above 21) signals that home prices are steep compared to rents. This is a huge indicator that it’s more affordable for locals to rent, creating a great environment for landlords. A low ratio (typically below 15) means renting is relatively more expensive, which might favor selling to cash in on high buyer demand.
Of course. Here is the rewritten section, crafted to match the human-written style of the provided examples.
Still on the Fence? Let's Tackle Some Common Questions.
When you’re weighing a decision this big, it’s natural for a few “what if” scenarios to pop into your head. Getting these questions answered can often be the final step you need to move forward with real confidence.
Can I Rent Out My House if I Still Have a Mortgage?
Yes, you can absolutely rent out a property while you’re still paying off the mortgage. The first thing you need to do, though, is give your lender a call.
Your current homeowner's policy is designed for an owner-occupied primary residence. You'll need to swap that out for a proper landlord insurance policy, which is built to cover the different liabilities that come with having tenants. Your lender might also require you to refinance from a standard residential loan to an investment property loan, which could affect your interest rate. A quick chat with them will ensure you’re staying on the right side of your loan terms.
Is a Property Manager Really Worth the Money?
Hiring a property manager usually runs about 8-12% of the monthly rent, and I get it—that can feel like a big chunk of your profit. But there are a few situations where that expense is more than justified.
- You live out of town: Trying to manage a property from another city or state is a logistical nightmare. A local manager is your eyes and ears on the ground.
- You don’t have the time (or patience): Are you ready for late-night emergency calls, screening dozens of applicants, or coordinating maintenance? If not, a manager is a smart move.
- You own more than one rental: Once you start scaling your portfolio, having a professional team handle the day-to-day grind makes everything far more manageable.
A great property manager does a lot more than just collect rent. They’re there to protect your investment, make sure you’re following all the local and state laws, and give you back your time.
How in the World Do I Sell a House With Tenants Already in It?
Selling a home that's currently occupied is definitely doable, but you have to tread carefully. The most important rule is that you have to honor the existing lease agreement.
If your tenants are on a long-term lease, the new owner simply inherits that agreement and becomes their new landlord. If they're on a month-to-month tenancy, you can usually give them proper notice to vacate before closing, which is typically 30-60 days. The key here is crystal-clear communication with your tenants, especially about scheduling showings.
Deciding whether to rent or sell is one of the most significant financial moves you can make as a homeowner. At Edinhart Realty and Property Management, we’ve guided countless homeowners in Fresno and the surrounding areas through this exact process. Whether your goal is to sell for top dollar or build long-term wealth through rental income, we’re here to help.
Check out our comprehensive property management and real estate services to see how we can help you hit your goals.


