

The secret to selling your home during a divorce without losing your mind—or your money—is to get everything in writing before that "For Sale" sign ever hits the lawn. You need a clear, legal game plan. This initial agreement on who does what, who decides what, and how the money gets split is your roadmap. It's what will keep things from going off the rails when emotions are running high.
Your First Move When Selling a Home in a Divorce
Deciding to sell your home is one of the biggest financial moves you'll make during a divorce. Getting it right from the start saves you from a world of future headaches and protects the equity you've both built. This isn't just another house sale; it's a business transaction happening under intense emotional pressure, which makes the planning stage absolutely non-negotiable.
Laying the Legal and Financial Groundwork
Before you even think about calling a real estate agent, you and your spouse need to have some frank conversations about the property. This is the moment you shift from thinking about it as a shared home to a shared financial asset.
First things first, you need to know exactly where you stand legally. The property title is a huge piece of this puzzle. How you legally own the home—as joint tenants with right of survivorship or tenants in common—directly dictates how the property is handled and how the proceeds are divided. Figuring this out isn't optional; it's the starting line.
With divorce so common, property sales are a frequent and often urgent part of the process. This is especially true in the United States, where homeownership rates among married couples are high.
Creating a Co-Selling Agreement
Once you’ve got the legal and financial picture, it’s time to draft a co-selling agreement. This is a written document, usually put together with your attorneys, that spells out the rules for the entire sale. Think of it as the business plan for selling your house.
This agreement needs to be specific. It should cover:
- Who Talks to Whom: How will you, your spouse, and your agent communicate? A group email thread? Will the agent speak to each of you separately? Nail this down.
- Decision Power: Who gets the final say on the list price, accepting an offer, or paying for repairs? This almost always requires mutual consent.
- Paying the Bills: Who’s covering the mortgage, utilities, insurance, and repairs while the house is on the market?
- Getting Paid Back: If one person fronts the cash for staging or pre-sale repairs, how and when will they be reimbursed? Get it in writing.
A solid co-selling agreement is the single best tool you have to prevent fights. It moves the conversation from emotional reactions to pre-approved business decisions, keeping the sale on track.
Before you jump in, you need a clear-eyed assessment of your finances, your emotional state, and a realistic timeline.
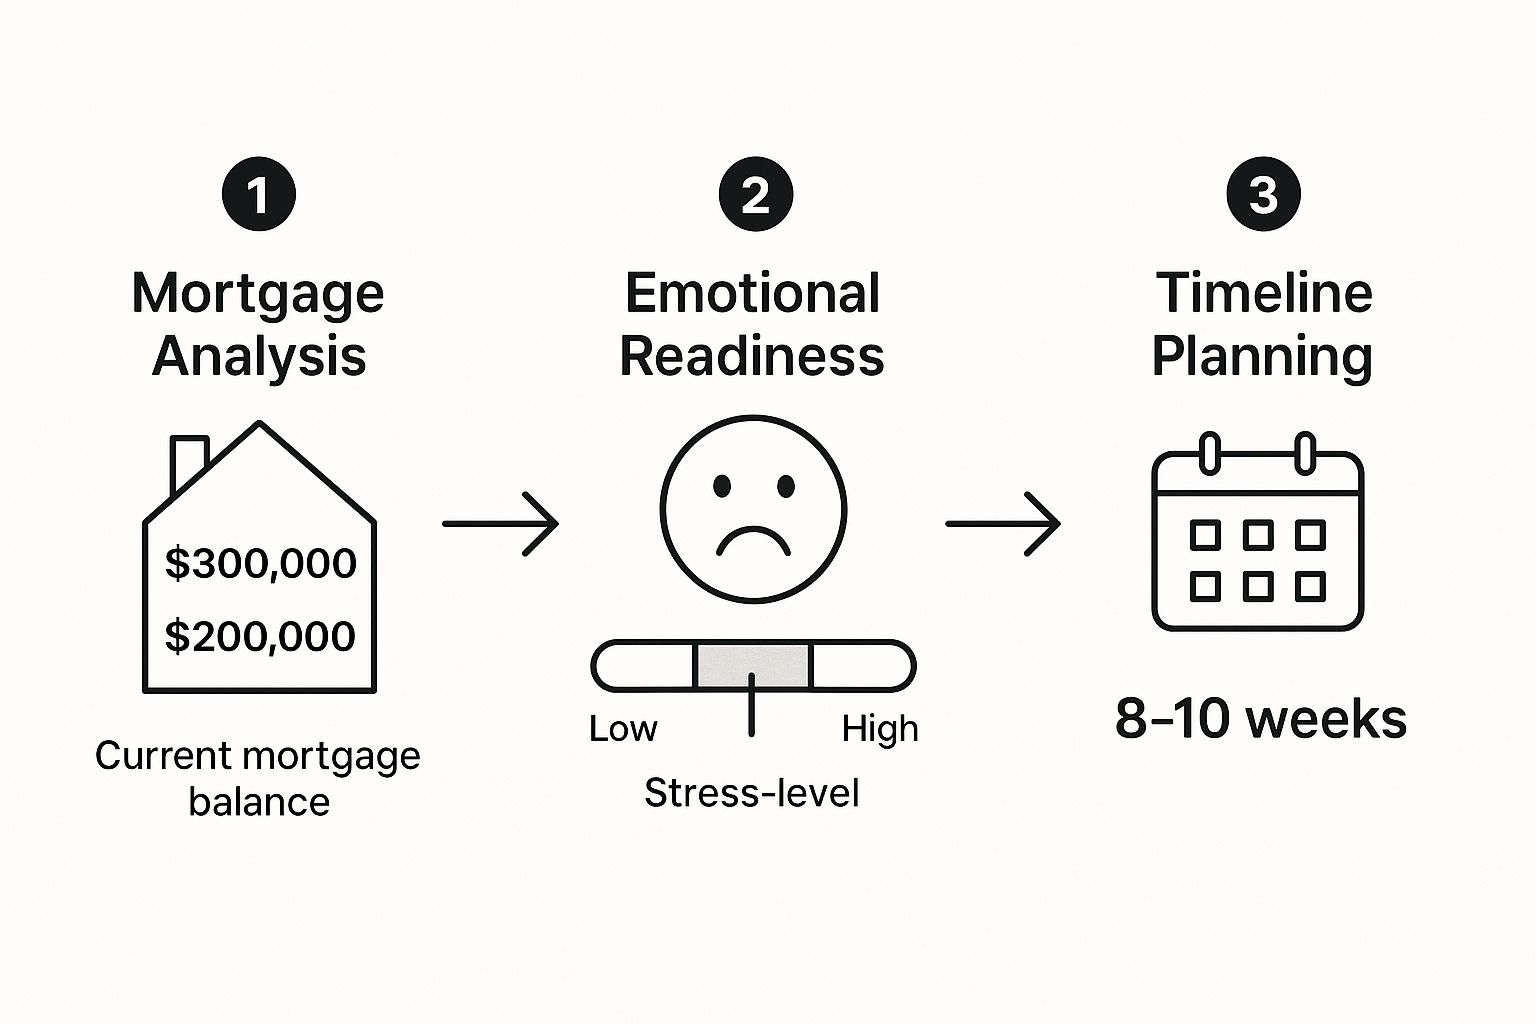
The process starts with understanding the numbers—your equity, your stress levels, and your timeline. A successful sale depends on it.
To help you organize these crucial first conversations, we've put together a simple framework. Think of this as your pre-listing checklist to ensure you and your spouse are aligned on the most important points before involving an agent.
Initial Decision Framework for Your Marital Home
| Key Decision Point | Why It Matters for Your Divorce | Actionable First Step |
|---|---|---|
| Property Title Status | Determines legal rights for the sale and how proceeds can be split. | Locate your property deed to confirm if you're "joint tenants" or "tenants in common." |
| Pre-Sale Budget | Prevents disputes over who pays for necessary repairs, staging, or maintenance. | Agree on a budget for pre-sale expenses and create a shared document to track all spending. |
| Communication Plan | Avoids miscommunication and ensures all parties (including the agent) are on the same page. | Decide on a single method of communication (e.g., a dedicated group email) for all sale-related decisions. |
| Sale Timeline | Aligns expectations on how quickly you need to sell, which impacts pricing and negotiation strategy. | Discuss and agree on a target "go-live" date and a deadline for accepting an offer. |
| Profit Division | Clarifies exactly how the net proceeds will be divided after all costs are paid. | Consult with your respective attorneys to draft a clear, legally-binding clause for the division of funds. |
This table isn't just a to-do list; it's a tool to facilitate productive, business-like conversations. By methodically working through these points, you turn a potentially explosive process into a manageable one.
Getting a handle on the legal paperwork is also a must. For those in certain states, you can find helpful guides for navigating Arkansas divorce papers and forms online. Doing this homework ensures the home sale fits correctly within the larger legal requirements of your divorce. When you tackle these issues upfront, you're setting yourself up for a sale that’s smoother, more predictable, and ultimately, more profitable.
Building Your Divorce Real Estate Team
Selling your home during a divorce isn't just another real estate transaction. It’s a whole different ballgame. The financial stakes are massive, emotions are running high, and simple communication can feel like navigating a minefield.
That’s why putting together the right team of professionals isn't a "nice-to-have"—it's an absolute necessity. You need a crew that can shield your biggest shared asset and, just as importantly, your own sanity.
Forget about hiring your newly-licensed cousin or a friend in the business. This situation calls for specialists who get the unique pressures of a divorce sale. Think of them as a neutral buffer, turning a potentially explosive personal drama into a structured business deal. Their entire focus is on one thing: getting you the best possible financial outcome.
The Right Real Estate Agent
This is the most important hire you will make. Your average agent might be a pro at selling houses, but they're often completely unprepared for the high-conflict communication and legal complexities that come with a divorce. You need someone who is part project manager, part diplomat, and 100% focused on the business at hand.
When you're interviewing agents, dig deeper than their sales history. You need to look for specific experience.
- Proven Divorce Sale Experience: Don't be shy. Ask for real-world examples. How have they handled disagreements over pricing or repairs? What's their process for making sure both parties get the exact same information at the exact same time?
- Specialized Training: Look for credentials like Real Estate Collaboration Specialist – Divorce (RCS-D) or Certified Divorce Real Estate Expert (CDRE). This isn't just alphabet soup; it means they've invested in training specifically for the legal and financial angles of selling property during a divorce.
- A Solid Communication Plan: A great agent in this scenario acts as a single, unbiased point of contact. They must be committed to communicating every update to both of you simultaneously. This prevents one person from feeling manipulated or left in the dark.
A top-tier agent in a divorce sale doesn't pick sides. They manage the process, keep the conversation focused on the sale itself, and guide decisions based on what you've already agreed to.
The Real Estate Attorney
Here’s a common mix-up: many people assume their divorce lawyer handles the home sale. While your divorce attorney is focused on dissolving the marriage and the overall settlement agreement, it's the real estate attorney who manages the nitty-gritty of the property transaction.
Their job is separate but critical. They are the ones who will review the final purchase contract, check the property's title for any liens or issues, and prepare all the closing documents. This ensures the ownership transfer is legally sound and clean, which is vital when so much money is on the line.
The Neutral Appraiser
Even with a fantastic agent providing a market analysis, arguments over the home's value can stop a sale dead in its tracks. It's common for one spouse to have an inflated price in mind due to emotional attachment, while the other just wants to sell it fast and move on.
This is exactly where a neutral, licensed appraiser saves the day.
By agreeing to hire one professional appraiser, you get an unbiased, data-driven valuation of your home. This number becomes the official starting point for setting your list price, and you can even write it into your co-selling agreement. It’s a small investment upfront that can prevent a massive, expensive conflict down the road.
It also gives you a clear financial picture, helping you understand how closing costs and real estate agent commission rates will affect your final payout.
Setting the Right Price and Managing Negotiations
Pricing is where the first real battle of a divorce home sale usually gets fought. I’ve seen it time and again: one spouse just wants a fast, clean sale for whatever cash they can get, while the other is dead set on holding out for the highest possible price.
Finding a middle ground isn't just about compromising. It's about using hard data to take the emotion out of the equation and creating a solid negotiation strategy before an offer even hits the table.
This united front is absolutely critical. Buyers can smell desperation or disagreement from a mile away, and it almost always leads to lowball offers. When you and your ex are on the same page about price and process, you stay in control.
From Disagreement to Data-Driven Decisions
The best way to sidestep pricing arguments is to let the market do the talking. Instead of going with your gut or what you think the home is worth, you need to ground your decision in two key pieces of evidence.
Your real estate agent will kick things off with a Comparative Market Analysis (CMA). This is a detailed report that looks at recently sold properties in your area that are similar to yours in size, condition, and features. It gives you a realistic range of what buyers are actually paying right now.
But even a CMA can leave room for dispute. This is where a formal appraisal from a licensed, neutral appraiser becomes your best friend in a divorce sale. By agreeing to hire one appraiser together, you get a single, legally defensible valuation. This number isn't a suggestion; it’s a professional assessment of your home’s fair market value.
Agreeing upfront to set the list price at or very near the appraised value is one of the smartest moves you can make. It replaces emotional debates with a hard number, allowing you to move forward as a team.
Proactive Negotiation Planning
Once you’ve locked in a price, the next move is to plan for the negotiation process itself. A buyer’s first offer is rarely their best, so deciding how you’ll respond to different scenarios before they happen is a game-changer. This is where you create a pre-approved plan.
Create a Price Reduction Schedule
Markets can change, and sometimes a home just doesn't sell as fast as you'd hope. A price reduction schedule prevents future fights by clearly defining when and by how much you’ll adjust the price.
For example, your agreement could state:
- Initial List Price: $550,000 (based on the appraisal).
- After 21 Days: If no acceptable offers are received, the price will automatically drop by 2% to $539,000.
- After 45 Days: If it's still on the market, the price will be reduced by another 2% to about $528,000.
This structure means you’re reacting to market feedback with logic, not emotion. It also stops one spouse from holding the sale hostage by refusing a necessary price drop.
Set Offer Acceptance Parameters
Your co-selling agreement should also spell out the minimum terms you will both accept. This goes beyond just the final sale price.
- Minimum Net Proceeds: What's the absolute lowest amount you need to walk away with after paying the mortgage, commissions, and closing costs?
- Contingencies: Are you open to offers with financing or inspection contingencies?
- Closing Timeline: Do you need to close quickly, or is there room for flexibility?
Having these parameters carved in stone means that when an offer lands, your agent can simply see if it meets your pre-approved criteria. If it does, the decision to accept is already made.
Broader economic conditions can also play a major role in your sale. For instance, historical data shows that divorce rates tend to slow down during economic slumps, like the 2008 recession, because financial instability makes it tougher for couples to go their separate ways. As the economy bounces back, a surge in divorces can flood the market with properties. You can learn more about how economic shifts influence divorce trends and real estate. This context makes having a clear, data-backed strategy for pricing and negotiating even more crucial.
How to Prepare and Show the Home Without Conflict
Getting a house ready for the market is tough, even in the best of times. Throw a separation into the mix, and the tasks of decluttering, repairing, and staging can feel monumental. This is especially true if one of you still lives there.
To get through it, you need a playbook that treats this as a business transaction, not a personal matter. The secret is to stop seeing it as "our home" and start seeing it as "our shared asset." This mental shift is the first and most critical step. It creates a neutral playing field where decisions are based on what gets you the best price, not on emotional ties.
Creating a Neutral and Appealing Space
First up is the tough part: depersonalizing the home. Buyers can't picture themselves in a space when every surface is covered with your family photos and mementos. This isn't just for them; it's an emotional reset for you, helping you both start the process of letting go.
Before a single buyer walks through the door, you have to make the space feel inviting to as many people as possible. This means learning how to effectively declutter your home and create a feeling of spaciousness. The goal is simple: make every room look bigger, brighter, and more welcoming.
Sorting through years of shared belongings is an emotional minefield. To keep friction to a minimum, try tackling this job separately or bring in a neutral third party to mediate. For a more organized approach, our guide on how to conduct an estate sale has practical tips for sorting and selling items, which can easily be adapted for this situation.
Managing Repairs and Staging Costs
Once the clutter is gone, it's time to handle necessary repairs and think about staging. A pre-sale inspection is a smart move; it uncovers issues that could scare away buyers, giving you a chance to fix them first. Your agent is a great resource here—they can point you to high-impact, low-cost fixes that deliver the best return.
But who foots the bill? This should have been ironed out in your co-selling agreement. The most common arrangements are:
- Splitting costs 50/50: You each contribute an equal amount from your own funds.
- Reimbursement at closing: One person pays for everything upfront and gets paid back from the sale proceeds before profits are split.
- Using a joint account: You both deposit an agreed-upon amount into a shared account used only for sale-related expenses.
No matter which path you take, keep every single receipt. Meticulous records are your best defense against "he-said, she-said" arguments over money. It ensures the final accounting at closing is clean, accurate, and fair.
Building a Fair Showing Schedule
If one spouse is still living in the house, you need a showing schedule that works for the sale while respecting their privacy. This takes cooperation and a little empathy. The aim is to make the home as accessible as you can without making the resident feel like they’re in a fishbowl.
Here’s how to set up a plan that works for everyone:
- Define "Reasonable Notice": Agree on a minimum notice period for showings, like 24 hours. Make sure your real estate agent knows this rule.
- Set "Blackout" Times: Are there times when showings are completely off-limits? Think kids' online school or important work-from-home calls. Define these from the start.
- Establish an Exit Plan: The person living in the home needs to plan on being gone during all showings. If you have pets, it’s best to take them with you. This lets buyers look around and talk freely without feeling like they're intruding.
When one person refuses to cooperate, it can derail the whole sale. This is where your real estate agent's role as a neutral project manager becomes invaluable. They can enforce the rules you agreed on for showings and prep work, acting as a buffer to keep the focus where it belongs: on maximizing your home’s value.
Navigating Closing Day and Dividing The Money
You’ve made it. After all the negotiations, paperwork, and emotional stress, closing day is the finish line. This is where all the hard work pays off and your shared home finally turns back into cash, ready to be split according to your agreement.
Knowing exactly what to expect demystifies the whole thing. It helps you avoid any last-minute drama or confusion when you’re so close to being done. A smooth closing isn't an accident; it's the result of being prepared.
What Happens at The Closing Table
On closing day, you’ll find yourself sitting across from a neutral third party—usually a closing attorney or an officer from a title company. Their role is simple: to make sure the property legally changes hands. They don’t work for you or your ex-spouse. They work for the transaction itself, ensuring every detail follows state law and your purchase agreement.
You’ll be handed a stack of documents, but the one that matters most is the Closing Disclosure (CD). This five-page form breaks down every single cost and credit involved in the sale. Both you and your ex-spouse need to review it carefully before a single pen touches paper.
This is exactly why having your own lawyer is so crucial. They can spot issues you might miss. In some situations, holding the property in a trust can also change how closing works. If that’s your scenario, you can get a better handle on the specifics by reading our guide on buying and selling real estate using a trust.
The Critical Role of Your Divorce Decree
The single most important document in this entire process is your divorce decree or marital settlement agreement. This is the court-approved legal order that spells out exactly how the money from the home sale will be divided. Ambiguity is your worst enemy here.
A well-written agreement leaves nothing to chance. It serves as a clear instruction manual for the closing agent, who is legally bound to follow it to the letter.
Your settlement agreement is the ultimate authority. The closing agent cannot and will not deviate from it. If the agreement says proceeds are split 50/50 after costs, that is exactly what will happen.
With approximately 40-50% of U.S. marriages ending in divorce, real estate agents and closing attorneys see these situations all the time. In fact, this is one of the reasons the real estate market keeps moving, even in a slower economy—divorcing couples often have to sell.
From Gross Proceeds to Your Final Check
Don't make the mistake of thinking you just take the sale price and cut it in half. It’s not that simple. The closing agent has a specific process for calculating the net proceeds, which is the actual cash left over for you and your ex.
Here's how the money flows from the buyer's payment to your bank account:
- Gross Sale Price: This is the starting point—the final price the buyer paid.
- Mortgage Payoff: First, the remaining balance on your mortgage is paid off. The closing agent wires this money directly to your lender.
- Closing Costs: Next, all transaction fees get paid out. This bucket includes agent commissions, title insurance, transfer taxes, and attorney fees.
- Agreed-Upon Reimbursements: This is where your careful record-keeping comes in. If you fronted the money for repairs or staging, the closing agent will reimburse you from the proceeds before the final split is calculated.
Let's walk through a quick example:
- Sale Price: $500,000
- Remaining Mortgage: -$250,000
- Commissions & Closing Costs: -$35,000
- Reimbursement to Spouse A for Repairs: -$5,000
After all those deductions, the net proceeds left to divide are $210,000. If your decree calls for a straight 50/50 split, you each get a check for $105,000.
Think about that for a second. Without that clear reimbursement clause in your settlement, that $5,000 for repairs could have easily turned into a huge fight at the closing table. This level of clarity is what transforms a potentially messy event into a predictable, professional transaction.
Common Questions About Selling a Home During Divorce
Even when you think you have a solid plan, selling a home in the midst of a divorce is guaranteed to bring up a lot of "what-if" scenarios. It's a stressful time, no doubt. But walking into it with clear answers to the tough questions can make a world of difference, helping you manage the process calmly and effectively.
Let’s tackle some of the most pressing questions we hear from clients facing this challenge.
Can My Spouse Force Me to Sell the House?
This is a huge source of anxiety for many people. The short answer is no, one spouse generally can't force the sale of the home on their own. It takes a court order. If you and your spouse are at a complete impasse about what to do with the house, a judge will have to step in and make the call based on your state's laws and the unique facts of your case.
More often than not, courts will order a sale to make sure the marital assets are divided fairly. This is almost a given if neither of you has the financial ability to buy out the other person's share.
The threat of a court-ordered sale is a powerful motivator. I always tell my clients that reaching a mutual agreement is far better because it keeps you in control of your largest asset—not a judge who doesn't know you.
This is exactly why that co-selling agreement we talked about earlier is so critical. It gives you a clear roadmap to follow and helps you avoid the kind of deadlock that lands you in a courtroom.
What Happens If My Ex Refuses to Cooperate?
An uncooperative ex can bring a home sale to a screeching halt. I’ve seen it all—from rejecting perfectly good offers and blowing past deadlines to making it impossible for agents to even show the property.
Your first line of defense should be that pre-negotiated co-selling agreement. It needs to spell out everyone's responsibilities and, just as importantly, the consequences for not holding up their end of the deal. If a firm reminder of that agreement doesn’t work, it's time to escalate.
Your attorney can file a motion with the court to compel your ex-spouse to cooperate. A judge has the power to:
- Enforce the sale terms: The court can order the uncooperative party to sign necessary documents or allow showings.
- Appoint a special master: In really high-conflict situations, a judge might appoint a neutral third party to take complete control of the sale from start to finish.
- Award legal fees: The court could order your ex to pay for the legal fees you had to rack up just to force them to cooperate.
Who Pays for Everything While the House Is for Sale?
The mortgage, utilities, insurance, and upkeep don't magically stop just because you're getting divorced. Figuring out who pays these ongoing expenses is a common battleground.
This responsibility needs to be spelled out, in no uncertain terms, in your separation agreement or a temporary court order. A few common ways to handle it include:
- One spouse pays and gets reimbursed: One person covers all the bills during the sale and is paid back from the gross proceeds at closing, before the final profits are split.
- Both spouses continue to split costs: You each keep contributing your share of the payments, just like you did during the marriage.
- A joint account is used for all expenses: Both parties deposit an agreed-upon amount into a brand new, separate bank account that's used only for house-related bills.
No matter which path you take, document every single penny. Missing a mortgage payment can crater both of your credit scores and even put the home at risk of foreclosure. A clear, written plan here isn't just a good idea—it's essential.
How Do We Handle Taxes on the Sale Profits?
The tax implications of a home sale are a big deal, but there’s some good news. The IRS gives a pretty substantial tax break for selling your primary residence.
Under current tax law, you can exclude a large chunk of the capital gains from your taxable income.
- An individual can exclude up to $250,000 of the gain.
- A married couple filing a joint tax return can exclude up to $500,000.
To get this break, you typically must have owned and lived in the home as your main residence for at least two of the five years right before the sale. It’s sometimes possible for both parties to still claim the full individual exclusion after a divorce, but the rules can get tricky.
Because the timing of your divorce decree and the home sale can drastically change how much you owe Uncle Sam, talking to a CPA or tax advisor isn't optional. It's a critical step.
Navigating the sale of a home during a divorce requires a steady, experienced hand. At Edinhart Realty and Property Management, we provide the expert guidance and neutral support needed to manage your sale professionally, ensuring the best possible financial outcome for both parties. Contact us today to learn how we can help.


