

For years, the cash security deposit has been the unquestioned standard in renting. But let's be honest—it's often a massive financial hurdle for tenants. Security deposit alternatives are changing that dynamic by replacing the need for a huge upfront payment.
Instead of forking over thousands of dollars at once, a renter can pay a much smaller, non-refundable fee or get approved for a special insurance-like product. This gives landlords the financial protection they need against damages or unpaid rent while making it far easier for tenants to move in. It’s a simple shift that gives savvy landlords a serious competitive edge.
Why Security Deposit Alternatives Are Reshaping the Rental Market
The traditional security deposit has always been a point of friction. For many prospective tenants, it’s a major roadblock. In California, a deposit can easily equal one to two months' rent, which often means finding $2,000 to $4,000 in cash on top of the first month's rent. That's a tall order for a lot of great applicants. This single upfront cost can delay move-ins, drive up vacancy rates, and shrink the pool of qualified people who can afford your property.
Security deposit alternatives tackle this problem head-on. They offer a more flexible and accessible path for everyone involved, and the benefits for property owners are substantial:
- A Bigger Pool of Applicants: When you lower the cost of moving in, your property instantly becomes more appealing to a much wider range of qualified renters.
- Shorter Vacancy Periods: Advertising a "deposit-free" option is a powerful marketing tool. It helps you fill units faster, which means less time with an empty property and more rental income in your pocket.
- Better Financial Protection: It might sound counterintuitive, but many of these alternative products offer coverage that actually exceeds a traditional cash deposit. Some industry data shows they can provide up to 50% more protection. You can learn more about how these alternatives offer greater coverage on our blog.
This graphic from Entrata does a great job of showing how these products are built to help both residents and property owners.
The bottom line is that these solutions create a win-win. They remove a major source of stress for tenants and often leave landlords with more comprehensive protection.
Comparing the Core Concepts
To really get why this is such a big shift, it helps to see a side-by-side comparison. The fundamental difference is all about how risk is handled and who carries the initial financial weight. A traditional deposit is just a pile of cash sitting in an account, waiting for a problem. An alternative is a proactive financial tool designed to cover that risk from day one.
At their core, security deposit alternatives convert a large, static liability for tenants into a small, manageable operating cost. This fundamentally changes the leasing dynamic for the better and allows landlords to protect their assets without excluding great applicants who just don't have thousands in spare cash.
Before we dive deeper, here's a quick look at how the old way stacks up against the new.
Traditional Deposits vs Modern Alternatives at a Glance
This table breaks down the key differences in how each approach impacts tenants, accessibility, and your own administrative workload.
| Feature | Traditional Security Deposit | Security Deposit Alternative |
|---|---|---|
| Tenant Financial Impact | High upfront cost (1-2 months' rent) | Low initial cost (small fee or premium) |
| Tenant Accessibility | A significant barrier for many applicants | Increases affordability and widens the applicant pool |
| Administrative Effort | Requires escrow management and strict refund laws | Streamlined claims process with a third-party provider |
As you can see, the alternative model offers a much smoother, more modern experience for everyone involved.
Comparing the Top Security Deposit Alternatives
Deciding on the right security deposit alternative isn't a one-size-fits-all solution. You really need to get into the nuts and bolts of how each model works. They all have different cost structures, coverage levels, and, importantly, claims processes. The best choice for you as a landlord will come down to your property type, how much risk you're comfortable with, and what your local rental market looks like.
Let's break down the big three: Surety Bonds, Lease Insurance, and Credit Authorization services. They all aim to lower the upfront move-in costs for tenants, but how they get there is what sets them apart.
This decision tree gives you a simplified look at how offering an alternative can fit into your tenant screening process.
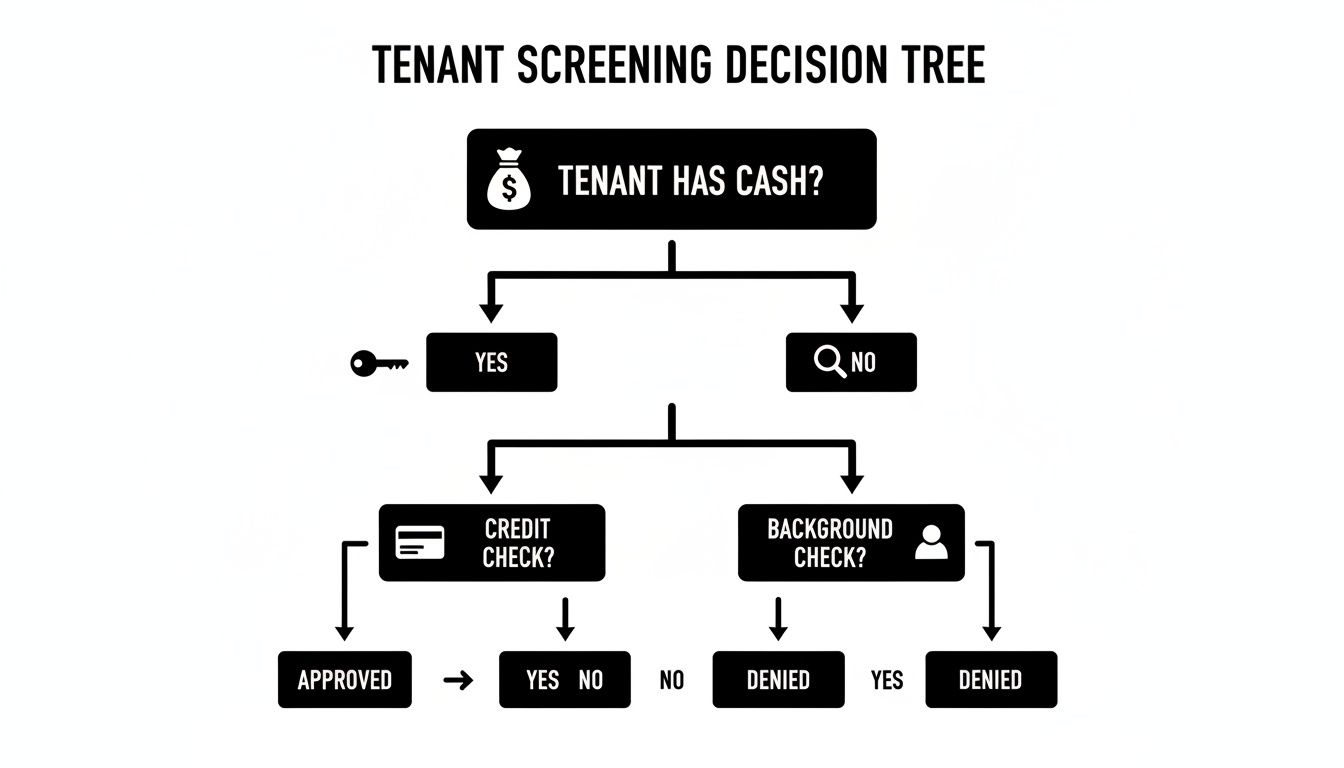
As you can see, it opens up a new path for well-qualified applicants who might be held back by the need for a large cash deposit.
Surety Bonds Explained
Surety bonds have been around for a while and are probably the most established alternative. Here’s the deal: the tenant pays a small, one-time, non-refundable fee to a third-party bond provider. That fee buys a bond that guarantees you, the landlord, will be paid for covered losses like property damage or unpaid rent up to a certain limit.
Think of it as a three-way agreement between the tenant, the landlord, and the bond company. If the tenant causes damage or skips out on rent, you file a claim with the surety company. The company pays you and then goes to the tenant to get that money back.
Key characteristics of surety bonds include:
- Tenant Cost: It's usually a one-time fee, often around 17.5% of what the full deposit would have been.
- Landlord Cost: It's typically free for landlords to offer this option.
- Liability: The tenant is still on the hook. They must repay the bond company for any claims paid out on their behalf.
This model is popular because it's pretty straightforward to set up. Just be aware that the claims process can sometimes feel a bit more cumbersome than just deducting from a cash deposit you're holding.
Lease Insurance Uncovered
Lease insurance, which you might also hear called rental insurance, operates on a completely different framework. With this setup, the landlord buys an insurance policy that covers a whole portfolio of rental units. The cost is usually passed along to tenants as a small, mandatory monthly fee on top of their rent.
Unlike a bond, the insurance policy is held by you, the property owner. When a tenant moves out leaving behind a mess or unpaid rent, you file a claim directly with your insurance provider, who then pays you based on your policy terms.
Here’s the critical difference: with lease insurance, the insurance company typically doesn't chase down the tenant for reimbursement. That small monthly fee they paid was their premium, covering your risk, just like any other insurance policy.
This model makes sense for landlords who want:
- A cleaner, simpler claims process without having to deal with the tenant after they're gone.
- Potentially higher coverage limits, as some policies cover losses that go beyond a standard one-month deposit.
- A steady, predictable bit of extra income from the monthly fees.
It's still incredibly important to understand the importance of renters insurance and require it. Lease insurance protects you, the landlord—not the tenant's personal belongings. You have to make that distinction crystal clear to your residents.
Credit Authorization Services
Credit authorization is a newer player in the game and is quickly gaining traction. These services don't involve a fee or a premium in the traditional sense. Instead, a tenant qualifies by linking their bank account and giving the provider permission to charge them for any approved damages or unpaid rent after they move out.
In essence, the service pre-approves the tenant for a line of credit that covers any potential losses you might incur. For the tenant, this is huge—there is no upfront cost at all. They only pay if a claim is made and approved. For you, it's peace of mind knowing the funds are available to cover legitimate charges.
This approach is incredibly appealing to tenants as it’s the closest thing to a truly "deposit-free" move-in experience.
Key features of credit authorization include:
- Zero Upfront Tenant Cost: Tenants pay nothing to sign up, only for claims filed and approved.
- Direct Landlord Reimbursement: You get paid directly by the provider, who then handles collection from the tenant.
- Rigorous Qualification: Tenants have to meet specific financial standards to be approved.
The main thing for landlords to consider is that the whole model hinges on the provider's ability to successfully collect from the tenant after paying a claim. The top companies, however, have very sophisticated systems in place to manage this effectively.
Detailed Comparison of Security Deposit Alternative Models
To help you weigh your options, this table breaks down the core differences between the three main alternatives. Use it as a quick reference to see which approach best aligns with your properties and management style.
| Alternative Type | How It Works | Typical Tenant Cost | Landlord Cost | Coverage Scope | Best for Landlords Who… |
|---|---|---|---|---|---|
| Surety Bond | Tenant pays a one-time fee to a bond company that guarantees payment to the landlord for approved claims. The tenant must repay the bond company. | One-time, non-refundable fee (e.g., 17.5% of deposit). | Generally none. | Covers specific damages and unpaid rent up to a pre-set bond amount. | Want a straightforward, widely understood option and don't mind a formal claims process. |
| Lease Insurance | Landlord buys a policy for their portfolio. Tenants pay a small, recurring monthly fee. Landlord files claims with the insurer. | Small monthly fee added to rent (e.g., $10-$30/mo). | Typically none, as the cost is passed to the tenant. | Can offer broader coverage, sometimes exceeding a standard deposit amount. | Prefer to manage risk across all units and want a claims process that doesn't involve tenant collections. |
| Credit Authorization | Tenant authorizes a provider to charge their account for approved post-move-out charges. No upfront cost for the tenant. | $0 upfront. Tenant only pays if a claim is made and approved. | Typically none. | Covers approved charges for damages and unpaid rent, backed by the tenant's pre-authorized account. | Want to offer a completely cost-free move-in incentive to attract a wider pool of qualified applicants. |
At the end of the day, any of these alternatives can be a powerful tool for filling vacancies faster. By taking a hard look at how each one fits with your business goals, you can pick a solution that gives you solid protection while making your properties more accessible for great tenants.
A Landlord's Guide to Benefits and Risks
Jumping into security deposit alternatives isn't just a minor operational tweak—it's a full-blown strategic move. As a landlord, you need to go in with eyes wide open, ready to weigh the genuine rewards against the potential headaches. The upside goes way beyond just getting more applicants; these options can fundamentally change your leasing game, often for the better.
But it’s not all smooth sailing. With these new benefits come new responsibilities and risks that you absolutely have to manage. Getting this trade-off right is the secret to making a deposit-free policy work for you and your properties.
The Clear Advantages for Property Owners
Let's start with the most obvious win: marketing power. When you advertise a "deposit-free" option, your applicant pool can explode. Suddenly, you're attracting highly qualified tenants who have the income for rent but maybe not thousands in cash sitting around for a deposit. It makes your property instantly more accessible.
That wider appeal usually leads to one thing: faster lease-ups. We’ve seen properties using these alternatives achieve 36% faster conversions. For a portfolio of 500 units, that can translate to over $90,000 in additional revenue each year. It’s a game-changer, especially for a full-service management company like ours.
But the benefits don't stop at speed. Many of these products offer financial protection that’s actually better than a traditional deposit.
- Enhanced Coverage: Some lease insurance programs blow past the state-mandated deposit caps. This means you’re covered for damages or unpaid rent that a standard one-month deposit wouldn't even touch.
- Reduced Administrative Work: Forget about managing escrow accounts and navigating California's strict 21-day refund timeline. The claims process is outsourced to a third party, which seriously streamlines the move-out chaos.
- Competitive Edge: As more renters learn about these options, offering them gives you a real leg up in a crowded market. It positions your property as modern and tenant-focused.
Understanding the Potential Risks and Drawbacks
As great as that all sounds, you have to be realistic about the risks. The biggest shift is that you're no longer holding the cash. Instead, you're relying on a third-party company to reimburse you, which introduces a whole new set of rules.
Learning to navigate a provider's claims process is probably the biggest hurdle. You can't just deduct from a deposit anymore. You have to submit a formal claim with meticulous documentation—photos, invoices, move-out reports—and wait for a third party to approve it. The timeline and the final decision are out of your direct control.
A common pitfall for landlords is assuming all provider agreements are the same. Each has unique terms for what constitutes a covered loss, the documentation required for a claim, and the dispute resolution process. Diligent review is not just recommended; it is essential.
To properly vet these providers, using a solid contract review checklist is a must. It forces you to dig into the details and understand your rights and obligations before you’re locked in.
Another risk is tenant confusion. It is critical that your residents understand they are not simply off the hook for damages. With surety bonds or credit authorizations, the tenant is still financially liable and will have to reimburse the provider for any claims paid out. If that’s not communicated clearly from day one, you’re setting yourself up for disputes and bad reviews down the line.
Navigating California's Legal Landscape
Before you jump into offering security deposit alternatives, it’s crucial to know where you stand with California law. The Golden State has some of the most specific and rigid landlord-tenant laws in the country, especially around security deposits. While these modern alternatives operate on a different track, they don't get a free pass. One wrong move can land you in a costly legal mess, so getting this right is non-negotiable.
The most important thing to understand is that these products—surety bonds, lease insurance, you name it—are not legally considered a 'security deposit' under the California Civil Code. This is a game-changer. It means they aren't bound by the same strict rules, like holding funds in a separate account or adhering to the state's deposit caps.
But that distinction puts the ball squarely in your court. You have to be crystal clear in your lease agreements and how you talk to tenants. They need to know exactly what they're paying for, that any fees are non-refundable, and that they're still on the hook for damages when they move out. Transparency isn’t just good practice; it's your best defense.
California Deposit Limits and Alternative Coverage
California law is very clear about how much a landlord can collect for a security deposit. For an unfurnished home, the max is two times the monthly rent. If the property is furnished, you can go up to three times the monthly rent. These caps are there to keep housing accessible by limiting a tenant's upfront move-in costs.
This is where security deposit alternatives really show their value. Since the premiums tenants pay aren't classified as a deposit, the coverage you get from the third-party provider can actually exceed these legal limits. It’s not uncommon for a lease insurance policy to offer protection equal to three or even four months' rent, even on an unfurnished unit.
This ability to get more financial protection is a huge reason landlords are making the switch. It provides a much stronger safety net against major damages or a long vacancy that a traditional deposit, by law, just can't cover.
Just remember, you can't have it both ways. You are not allowed to charge a tenant the maximum legal security deposit and require them to buy into an alternative program. The best practice, and the safest from a legal standpoint, is to offer it as a choice. Let the tenant decide if they want to pay the traditional cash deposit or go with the alternative.
The 21-Day Rule and Claims Processing
Anyone who's been a landlord in California for a while knows the 21-day rule. Once a tenant moves out, the clock starts ticking. You have exactly 21 calendar days to either return their full deposit or send an itemized list of deductions with any remaining balance. If you're even one day late, you can lose your right to deduct anything at all.
Security deposit alternatives throw that entire process out the window. Forget the 21-day countdown. Instead, you'll follow the claims process set by your provider, which usually looks something like this:
- Document Everything: At move-out, you’ll need to meticulously document the property's condition with tons of photos, videos, and detailed notes.
- Submit Your Claim: You'll file the claim through the provider's online portal, uploading all your proof and invoices for repairs.
- Provider Review: The company then reviews your claim, making sure it’s valid and follows their policy rules.
- Get Reimbursed: Once approved, the provider pays you directly for the covered damages and losses.
This system takes the pressure off the 21-day deadline, but it doubles down on the need for rock-solid documentation. The provider is the one cutting the check, so they're going to want to see clear, undeniable proof for every dollar you claim. If you want to dig deeper into the specifics, our guide to landlord-tenant law in California has you covered. Ultimately, this new workflow just reinforces how critical a thorough move-in and move-out inspection process truly is.
How to Implement Your New Deposit Policy
Deciding to offer security deposit alternatives is one thing, but rolling them out smoothly is another challenge entirely. A messy launch can create confusion for tenants, headaches for your staff, and even legal trouble. The key is to weave your new policy into every part of the leasing cycle, from the moment a prospect sees your ad to the final move-out inspection.
Launching a deposit-free option is about more than just picking a provider and calling it a day. It means rethinking your marketing, updating your legal paperwork, and making sure everyone on your team is on the same page. When you get it right, a good idea becomes a genuine operational advantage.
Selecting the Right Partner
First things first: you have to vet and choose a solid provider. Not all security deposit alternative programs are built the same. You need a partner with a proven track record, crystal-clear terms for everyone involved, and a claims process that actually works when you need it.
Look closely at the financial stability and compliance of any company you're considering. The best firms in the U.S. have proven that these options can actually provide more coverage than a traditional deposit, often protecting you for the entire lease term without a cap. That’s a huge win for property owners. You get to replace a limited cash deposit with a low-cost, tenant-paid premium that’s backed by real insurance.
When you work with a professional property manager like Edinhart, we take this whole process off your plate. We’ve already done the homework, evaluating providers on their reliability, how they handle claims, and whether they align with California’s strict legal standards. This ensures you get the best protection with the least amount of risk.
Updating Marketing and Lease Agreements
Once you’ve got a partner, it's time to shout it from the rooftops. Update all of your property listings and marketing materials to highlight your new "deposit-free" or "low-cost move-in" option. This is a powerful hook that attracts a much wider pool of qualified applicants and can slash your vacancy time.
Next up is the lease agreement—this is a legal must-do. You have to add specific language that clearly lays out the alternative you’re offering.
Your lease addendum should detail:
- That the program is an optional alternative to a traditional cash security deposit.
- The name of the third-party provider.
- A clear statement that any fee or premium paid is non-refundable.
- An explanation that the tenant remains financially responsible for any damages or unpaid rent.
By framing the alternative as a choice, you empower tenants while staying compliant. The language has to be completely unambiguous to avoid any arguments over financial responsibility when they move out.
Training Your Team and Educating Tenants
Your leasing staff are on the front lines, so they need to be able to explain the new policy with confidence. We equip them with scripts, FAQs, and training so they know exactly how the program works, what the benefits are for tenants, and what the tenant’s responsibilities are.
During the application process, your team should clearly walk every applicant through their options. They'll break down the upfront cost of the traditional deposit versus the smaller fee for the alternative. This transparency builds trust from day one and helps tenants make a smart decision.
Finally, remember that the move-out process will change. Your team needs to understand the new claims workflow and know just how critical detailed documentation is. Following our landlord move-out inspection checklist becomes more important than ever.
Common Questions About Security Deposit Alternatives
As landlords and property owners start thinking about moving away from the old-school security deposit, a lot of practical questions pop up. It makes sense. Bringing in a new system means getting clear on everything from legal duties to the day-to-day operational shifts. This section tackles the most common questions we hear, helping you navigate the move to security deposit alternatives with confidence.
Getting these details right from the start is what makes your new policy work. It ensures you're compliant, effective, and easy for both you and your tenants to understand.
Am I Required to Offer an Alternative to All Tenants?
In California, no state law requires you to offer a security deposit alternative. The real issue here, and where landlords can get into hot water, is discrimination. The key is consistency. If you decide to go with a deposit-free option, you have to apply that policy the same way for every single qualified applicant.
The best way to handle this is to frame it as a choice for every tenant you approve. Once they pass your normal screening, you can lay out the two paths: pay the traditional cash security deposit or enroll in the alternative program. This gives tenants a sense of control and, more importantly, shows you're treating everyone fairly, which is your best defense against potential legal claims.
A critical mistake is offering alternatives on a case-by-case basis. This can look discriminatory, even if you don't mean for it to be. A clear, written policy that you stick to every time is your best protection.
What Happens if a Tenant Stops Paying the Monthly Fee?
This is a totally valid concern, and one we hear all the time, especially with alternatives that use a monthly fee model. If a tenant stops making those payments, the provider will almost certainly cancel their coverage.
When that happens, the tenant is now in breach of the lease agreement. Your lease should spell out exactly what you can do next. The standard procedure is to require the tenant to pay a full traditional cash security deposit within a set amount of time to fix the breach.
This is where professional property management systems really shine. They can track these payments, automatically flag when one is missed, and handle the communication needed to get things sorted out quickly. It ensures your property stays protected without any gaps.
How Does the Claims Process Differ from a Cash Deposit?
The paperwork and workflow for making a claim is completely different—and often more structured—than just deducting from a cash deposit you're holding. With a cash deposit, you're on the hook for sending an itemized list of deductions within California's strict 21-day deadline.
With a security deposit alternative, you're working with a third-party provider. Here’s how it usually plays out:
- Damage Assessment: You do a thorough move-out inspection, documenting everything with photos, videos, and detailed notes.
- Claim Submission: You file a formal claim through the provider's online portal, uploading all your proof and repair invoices.
- Provider Review: The company reviews your claim to make sure it's covered under the policy and that your evidence backs it up.
- Reimbursement: Once approved, the provider pays you directly for the covered damages.
This system often gets you your money back faster and takes the pressure of the 21-day rule off your shoulders. The trade-off? It demands meticulous record-keeping. To get a better sense of the old-school process this replaces, check out our guide on what a security deposit is used for.
Can I Use an Alternative Alongside a Small Cash Deposit?
Trying to create a hybrid system—where you collect a small cash deposit and have the tenant pay for an alternative—is a legal minefield in California. The state's Civil Code is very clear: any payment a tenant makes for security purposes counts toward the legal maximum you can hold.
If you combine a partial cash deposit with a premium for an insurance product, a court could easily see that as you exceeding the legal limit. For example, if the max deposit allowed is $3,000, and you take $1,000 in cash plus a $300 fee for a bond that gives you $3,000 in coverage, you're essentially securing $4,000 in protection. That's a violation.
To stay compliant and keep things simple, the safest bet is to pick one lane and stay in it. Either stick with a traditional security deposit or go all-in on an alternative—don't mix them. A property management professional can help you build a policy that protects you and is 100% compliant with California law.
Figuring out the world of security deposit alternatives can feel overwhelming, but you don't have to go it alone. The experts at Edinhart Realty & Property Management can help you put a compliant, effective policy in place that protects your investment while attracting the best tenants in the Fresno area. Contact us today to learn how we can take your rental strategy to the next level.


