

You've built up some cash. Maybe it came from years of work, a home sale, an inheritance, or just finally getting serious about saving. Now you're staring at the same fork in the road a lot of Central Valley investors face. Should that money go into the stock market, where it's liquid and easy to manage, or into a rental property, where the upside can look stronger but the work is real?
That question sounds simple, but it isn't. In practice, rental property vs stock market comes down to control, time, temperament, and whether the local numbers work. In Fresno and the surrounding Central California market, that last point matters more than is often acknowledged. A property can look great in a generic online calculator and still turn into a weak investment once you account for rent levels, repairs, management, and vacancy.
The better way to look at it is this. Stocks and rentals are both legitimate wealth-building tools. They just solve different problems. One gives you passive ownership in businesses. The other gives you a tangible asset you can influence directly. If you want a clean decision, you need a framework, not hype.
The Ultimate Investment Question
A lot of investors come into this decision looking for a winner. They want someone to say stocks always beat real estate, or rental properties always beat stocks. That's usually where bad advice starts.
The stock market is simple to access, easy to diversify, and far more liquid. Real estate gives you something stocks usually don't. Control over the asset, control over financing, and the ability to improve performance through operations. Those aren't small differences. They change how returns are created.
What most people are really asking
When someone asks about rental property vs stock market, they're usually asking a few separate questions at once:
- Which path fits my schedule: If your career already eats up your week, a second job disguised as an investment may be a bad fit.
- How much risk can I handle: Some people hate seeing market swings in a brokerage account. Others hate the idea of a vacancy or a roof replacement.
- Do I want income now or growth later: Rentals often appeal to people who want cash flow. Stocks often appeal to people who want simplicity and long-term compounding.
- How much control matters to me: With stocks, you're along for the ride. With property, your decisions affect the outcome.
A good investment on paper can still be the wrong investment for the person holding it.
In Fresno, Clovis, Friant, and the broader Central Valley, this decision gets even more practical. Local rent levels, neighborhood quality, school districts, tenant demand, commute patterns, and property condition all change the math. National averages don't buy a property, screen a tenant, or cover an HVAC replacement in July.
The right question to ask
Don't ask which asset class wins in every situation. Ask which one fits your capital, your goals, and your willingness to manage complexity.
That's how experienced investors approach it. They stop chasing slogans and start comparing the actual mechanics of each option.
Two Paths to Building Wealth
A Fresno investor with $60,000 to put to work usually ends up looking at two very different paths.
One path is simple. Put the money into index funds, add to it every month, and let time do the work. The other path is hands-on. Use that same cash for a down payment, buy a rental in the right neighborhood, and build returns through rent, debt paydown, and property performance.
Both can work. They just ask different things from the person writing the check.
Stocks are ownership in businesses. The upside comes from price growth and, in some cases, dividends. The appeal is obvious. They are easy to buy, easy to hold, and easy to spread across many companies in one fund.
Rental property is ownership in a specific asset with real operating decisions attached to it. In Fresno, that can mean deciding whether a property near Fresno State will rent better to students, whether a Clovis-area home will attract longer-term tenants, or whether an older Central Fresno property has enough margin left after repairs to make sense. Returns are tied to purchase price, financing terms, vacancy, maintenance, rent collection, and your ability to manage the property well.
What stocks do well
Stocks fit investors who want a passive system with very little day-to-day involvement. Money can be invested in minutes. Selling is usually quick. Rebalancing is straightforward.
That matters for busy professionals, out-of-area investors, and anyone who knows they do not want calls about plumbing leaks, late rent, or turnover costs.
Stocks also make diversification easier. One broad-market fund can spread risk across hundreds of companies. A single rental property does not. One bad roof, one rough tenant, or one long vacancy can have an outsized effect on annual returns.
What rental property does differently
Rental property gives the owner more ways to create results.
A well-bought property can produce monthly cash flow. Tenants reduce the loan balance over time. The property may appreciate. An owner can also improve the outcome by raising below-market rents, tightening expense control, improving management, or buying a property that needs smart cosmetic work instead of major reconstruction.
That level of control is the draw. It is also the burden.
In the Central Valley, execution matters more than the headline return estimate. A rental in the wrong pocket of town, bought with thin reserves, can turn into an expensive lesson. A rental bought at the right price with realistic maintenance assumptions can outperform because the owner made good operating decisions, not because real estate automatically wins.
For investors comparing actual deals, a solid investment property analysis process matters more than broad national averages. The spreadsheet has to reflect Fresno rents, insurance, taxes, repairs, and vacancy, not a generic estimate pulled from a national article.
Stocks reward consistency. Rental property rewards pricing discipline, financing discipline, and management discipline.
That is why I do not treat this as a winner-take-all decision. Some investors should stay with stocks because simplicity fits their schedule and temperament. Others are better served by rentals because they want more control and are willing to handle the work that comes with it.
A Side by Side Investment Comparison
A Fresno investor with $120,000 to deploy usually narrows the choice to two paths. Put the money into index funds and keep life simple, or use part of it as a down payment on a rental and accept the work that comes with ownership. The better option depends less on headlines and more on what kind of return, risk, and involvement that investor can handle.
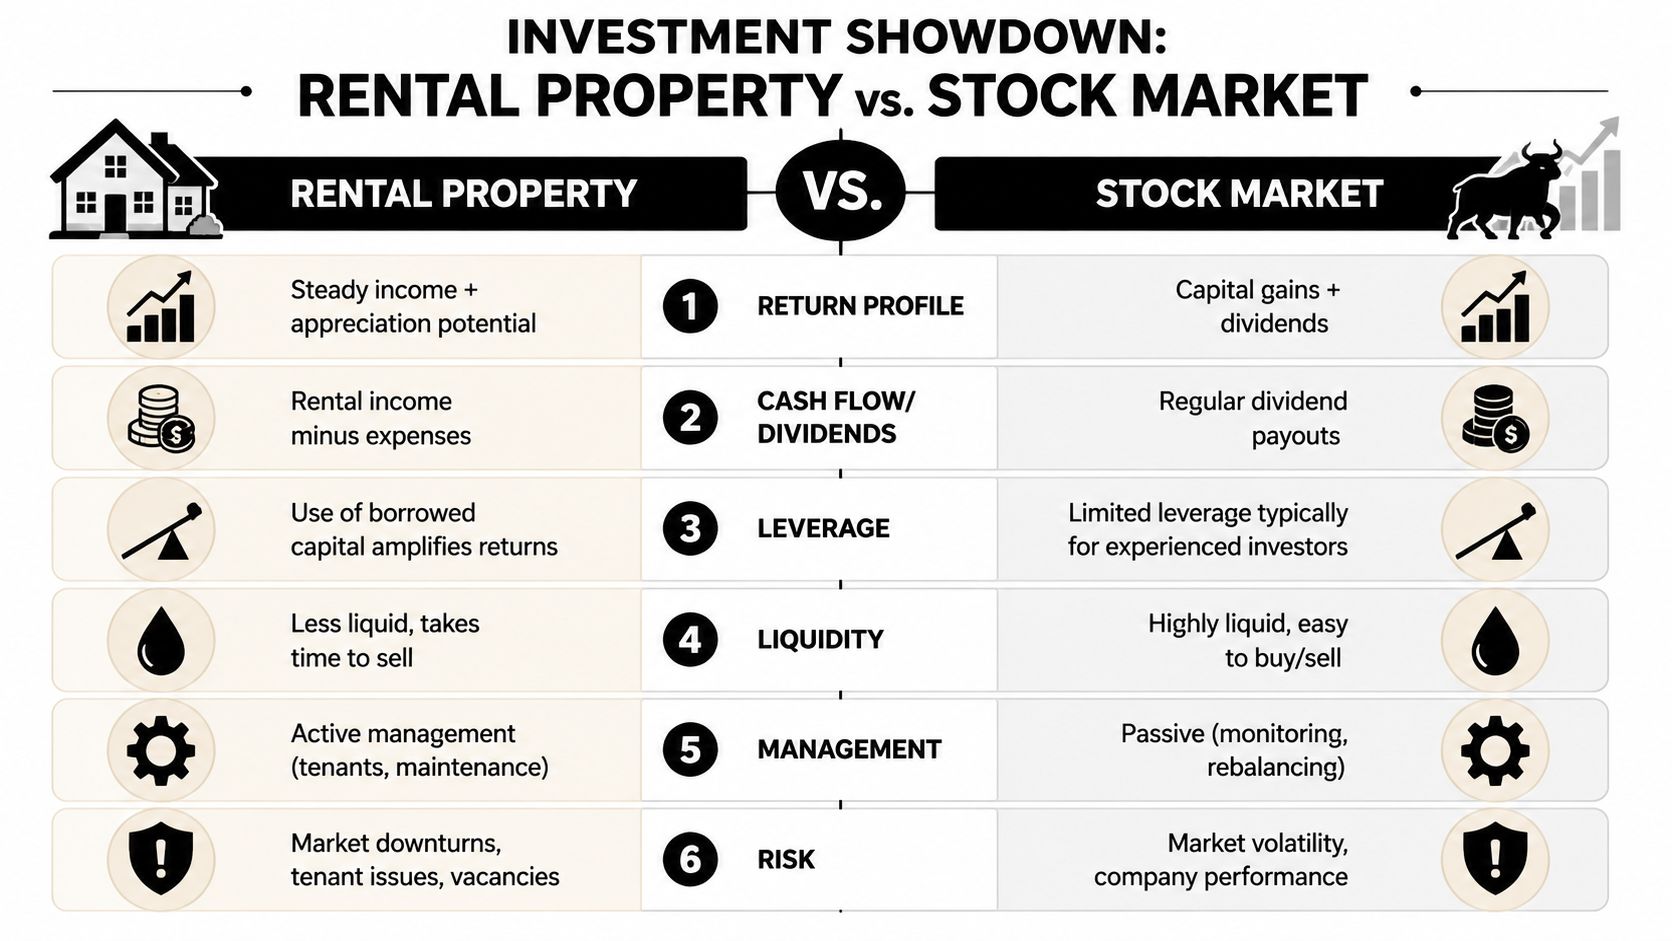
| Factor | Rental Property | Stock Market |
| |—|—|
| Return profile | Cash flow, loan paydown, tax benefits, and appreciation | Capital gains and dividends |
| Volatility | Values move slower, but property-specific problems hit hard | Prices reset every trading day |
| Liquidity | Slow to sell and expensive to exit | Easy to buy and sell |
| Financing | Mortgage debt is widely available on investment property | Borrowing usually means margin, with stricter risk |
| Management | Active, unless you hire it out | Mostly passive |
| Control | You can change rents, expenses, and operations | You own shares, not the business decisions |
Return profile
Stocks are cleaner. Rentals are layered.
A stock investor usually gets return from price growth and dividends. A rental owner can earn monthly cash flow, build equity as the tenant pays down the loan, claim tax benefits, and still participate in appreciation. That is why a simple side-by-side comparison based only on appreciation misses how rental property performs in practice.
The catch is execution. A Fresno rental bought with thin cash flow and deferred maintenance can underperform fast. A modest house in a stable rental pocket with realistic reserves can produce a solid total return even if appreciation is average.
Risk and volatility
Stock risk is visible every day. Real estate risk shows up in chunks.
A portfolio can drop this afternoon and recover next quarter. A rental may look stable for months, then take a vacancy, a plumbing failure, and a $9,000 turnover bill in the same stretch. The account statement on stocks is harsher. The repair invoice on property is more personal.
In Fresno and surrounding Central Valley markets, concentration risk matters. One rental on one street carries more location risk than a broad stock fund spread across hundreds of companies.
Liquidity
Stocks win this category by a mile.
If an investor needs cash for a business opportunity, medical expense, or family issue, stocks can usually be sold the same day. A rental sale takes time, and the exit cost is real. Commissions, closing costs, repairs, and concessions can eat into gains. Refinancing can help, but that depends on rates, equity, and lender standards.
Financing
Property gives investors a financing tool that stocks usually do not.
An investor can buy a rental with a down payment and a mortgage, then let rent help cover the debt service. For borrowers focused on income-producing property, New American Funding DSCR options are one example of how financing can be based on the asset's cash flow rather than personal income alone. That can widen the path into rentals, but it also raises the importance of buying right. If the property does not carry itself, the loan becomes pressure instead of help.
For that reason, a detailed investment property deal analysis for Fresno rentals matters more than broad return averages.
Management burden
Stocks ask for discipline. Rentals ask for decisions.
A rental owner deals with leasing, screening, maintenance, insurance renewals, city requirements, bookkeeping, and turnover timing. A property manager can reduce the day-to-day load, but that cost needs to be built into the numbers from the start. Investors who ignore the labor side of rentals usually overstate the return.
Tax treatment
Real estate often has stronger tax advantages on paper. Stocks are simpler to report and easier to manage.
Neither one gets a pass on bad pricing. A weak rental is still a weak rental, even with deductions. A stock portfolio bought without a plan is still exposed to panic selling at the wrong time.
The practical comparison is straightforward. Stocks offer liquidity, simplicity, and broad diversification. Rentals offer control, financing options, and several ways to build return from one asset. In Fresno, the right answer usually comes from the deal, the financing, and the investor's tolerance for hands-on ownership.
Understanding The Power of Leverage
The potential for amplified returns with borrowed funds is why many investors stay interested in rental property even when they know the stock market is easier.
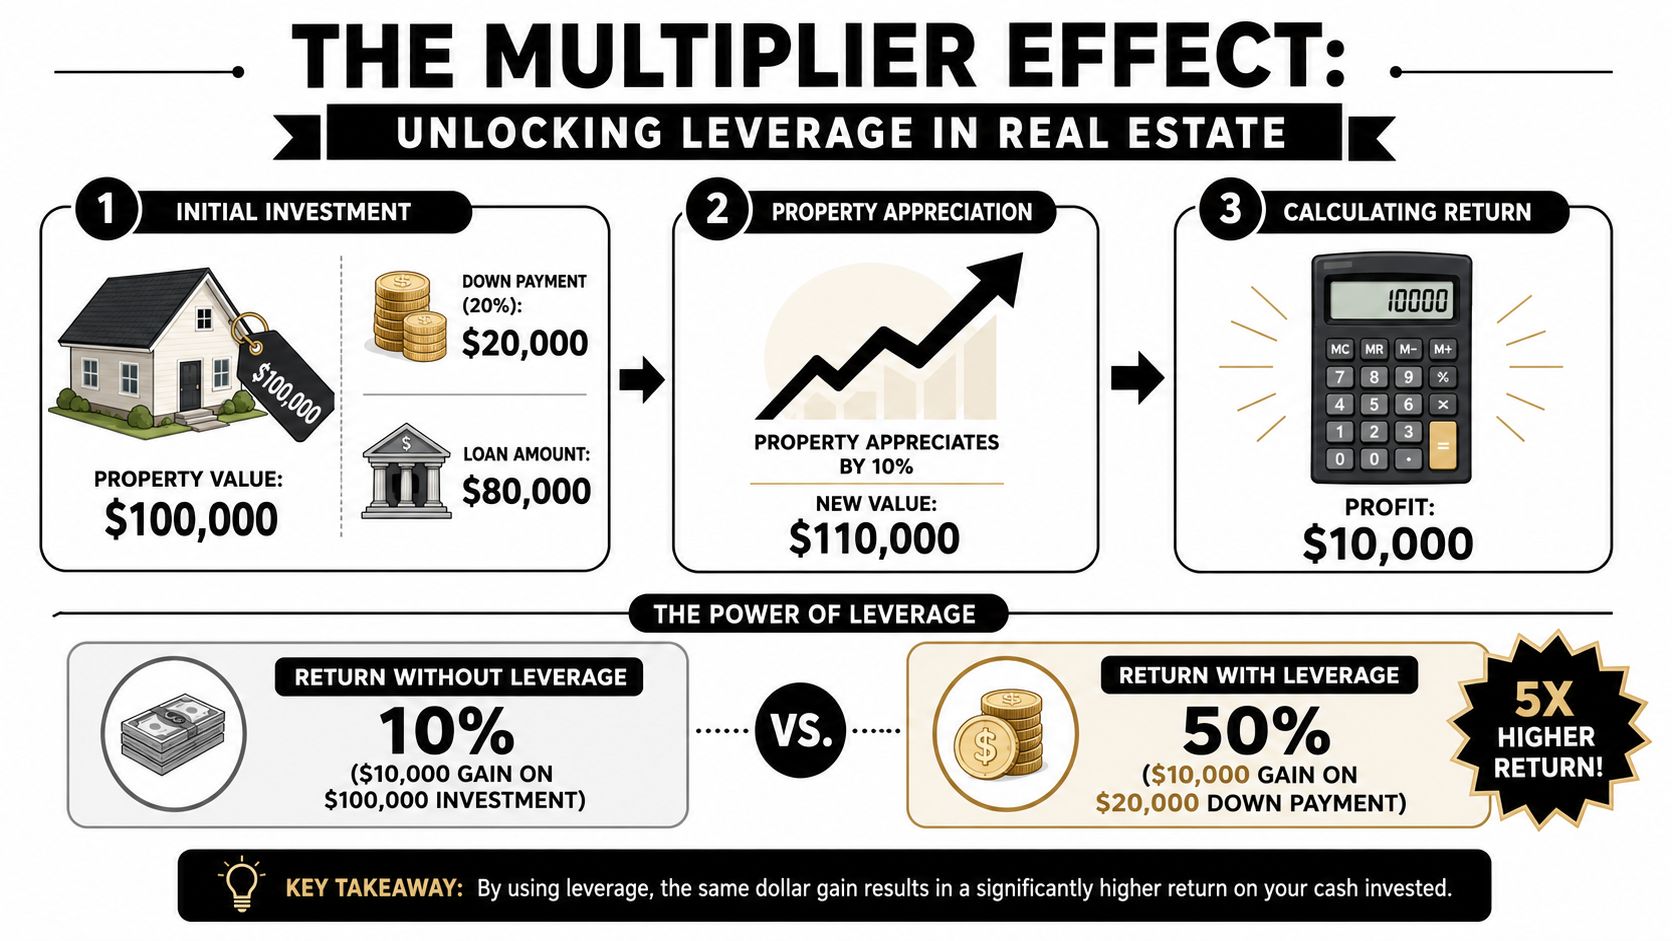
If you buy stocks, your return is usually based on the cash you invested. If you buy a rental with financing, your return is affected by the value of the whole property, not just your down payment. That's a major difference.
The simple math
A well-managed rental can deliver 8% to 12% annual ROI, and the use of borrowed capital can push returns on actual cash invested to 25%+ with a 20% down payment, according to AvantStay's explanation of leveraged real estate returns. Their example is straightforward. A $100,000 property bought with 20% down means $20,000 in cash invested. If the property appreciates by 5%, that creates a $5,000 gain, which equals a 25% return on the cash invested. The same $100,000 placed in stocks with 5% appreciation produces a 5% return.
That's the attraction. The bank finances most of the asset, but you benefit from the gain on the full property value.
Why this matters in practice
Borrowed funds can amplify a good deal. They can also amplify a bad one.
If the property has weak rent, too much deferred maintenance, or thin reserves, debt doesn't help. It increases pressure. That's why investors who do well with rentals don't just chase appreciation. They underwrite the property like a business.
For buyers who are comparing lending paths, a resource on New American Funding DSCR options can help clarify how debt-service coverage financing works for rental property purchases. That matters when you want financing tied more closely to property income than to traditional owner-occupied underwriting.
A financing plan also has to match the investor's broader goals. If you're looking at purchase strategy, reserves, and cash-flow structure, this guide to real estate investor financing is a useful place to think through the moving parts before making offers.
Here's a short walkthrough that explains the concept visually and in plain language.
Leverage is powerful when the asset already works. It doesn't rescue a weak property.
That's the part people skip. In Fresno and the Central Valley, using borrowed money can absolutely improve returns. But only when rent, condition, financing, and reserves line up.
Why The Fresno Market Changes The Math
National advice tends to flatten real estate into one category. It isn't one category. Real estate is local, and local math decides whether a rental property beats a stock portfolio for a specific investor.
That's especially true in Fresno and the surrounding Central California market. Investors here aren't buying an abstract asset class. They're buying one house on one street in one school district, with one rent ceiling and one maintenance profile.
The metric that matters more than hype
A key factor is the rent-to-price ratio. Real estate only consistently outperforms stocks when monthly rent is at least 0.8% to 1% of the purchase price, according to Iconic Property Management's discussion of when rental property outperforms stocks. That threshold is what makes the deal mathematically favorable from day one.
That's a more useful screen than a general claim about appreciation. Appreciation is nice. Rent is what carries the property month to month.
Why local knowledge matters
In the Fresno area, neighborhoods can produce very different outcomes even when homes look similar online. A property near stable employment, strong commuting patterns, and durable tenant demand usually gives you a better operating base than one that only looks cheap at purchase.
When investors get into trouble, it's often because they bought based on a listing photo and a spreadsheet, not on local leasing reality. They assumed every house would rent quickly, every tenant pool would be similar, and every maintenance line would behave the same. That's not how it works.
A practical local filter looks something like this:
- Rent support: Can the neighborhood support the target rent without overreaching?
- Property condition: Will the house need immediate capital work, or can it perform cleanly from the start?
- Tenant demand: Is the property in an area where qualified renters consistently want to live?
- Operational friction: Will layout, age, deferred maintenance, or location create more turnover and repair calls?
In real estate, location isn't branding. It's a cash-flow filter.
That's why Fresno changes the math. The right Central Valley property can produce a reasonable blend of rent, tenant demand, and long-term hold potential. The wrong one can underperform even if the purchase price looked attractive.
Calculating Returns Without The Rose Colored Glasses
A lot of online rental calculators are too optimistic to be useful. They make property investing look cleaner, easier, and more profitable than it usually is in real life.
The biggest problem is what they leave out. Many comparisons ignore property management, underestimate vacancy, gloss over capital expenditures, and treat maintenance like a minor line item. That creates returns that look strong on paper and disappoint in ownership.
The costs investors skip
A more realistic view comes from Rental Income Advisors' review of stocks versus rental properties, which notes that property management fees of 8% to 10% of monthly rent, vacancy gaps, and capital expenditures are often excluded from simplified models. Once those expenses are included, theoretical cash-on-cash returns can fall into a more practical 3% to 5% range.
That doesn't mean rentals are bad investments. It means sloppy underwriting produces bad expectations.
A cleaner way to evaluate a rental
When reviewing a property, use a more conservative framework:
- Start with actual rent, not hoped-for rent: Base income on what the market supports now.
- Include management even if you plan to self-manage: Your time has value, and future buyers or partners may not self-manage.
- Reserve for vacancy: Units don't stay full forever.
- Budget for capital items: Roofs, HVAC systems, flooring, and exterior work are part of ownership.
- Stress test the deal: Ask whether the property still works if repairs come early or rent growth stalls.
For investors who also hold stocks, good discipline carries over. Position sizing, downside planning, and reserve thinking matter in both asset classes. A resource like Rize Trade's risk management guide is useful because the core principle applies across investing. Protect capital first, then chase return.
If you want a more grounded method for analyzing the full picture, this breakdown of how to calculate total return on investment is a better starting point than a glossy calculator.
Practical rule: If a rental only works when every assumption goes right, it doesn't work.
That's the discipline many first-time investors miss. In rental property vs stock market decisions, rentals lose credibility when buyers pretend the headaches and costs aren't real.
Your Investment Framework and Next Steps
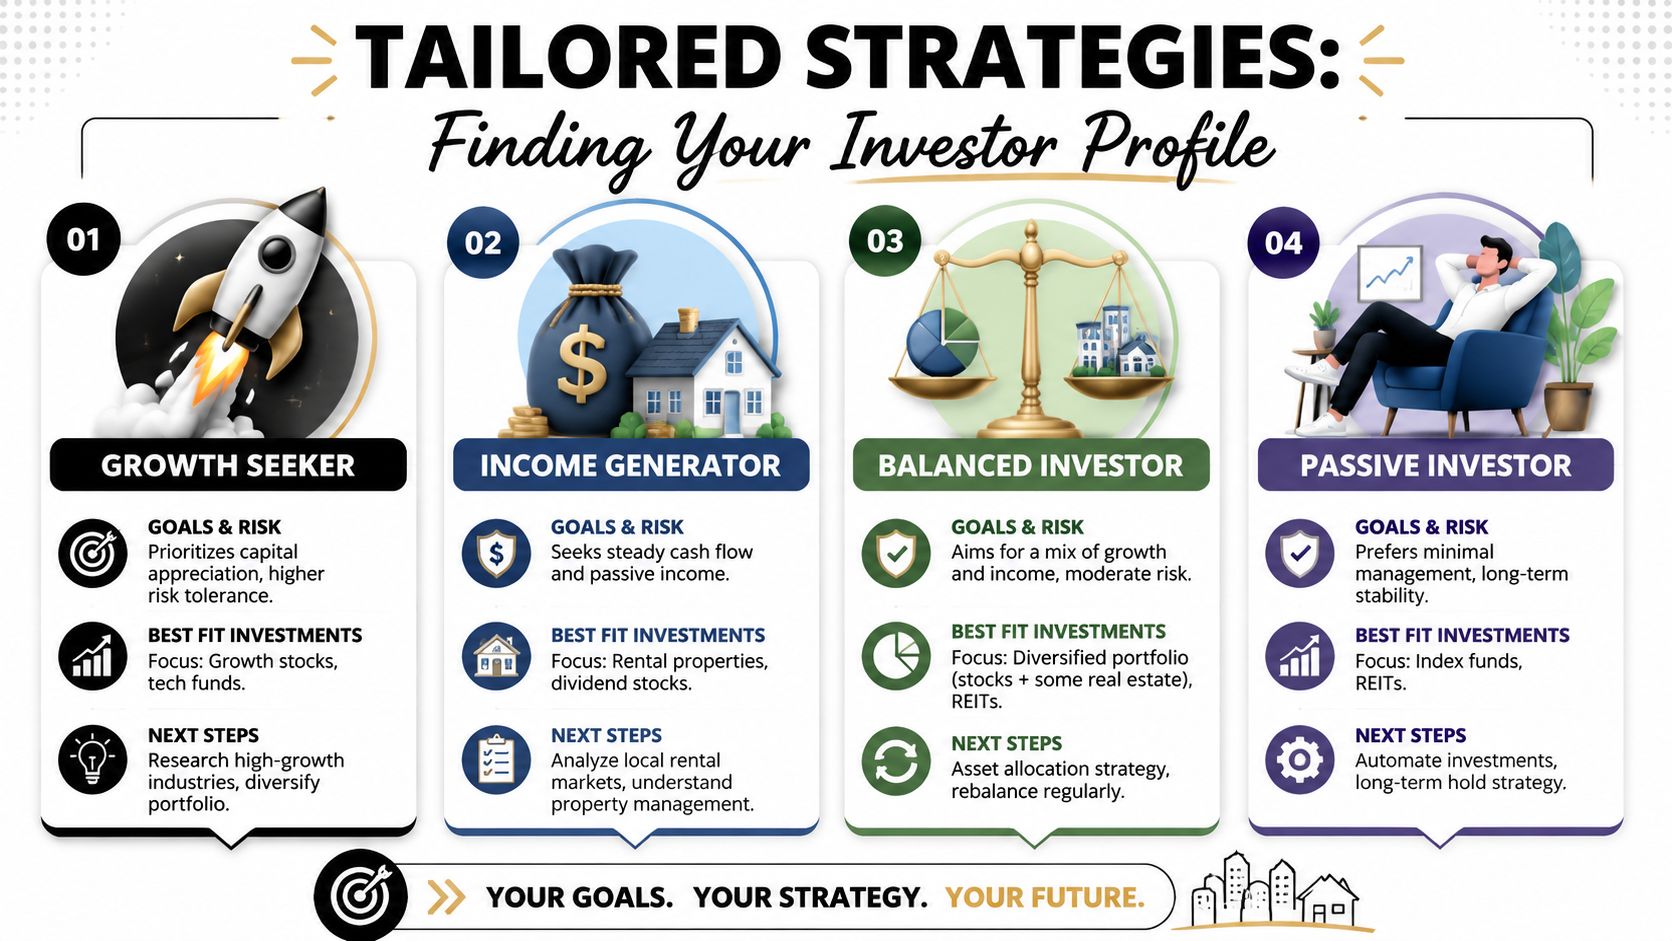
The right answer usually isn't “stocks” or “real estate.” It's “which one fits the investor you are right now.”
A busy surgeon, a local contractor, a retiree seeking income, and a younger professional building long-term wealth shouldn't all make the same choice. They have different time constraints, different risk tolerance, and different interest in being hands-on.
The busy professional
This investor values simplicity and consistency. They don't want midnight repair calls or leasing decisions competing with work and family life.
Stocks usually fit this profile well. So can rental property, but only if the property is treated as a managed asset rather than a personal side project. If the investor wants direct real estate exposure without day-to-day involvement, the management structure matters as much as the purchase itself.
The hands-on builder
This investor wants control. They like finding an opportunity, improving operations, tightening screening, controlling expenses, and using financing strategically.
Rental property usually fits better here. Not because it's guaranteed to outperform, but because this type of investor can turn local knowledge and discipline into better results. They see a property as a business unit, not just an asset on a statement.
The income-focused investor
Some investors care less about abstract account growth and more about recurring income. They want money coming in, and they like the idea that tenants help pay down debt over time.
Rental property often appeals to them first. Dividend-paying stocks can still play a role, but the appeal of a physical asset with rent-driven income is usually stronger. The key is staying conservative on expenses and reserves.
The balanced investor
This is often the strongest long-term profile. Part of the portfolio stays in stocks for liquidity and diversification. Part goes into real estate for income, control, and magnified returns.
That mix can reduce the pressure to force one asset class to do everything.
A simple framework looks like this:
| Investor profile | Usually leans toward | Why |
|---|---|---|
| Busy professional | Stocks or fully managed rental | Less day-to-day friction |
| Hands-on builder | Rental property | More control and operational upside |
| Income-focused investor | Rental property with conservative underwriting | Better alignment with cash-flow goals |
| Balanced investor | Mix of both | Diversification across different strengths |
The strongest move is usually the one you can hold through stress. A stock portfolio only works if you won't panic when markets swing. A rental only works if you'll manage it with discipline, fund reserves, and make decisions based on numbers instead of hope.
That's where execution matters. In the Central California market, some owners want a completely hands-off approach, while others want help only with marketing, screening, and lease setup so they can manage the rest themselves. Both approaches can work if they match the investor.
If you want help evaluating rental opportunities, leasing strategy, or property management options in Fresno, Clovis, Friant, or the broader Central California market, Edinhart Realty and Property Management offers both full-service management and placement-only support for owners who want a more customized approach.


