

Financing an investment property isn't quite like getting a mortgage for the home you live in. It's a completely different ballgame. The world of real estate investor financing covers a whole spectrum of funding options, from the familiar comfort of traditional bank loans to faster, more flexible solutions like hard money, private lending, and creative financing. The right move for you boils down to your specific strategy, how quickly you need to act, and the details of the deal on the table.
Your Guide to Investor Financing
Think of capital as the fuel for your real estate portfolio. Getting financing isn't some roadblock to dread; it's a strategic toolkit, and each tool is designed for a different job. When you apply for a standard home loan, the bank is laser-focused on your personal income and credit score. But for an investment property? They’re scrutinizing the property’s ability to make money.
This is why, for any serious investor, accurately projecting your cash flow is non-negotiable. Before you even think about talking to a lender, you need to know how to effectively calculate rental income. It's the foundational first step.
This guide will pull back the curtain on the entire funding landscape. We’ll break down why your local bank isn't your only option and how today's market is opening up some fascinating new doors.
Navigating the Modern Lending Landscape
The world of real estate investor financing has never been more interesting. As traditional banks have tightened their belts and become more cautious, they’ve left a huge void in the market. That shift has flung the doors wide open for alternative lenders to step in and play a much bigger role in getting deals done.
This trend is creating what some are calling a "financing gap" of about $150 billion every year in the U.S. and Europe. Private lenders are jumping in to fund projects that big banks might just pass on.
So what does this new environment mean for you? It’s a mix of challenges and incredible advantages. While walking into your bank for a conventional loan might be a bit tougher, you now have access to a much wider array of specialized funding built for specific investor strategies, like:
- Fix-and-flips: These deals demand short-term cash that's based on the property's After Repair Value (ARV), not what it's worth today.
- The BRRRR Method: (Buy, Rehab, Rent, Refinance, Repeat) This popular strategy relies on a sequence of different loan types to work.
- Long-term rentals: For these, you’ll want stable, long-term loans that are focused squarely on the property's monthly cash flow.
Whether you're tackling your first flip or working on scaling a portfolio of rentals, understanding these different avenues gives you the power and confidence to find the right money to make it happen.
Navigating Traditional Financing Routes
Think of traditional financing as the main highway for real estate investors. It’s the most common route, paved by big banks and credit unions, offering the stability of conventional and portfolio loans. It’s a familiar path with established rules and procedures.
This lane is almost always the best fit for buy-and-hold investors who are playing the long game. The goal here is steady, predictable cash flow, and these loans deliver exactly that. You're typically looking at lower interest rates and 30-year fixed terms, which means your core mortgage payment won't change for decades.
But there's a trade-off for all that stability: speed. The application process is notoriously slow and meticulous, which can be a deal-killer when you're up against all-cash offers in a hot market.
The Investor's Underwriting Process
When you bought your own home, the bank obsessed over your personal income. For an investment property? The script gets flipped entirely. The lender’s focus shifts from you to the property’s ability to make money.
This is where you'll hear the term Debt Service Coverage Ratio (DSCR) over and over. Instead of just looking at your W-2, lenders use DSCR to see if the rent a property brings in can easily cover the mortgage and other bills. Most lenders want to see a DSCR of 1.25 or higher, which simply means the property generates 25% more income than it costs to own.
What is DSCR? It’s just Net Operating Income (NOI) divided by your Total Debt Service. In plain English, it answers the lender's number one question: "Can this property pay for itself and still put money in the investor's pocket?"
They’ll still check your personal finances, of course, but the property's potential is what truly drives the decision. This asset-first mindset is the foundation of almost all investor financing.
Typical Requirements for Conventional Investment Loans
Getting a conventional loan for an investment property is a higher bar to clear than for your personal home. Lenders see these as riskier, so they tighten the requirements. You'll need to be ready to show:
- A Strong Credit Score: You might get a primary mortgage with a 620, but for an investment property, you really need to be aiming for 720 or higher. Your score directly impacts your interest rate, and a lower rate means better cash flow.
- A Serious Down Payment: Forget the 3-5% down you see for first-time homebuyers. Investors should expect to bring 20% to 25% of the purchase price to the table. For a $300,000 property, that's a check for $60,000 to $75,000.
- Cash Reserves: Lenders need proof that you can handle a vacancy or a sudden repair without missing a mortgage payment. Plan on showing at least six months worth of the property's total monthly payments (principal, interest, taxes, and insurance) sitting in a liquid account.
- Experience (Sometimes): While not always a deal-breaker, a proven track record as a landlord definitely helps your case. It becomes especially important when you start looking at financing larger multi-unit buildings.
The Current Market for Traditional Loans
The lending world is always in motion. After some turbulence from inflation and rate hikes, the market is starting to find its footing again. We're seeing a rebound in global real estate investment returns, with private property values ticking up for two straight quarters. In this climate, banks have settled into a role of providing "back-leverage," which helps boost returns for investors who bring a good chunk of their own cash to a deal. You can dig deeper into these real estate trends and tactics to get a better feel for the landscape.
What this all means is that while banks are still the go-to for real estate investor financing, they're being picky. They want to see well-qualified borrowers with solid deals that are profitable from day one. To succeed on this path, you need to be prepared, patient, and know exactly what makes a deal look good to a traditional lender.
Exploring Hard Money and Private Money Loans
When a traditional bank loan moves at a snail's pace and your perfect deal is on the line, you need a different kind of tool. Think of hard money and private money loans as the all-terrain vehicles of the real estate investor financing world—built for speed, flexibility, and navigating rough terrain where traditional lenders can't go.
Instead of spending months poring over your personal finances, these lenders cut right to the chase. They're focused on one thing: the quality of the deal itself. It’s the property’s potential that gets the green light, opening doors to opportunities that conventional banks would slam shut.
Hard Money vs. Private Money: What's The Real Difference?
People often toss these terms around like they're the same thing, but knowing the distinction is crucial. It’s like choosing between a specialized tool and a custom-made one.
- Hard Money Lenders: These are established, professional businesses. They have set processes and criteria, and their decision hinges almost entirely on the property as collateral. They live and breathe numbers, especially the After Repair Value (ARV).
- Private Money Lenders: This is all about relationships. Private money comes from individuals—think family, friends, colleagues, or fellow investors—who lend you their own capital. The terms are incredibly flexible, negotiated directly between you and them, and are built on trust.
At its core, a hard money loan is a formal business transaction. A private money loan is a personal agreement. Both get you to the same place: fast cash when the banks say no.
The image below really drives home the choice investors face when deciding between the slow, steady path of a bank and the nimbler route of private lending.
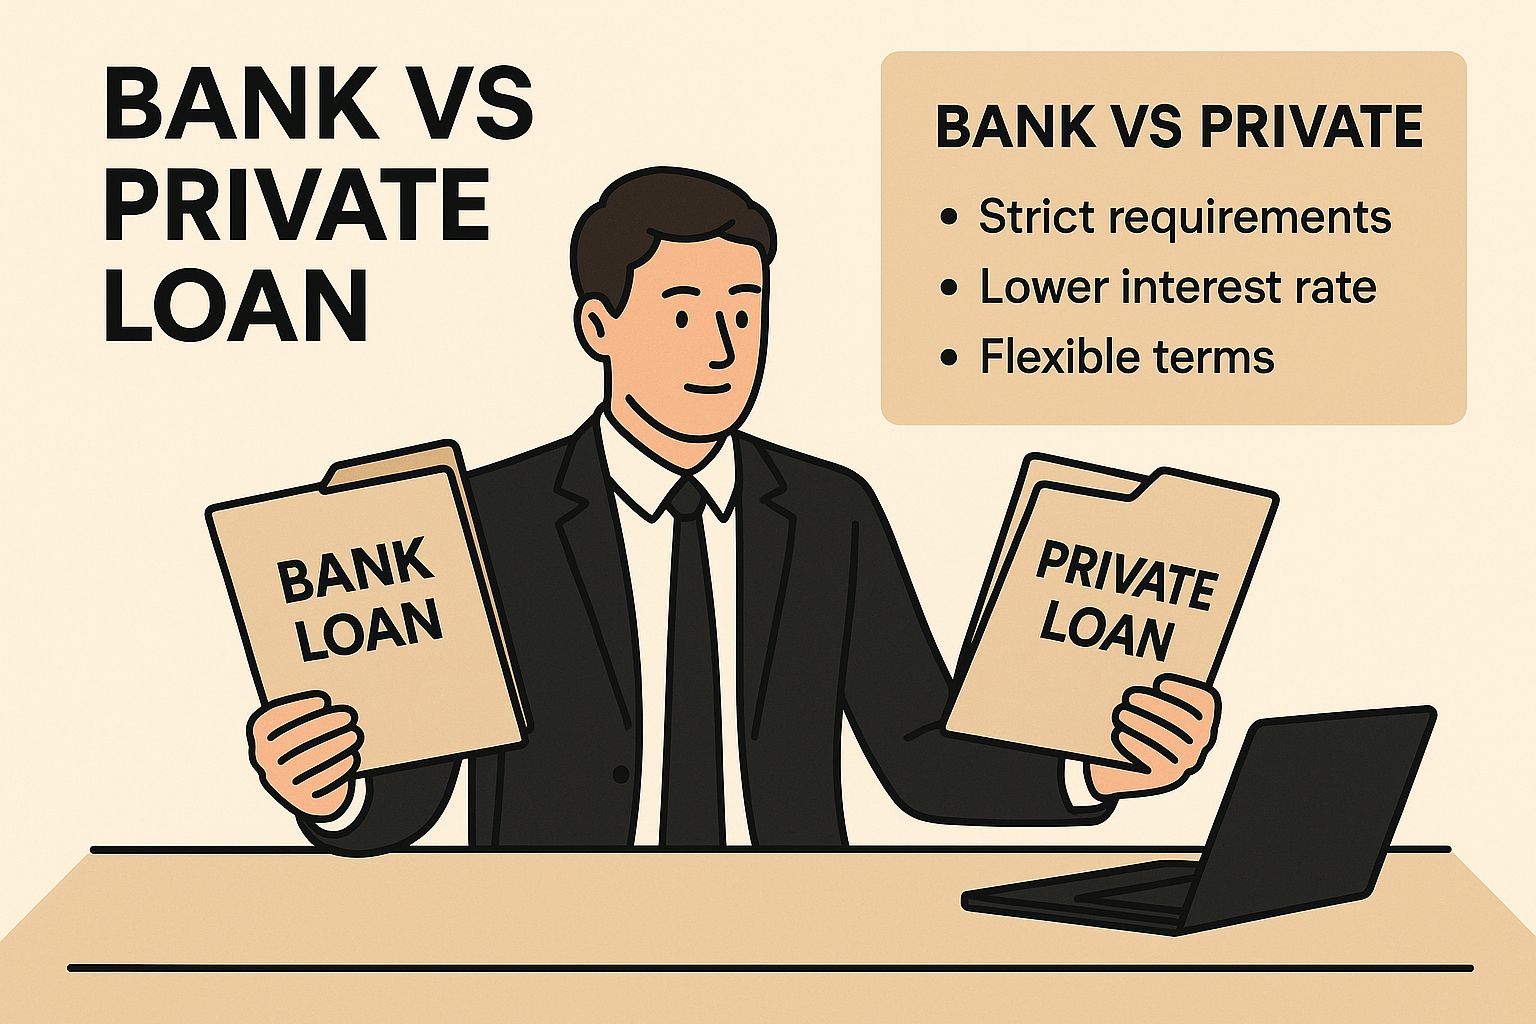
It perfectly illustrates how private financing carves out its own lane by focusing on what a property could be, rather than just what a borrower’s paperwork says today.
How These Asset-Based Loans Work
Forget everything you know about traditional mortgage applications. The underwriting for hard and private money is a completely different world. They aren't interested in your tax returns from three years ago; they want to know about the asset.
Their approval is almost entirely based on the property. For a house flipper, this is a total game-changer. The lender isn't just looking at the home's sad, current state—they’re basing the loan on its future, renovated value.
The Power of ARV: Lenders will typically front 65% to 75% of a property’s After Repair Value. Let's say you find a fixer-upper for $200,000 that you know will be worth $350,000 once you're done. A hard money lender might offer you up to $262,500, which could cover your entire purchase and renovation budget.
This ARV-based model is the secret sauce. It’s what makes these loans the undisputed champion for any project where you're adding value and transforming a property.
To help you see how these options stack up, here’s a quick side-by-side comparison.
Comparing Real Estate Investor Financing Options
This table breaks down the key differences between traditional, hard money, and private money loans, so you can quickly see which one aligns with your specific deal and timeline.
| Financing Type | Best For | Approval Basis | Typical Speed | Interest Rates |
|---|---|---|---|---|
| Traditional Bank Loan | Owner-occupied homes, stable rental properties, long-term holds | Borrower's credit, income, and DTI | 30-60+ days | Lowest |
| Hard Money Loan | Fix-and-flips, BRRRR projects, quick closes | Property's After Repair Value (ARV) | 7-14 days | High (10-15%+) |
| Private Money Loan | Any deal where speed & flexibility are key; relationship-based | The deal itself & your relationship with the lender | Highly variable, can be very fast | Negotiable |
As you can see, the right choice really depends on your strategy. Are you playing the long game with a stable rental, or do you need to move fast on a flip? Your answer will point you to the right column.
The Cost of Speed and Flexibility
Of course, this kind of speed and convenience isn't free. Hard and private money loans are more expensive than a conventional mortgage, and you absolutely have to factor these costs into your deal analysis.
Key Loan Terms To Expect
- Higher Interest Rates: While a bank might offer you a loan in the 6-8% range, hard money rates typically start around 10% and can climb to 15% or more.
- Origination Points: These are upfront fees charged by the lender. One "point" is equal to one percent of the loan amount, and it's common to see fees between 2 and 5 points.
- Short Loan Terms: These aren't 30-year mortgages. They are short-term solutions, with terms usually running from just six months to two years.
The expectation is crystal clear: get in, add value, and get out. You’ll either sell the property for a profit or refinance into a more stable, long-term loan.
When To Use Hard and Private Money
These are specialized tools, not everyday solutions. You pull them out of the toolbox for specific jobs where their benefits crush their costs.
Consider this type of real estate investor financing when you're:
- Flipping a House: It's the perfect vehicle for buying a distressed property, funding the rehab, and selling it for a profit, all within a year.
- Facing a Quick Close: When you need to close in 7-14 days to beat out cash offers, a bank's 45-day timeline just won't cut it.
- Securing a BRRRR Deal: It's the ideal funding for the "Buy" and "Rehab" stages before you move to the "Refinance" step with a traditional lender.
- Lacking Conventional Qualifications: If your credit is shaky or your income is hard to document, but you’ve found an undeniable grand-slam deal, an asset-based loan gets you in the game.
Ultimately, hard and private money are about strategic leverage. They give you the power to jump on opportunities that would otherwise pass you by, making them an essential part of any serious investor's financing arsenal.
Unlocking Creative Real Estate Financing Strategies
What if you could snag a profitable investment property without ever stepping foot inside a bank? That’s the reality in the world of creative real estate investor financing, a space where the structure of the deal is just as critical as the property itself. It's all about crafting win-win situations that neatly sidestep traditional lenders.
These strategies are your ticket to negotiating terms directly, opening the door to flexible solutions built around a specific property and a seller's unique needs. While a conventional loan has a strict, one-size-fits-all script, creative financing is more like improv—it takes clever thinking, sharp negotiation skills, and a genuine understanding of what the other person wants.
For investors, this unlocks a whole new world of potential deals. You'll find properties that banks wouldn't touch or sellers who just want a simple, fast closing more than they want top dollar.
Embracing Seller Financing
Imagine this: you find the perfect property, but instead of going to a bank, the owner becomes your lender. That's the simple genius behind seller financing, often called an owner-carry deal. The seller extends you a loan, and you make your monthly payments straight to them.
This can be an incredibly powerful tool. You get to negotiate everything directly with the seller—the interest rate, how much you put down, even the length of the loan. It's a lifesaver for properties that need some work or for buyers who don't quite fit into the neat little box that traditional lenders require.
Here’s a real-world example: A retiring landlord owns a rental property outright. Instead of a big, taxable lump sum, he’d rather have a steady income stream for his retirement years. You agree on a price, he "carries the note," and you send him a check every month. It’s a classic win-win scenario.
Seller financing is all about solving the seller's problem. When you figure out their motivation, you can structure a deal that works for everyone, landing you a property with terms a bank would never dream of offering.
Acquiring Property with Subject-To Deals
Another fantastic technique is buying a property "subject to" its existing mortgage. In short, you take ownership of the house and start making the monthly payments on the seller's loan, even though the loan officially stays in their name.
Why on earth would a seller agree to that? Usually, it's a lifeline for someone in a tough spot, like facing foreclosure. They need to get out from under the payments fast. This way, they can walk away with their credit intact, and you get into a property without the hassle of securing a new loan.
The real beauty here is that you can often lock in the amazing loan terms the seller got years ago, like a super-low interest rate you just can't find in today's market.
- You get the deed: The property is legally yours.
- The loan stays put: The original mortgage remains in the seller’s name.
- You take over payments: It’s now your job to make the monthly mortgage payments to the lender.
Subject-to deals are built on a mountain of trust and require rock-solid legal paperwork to protect both you and the seller. This isn't a beginner's move, and talking to a real estate attorney is absolutely non-negotiable.
Leveraging Lease Options for Control
A lease option, also known as a rent-to-own agreement, is a smart hybrid strategy. It's part rental lease, part purchase contract. This gives you a fantastic way to control a property right now with the option to own it down the road.
Here’s a breakdown of how it works:
- The Lease Agreement: First, you agree to rent the property for a specific amount of time, just like any other tenant.
- The Option to Buy: You'll pay an upfront "option fee." This gives you the exclusive right to buy the house at a pre-agreed price before your lease is up.
- Rent Credits: In many deals, a piece of your monthly rent gets set aside and credited toward your down payment if you decide to buy.
This strategy gives you breathing room. You have time to work on your credit, save up a bigger down payment, or simply wait for the home's value to go up before you pull the trigger. For sellers, it means instant rental income and a potential buyer already living in their house. Many savvy investors use this to lock down promising investment homes in up-and-coming areas. To get a broader view of non-traditional routes, looking into options like Smart Vendor Finance can also open doors to flexible real estate solutions.
Financing Emerging Real Estate Asset Classes
The world of real estate investing is stretching far beyond apartments and single-family homes. A new wave of high-growth, alternative assets is catching the eye of savvy investors, opening up some really exciting opportunities in specialized sectors.
We're talking about properties like data centers, self-storage facilities, life science labs, and specialized senior healthcare properties. These aren't just buildings; they're critical infrastructure and active businesses housed within four walls. That one distinction changes the entire game when it comes to securing real estate investor financing.
Your typical bank often gets cold feet when faced with these asset classes. Their underwriting models are built for simple property comparisons, which just don't work for a high-tech data center or a bustling self-storage business. This is where specialized private lenders are stepping in to fill a massive gap in the market.
A New Approach to Underwriting
When a lender looks at an office building, they pull comps—comparable sales and rental rates in the area. Simple enough. But how do you find comps for a cold-storage facility or a telecommunications tower? The short answer is, you don’t, at least not in the traditional way.
Lenders who get into financing these emerging assets have to completely shift their focus. They look past the physical property and zoom in on the operational success of the business inside. In reality, they act more like business lenders, crunching a totally different set of numbers to figure out the risk and potential.
- Market Demand: Is there a strong, growing demand for data storage or specialized medical services right here in this region?
- Operational Cash Flow: Is the business actually profitable? Lenders will want to see income statements and balance sheets that prove the operation is stable.
- Tenant Quality and Contracts: For assets like cell towers or data centers, having long-term contracts with major corporations is a huge green flag.
- Specialized Management: Does the investment team have a proven track record running this exact type of asset? Experience is everything.
This business-first approach demands a much deeper level of industry knowledge, which is why a small, dedicated group of niche lenders really dominates this space.
Why Alternative Lenders Excel Here
The unique nature of these properties makes them a perfect match for private and specialized debt funds. They have the flexibility and expertise that big, bureaucratic banks just can't offer. They can build custom-tailored loan structures that actually make sense for the business's specific operational model.
And this trend is only going to pick up speed. Forecasts show that through 2034, alternative property types like data centers and healthcare facilities are expected to grow in value at a compound annual rate of around 15%. This kind of rapid expansion absolutely requires creative financing from capital providers who understand these less mature and highly specialized assets. You can learn more about the future of alternative property investing here.
The key takeaway for investors is that financing these assets is less about the property's appraised value and more about presenting a compelling business case supported by strong market data and a solid operational plan.
To successfully land a loan, you have to show that you're not just buying a building—you're investing in a thriving, in-demand business. As these sectors continue to boom, knowing how to navigate this specialized financing landscape will be a major advantage for any forward-thinking investor.
How to Secure Your First Investment Loan
Turning your real estate goals from a dream on a spreadsheet into a closed deal comes down to having a rock-solid plan. Getting that first loan isn't just about having a great credit score; it's about putting together a professional package that shows lenders you’re a serious partner, not just a speculator.
Think of it this way: Lenders hate risk. Your number one job is to squash every single doubt they might have by proving you’ve done your homework and know your numbers inside and out. This preparation is what separates the pros who get funded again and again from the amateurs who can’t get off the ground.
Building Your Credibility Package
Before you even pick up the phone to call a lender, you need to get your "credibility package" in order. This is just a collection of documents that tells your complete financial story and proves the deal you’ve found is a smart one. A clean, organized package screams professionalism and makes the underwriter’s job a whole lot easier—which always, always works in your favor.
Your package really has two main parts: documents that prove who you are financially, and documents that analyze the specific deal.
The goal here is to anticipate every question a lender might ask and have the answer ready before they even think to ask it. A complete and organized file shows you're a serious professional who respects their time and process.
This proactive approach builds a ton of credibility, especially when you're just starting out.
The Essential Document Checklist
Getting these documents together ahead of time saves you from that last-minute panic and keeps the whole process moving smoothly. While every lender has slightly different requirements, this checklist covers the basics you'll almost certainly need.
Personal Financials:
- Tax Returns: You’ll need your last two years of personal and business returns.
- Bank Statements: Have two to three months of statements ready for all your checking, savings, and investment accounts.
- Pay Stubs: The most recent 30 days of pay stubs to verify your income.
- Personal Financial Statement: This is basically a snapshot of your assets and liabilities.
Property & Deal Specifics:
- Purchase Agreement: The signed contract to buy the property.
- Project Budget: A detailed breakdown of all your numbers—purchase price, rehab costs, closing fees, and holding costs.
- Scope of Work (SOW): If it's a rehab project, this is your line-by-line list of every single repair and improvement you plan to make.
- Comparable Market Analysis (CMA): An analysis of recent sales and rental comps that justifies your projected after-repair value (ARV). A great place to start is by using a solid rental property value estimator to make sure your projections are grounded in real-world data.
Presenting Yourself as a Reliable Partner
Once your documents are in order, it's time to present your case. Remember, lenders are funding you as much as they're funding the property. You need to clearly explain your investment strategy, show them exactly how this deal fits into that strategy, and walk them through your numbers with confidence.
Show them you’ve planned for the unexpected by having enough cash reserves. If you're new to the game, highlight skills from your career that carry over or mention any mentors you're working with. By presenting a professional, well-thought-out plan, you're not just asking for money—you're proving you're a low-risk, high-potential partner worthy of their capital. This foundation is absolutely key to securing real estate investor financing.
Frequently Asked Questions
When you're navigating the world of real estate investor financing, a lot of questions come up. It doesn't matter if you're just starting out or have been at this for years; getting clear answers to these common sticking points is key to making smarter, more confident moves with your portfolio.
Let's dive into some of the most common questions investors ask.
What Is the Difference Between a DSCR Loan and a Conventional Loan
The easiest way to think about it is that these two loans speak completely different languages. A conventional loan is all about your personal financial story. It wants to know about your job, your income, and how much personal debt you're carrying. Your debt-to-income (DTI) ratio is its North Star.
A DSCR (Debt Service Coverage Ratio) loan, on the other hand, only cares about the property's story. It's almost entirely focused on one question: can this investment generate enough rent to cover its own mortgage? For investors who want to scale, DSCR loans are a game-changer because they don't touch your personal DTI, freeing you up to buy more properties.
Can I Get Real Estate Investor Financing with a Bad Credit Score
Yes, you definitely can—you just have to look beyond the big banks. While a low credit score is usually a deal-breaker for a conventional loan, alternative lenders play by a different set of rules.
- Hard Money Lenders: These folks are focused on the asset. They care about the property's value, especially its After Repair Value (ARV), not your credit past. If the deal is good enough, you can get funding, though you should expect to pay higher rates.
- Private Money Lenders: These are often people in your own network who are funding both you and the deal. If they believe in your vision and the numbers pencil out, a credit score suddenly becomes far less important.
How Many Investment Properties Can I Finance at Once
This really boils down to what kind of loan you're using. If you go the conventional route with Fannie Mae or Freddie Mac, you're generally going to hit a ceiling at 10 financed properties, and that includes your own home.
But when you step into the world of commercial and alternative financing, there is no hard limit. Portfolio lenders, private lenders, and hard money lenders will keep funding your deals as long as each one is profitable and you've built a solid track record with them.
That kind of flexibility is exactly what investors need when they plan to grow beyond just a few doors. Just remember, managing the finances for a growing portfolio gets complicated fast. It's a smart move to get a handle on how to prepare for tax season when you own a rental so you can keep your books clean from day one.
At Edinhart Realty and Property Management, we help investors maximize their returns through expert property management and real estate services. Whether you're buying your first rental or optimizing a large portfolio, our team has the local expertise to guide you. Learn how we can support your investment journey at https://edinhart.com.


