

At its core, an investment home is a property you buy not to live in, but to generate income and build your wealth. Forget thinking about it like buying your own house. It's more like acquiring a financial asset—an engine you can fine-tune for long-term profit through rent and rising market values.
What Is An Investment Home, Really?
Let's look past the simple definition. An investment property isn't just four walls and a roof; it's a dynamic asset you put to work for you. One of the best ways I've found to explain this is to think of it like planting a "money tree."
For this tree to grow, it needs the right environment. That means fertile soil (a strong local real estate market), a healthy seed (your down payment and initial investment), and regular care (smart property management). When you get those things right, your tree produces two very different, but equally important, types of fruit.
The Two Core Ways You Make Money
First, you get a regular harvest in the form of cash flow. This is the pure profit left in your pocket each month after you’ve collected rent and paid all the property's bills—the mortgage, taxes, insurance, and any repair costs. For a real estate investment to be truly successful, you need that consistent positive cash flow.
Second, the tree itself gets bigger and more valuable. This is appreciation, the increase in your property's market value over the years. While cash flow helps you pay the bills today, appreciation is what builds serious, long-term wealth. You can dive deeper into these strategies by reading about why buying single-family homes can be a good investment.
The real magic happens when you combine these two forces. You use the steady rental income to cover all your costs and turn a profit, all while the property itself is quietly becoming more and more valuable.
Why Real Estate Is Still A Go-To Asset
There’s a reason real estate has been a cornerstone of wealth-building for generations: it’s a tangible asset. You can literally see it, touch it, and stand on it. Unlike a stock certificate that can feel abstract and volatile, property offers a real sense of security and utility.
We see this resilience in the numbers, even when the world feels uncertain. For instance, global real estate investment volume jumped to roughly US$185 billion in the first quarter of a recent year, marking a 34% increase from the year before. That kind of growth, happening amidst global unpredictability, shows just how much confidence seasoned investors have in property.
Seeing a house as a dynamic tool for creating wealth is the first, most important step. In this guide, we'll walk through exactly how to find, finance, and manage your own investment properties, helping you turn this powerful idea into a profitable reality.
Finding Your First Investment Property
Feeling like you're drowning in a sea of online property listings? You’re not alone. The sheer volume can feel paralyzing, but finding a great investment home isn't about scrolling until your eyes glaze over. It's about becoming a "neighborhood detective"—learning to spot markets with real, sustainable potential for growth.
Smart investors know to ignore the national headlines and focus on local fundamentals. They look for tangible signs that a specific area is on an upward swing. These are the green shoots that signal a healthy rental market long before everyone else catches on.
Uncovering Local Market Strength
Think local, local, local. A great investment property is always located where people want—and can afford—to live. You're hunting for signs of a healthy local economy and clear community investment.
Here are the key indicators to investigate:
- Job Growth: Are new companies moving into town? Are the big local employers hiring? A strong job market is a magnet for new residents, and those people will all need a place to live.
- Population Shifts: Is the population actually growing? Check out local census data or city planning reports to see where the trends are headed.
- New Infrastructure: Keep an eye out for new schools, hospitals, public transit lines, or major road projects. This kind of development is a powerful signal of future appreciation and growth.
Understanding these bigger trends is crucial. Even when global real estate markets seem shaky, local pockets of opportunity always exist. For instance, recent data showed global transaction volumes dipped by 2% year-over-year in one quarter, with the Americas showing growth while other regions declined. High-level shifts like this just underscore why focusing on resilient local markets is your best bet. You can dive deeper into these global real estate patterns at UBS.com.
To help you get started, here's a breakdown of the key metrics to look for when you're analyzing a potential market.
Key Market Analysis Indicators for Investment Homes
| Indicator | What to Look For | Why It Matters for Your Investment |
|---|---|---|
| Job Growth Rate | A rate higher than the national average; diverse industries are a plus. | More jobs mean more tenants and higher demand for rentals, reducing your vacancy risk. |
| Population Growth | Consistent, positive year-over-year growth. | A growing population directly translates to increased housing demand and potential for appreciation. |
| Median Household Income | A rising median income that can comfortably cover average local rents. | Ensures your target tenants can afford rent increases, supporting your cash flow over time. |
| New Construction Permits | A steady, but not excessive, number of new building permits. | Shows confidence from developers but watch for overbuilding, which can create a glut of supply. |
| School Ratings | High-performing or improving public schools. | Good schools attract families, who are often stable, long-term tenants. |
Putting in the work to research these factors is what separates successful investors from the rest. It gives you a solid foundation before you even start looking at individual properties.
Using Quick Rules To Filter Opportunities
Once you’ve zeroed in on a promising neighborhood, you need a quick way to sift through dozens of listings. This is where simple rules of thumb are your best friend. They aren't a replacement for a deep financial analysis, but they're fantastic for tossing out the duds quickly.
The 1% Rule is a classic first-pass filter. It's simple: a property's gross monthly rent should be at least 1% of the purchase price. So, for a $200,000 home, you'd want it to rent for at least $2,000 a month. If it doesn't even come close, it's probably not worth a second look.
This back-of-the-napkin math immediately tells you if a property's potential income is in the right ballpark for its price. It’s a time-saver that lets you focus your energy on the deals that actually have a chance.
Digging Deeper With Key Metrics
After you've used the 1% Rule to create a shortlist, it’s time to get a little more serious. You'll move from quick estimates to more solid calculations that paint a much clearer financial picture.
One of the most useful tools for this next stage is the Gross Rent Multiplier (GRM). This metric helps you compare the relative value of similar properties in the same area.
GRM = Property Price / Gross Annual Rent
Let's say two similar duplexes are for sale down the street from each other. Duplex A costs $300,000 and brings in $30,000 in rent each year (GRM of 10). Duplex B is listed at $320,000 but generates $35,000 in annual rent (GRM of 9.14). At first glance, Duplex B offers more rental income for the price, making it the better value.
By combining broad market analysis with these practical filters and metrics, you can turn a confusing flood of listings into a manageable list of real contenders. This methodical process moves you from being a passive house-hunter to a strategic investor ready to spot a genuine hidden gem.
How to Secure Financing for Your Investment
For most aspiring investors, figuring out how to pay for an investment property feels like the biggest roadblock. It's a common fear, but the truth is, there are more ways to secure funding than you might realize. Let's walk through the most common paths to get the capital you need to make your move.
The most straightforward option is a conventional mortgage, which works a lot like the loan you’d get for your own home. The key difference? Lenders view an investment property as a higher risk. They know that if financial hardship strikes, a borrower is more likely to default on a rental property mortgage than their primary residence.
To balance out that risk, banks almost always require more skin in the game. You should be prepared for a down payment in the 20% to 25% range.
Looking Beyond Conventional Loans
While a standard mortgage is a great tool, it’s not your only choice. Understanding the alternatives can open up doors to deals you might have otherwise passed on.
- FHA Loans: These government-backed loans are typically for owner-occupants, but there's a fantastic loophole for investors. You can use an FHA loan to buy a multi-unit property (up to four units) as long as you live in one of them. This strategy, often called "house hacking," allows you to get in the game with a down payment as low as 3.5%.
- Portfolio Loans: If your goal is to build a small empire of rentals, a portfolio loan is your friend. These are specialized loans that consider the cash flow of your entire real estate portfolio, not just your personal W-2 income. They’re perfect for scaling.
- Private and Hard Money Lenders: When a great deal pops up and you need to act fast, traditional banks can be too slow. This is where private and hard money lenders shine. Their rates are higher, but they can fund a deal in days, not weeks, making them ideal for fix-and-flip projects or nabbing a competitive property.
The BRRRR Method: A Wealth-Building Engine
One of the most powerful strategies for growing your portfolio without tying up all your cash is the BRRRR method. It’s a five-step system for recycling your initial investment over and over again.
BRRRR stands for: Buy, Rehab, Rent, Refinance, Repeat.
Here's how it works. You Buy a property that needs work, usually under market value and often with a short-term loan. Then, you Rehab it, forcing appreciation by making smart improvements that increase its value.
Once the renovation is complete, you Rent it out to a qualified tenant, establishing a consistent income stream. Now for the magic step: you go to a bank and Refinance the loan based on the property’s new, higher value. This allows you to pull your original cash back out, tax-free.
Finally, you take that capital and Repeat the process on the next property. The BRRRR method is a true financial engine, turning one pot of money into a growing collection of cash-flowing assets.
No matter which financing route you take, preparation is key. Getting your financial paperwork in order ahead of time will make the entire experience smoother and less stressful. Start by familiarizing yourself with what documents are needed for a mortgage to ensure you're ready when the right opportunity comes along.
Doing Your Homework: A Guide to Pre-Purchase Due Diligence
https://www.youtube.com/embed/vExObr24lMo
Alright, let's talk about the single most important step before you sign on the dotted line: due diligence. Think of it as your x-ray vision for an investment. It’s the deep-dive investigation that uncovers the costly problems hiding just beneath the surface.
Honestly, skipping this homework is the fastest way I've seen an investor turn a promising deal into a financial sinkhole. This isn't just a quick walkthrough. It's real detective work, separating the pros from the people who just get lucky. Your mission is to verify every claim, challenge your own assumptions, and protect your hard-earned capital from any nasty surprises.
How to Read a Home Inspection Report (Without Getting Overwhelmed)
The professional home inspection is the bedrock of your due diligence. But then you get this 40-page report, and it’s easy to feel overwhelmed by all the technical jargon and photos. The trick is knowing how to cut through the noise.
Don’t get sidetracked by chipped paint or a sticky doorknob. You need to zoom in on the big-ticket items—the systems that can absolutely drain your bank account if they fail.
Here’s what I always focus on first:
- Foundation and Structure: Any talk of major cracks, water in the basement, or floors that feel like you're walking on a funhouse ramp is a major red flag. These aren't small fixes; they can run into the tens of thousands.
- The Roof: A good inspector will estimate the roof's remaining lifespan. If it only has a year or two left, you're looking at a huge expense right out of the gate. You have to factor that into your numbers.
- Electrical System: Watch out for old-school wiring (like knob-and-tube) or an ancient electrical panel. These aren't just inconvenient; they can be serious fire hazards and often need a complete, and costly, upgrade.
- Plumbing: Leaky pipes and low water pressure are common finds. It's smart to know exactly which plumbing features to check before you buy a new home so you aren't blindsided by plumbing bills the month after you close.
Look, a perfectly clean inspection report is a unicorn. It basically doesn't exist. Your job isn't to find a flawless property, but to understand its flaws. Use the report as leverage—to negotiate a better price, get the seller to make repairs, or simply walk away if the risk is too high.
Untangling the Legal and Financial Knots
Beyond the bricks and mortar, you have to dig into the property’s legal and financial standing. Missing these details can trap you in legal battles, unexpected fines, or rules that prevent you from even renting the place out.
Zoning, Covenants, and HOAs
First, confirm the zoning. Is it actually zoned as a multi-family, or was a previous owner just renting out the basement illegally? Then, check for neighborhood covenants or Homeowner Association (HOA) rules. The last thing you want is to buy a home for short-term rentals only to discover the HOA has banned them entirely.
Property Tax Surprises
Next, pull the property tax records. Verify what the current owner pays, but more importantly, find out if the tax will be reassessed after you buy it. In many areas, the sale triggers a reassessment to the new purchase price, and a sudden tax hike can completely torpedo your cash flow projections.
Finally, and this is 100% non-negotiable, you must get a title search. This process confirms the seller is the true legal owner and that there are no hidden claims or liens on the property. A clean title is your proof of ownership, the final shield that protects the asset you've worked so hard to find and fund.
Calculating Your Real Profit from Investment Homes
That monthly rent check hitting your account feels great, but it's just the tip of the iceberg. Relying on gross rent alone is a classic rookie mistake—it’s a vanity metric that can mask the true performance of your investment home. To really know if your property is a financial winner or a slow-motion money pit, you have to get honest about the net profit.
This means looking past the exciting top-line number and accounting for every single dollar the property costs you. Only then can you see the full financial picture. Let's walk through the essential calculations that separate the savvy investors from those who are just guessing.
The Foundation: Your Monthly Cash Flow
Cash flow is the lifeblood of a rental property. It’s the actual money left over at the end of the month after you’ve collected all the rent and paid all the bills. Positive cash flow means the property is not only paying for itself but also putting money back into your pocket.
The basic formula is simple enough:
Monthly Cash Flow = Total Rental Income – Total Monthly Expenses
But the real work is in figuring out your “Total Monthly Expenses.” It’s so much more than just the mortgage.
Here’s a more realistic breakdown of what you need to budget for:
- Mortgage Principal & Interest: Your main loan payment.
- Property Taxes: Usually paid into an escrow account monthly.
- Homeowners Insurance: Essential protection for your asset.
- Vacancy Fund (5-10% of rent): You have to save for months when the property sits empty. It will happen.
- Maintenance & Repairs (5-10% of rent): For everything from a leaky faucet to a broken appliance.
- Capital Expenditures (CapEx) (5-10% of rent): For the big-ticket items down the road, like a new roof or HVAC system.
- Property Management Fees (8-12% of rent): If you hire a pro to handle the day-to-day.
Forgetting to budget for vacancy, repairs, and CapEx is where so many new investors stumble. These aren't "if" expenses; they are "when" expenses.
Measuring Your Return: The Cash-on-Cash Return
Once you've confirmed your property is generating positive cash flow, the next question is: how hard is your invested cash actually working for you? This is where the Cash-on-Cash Return comes in. It tells you the annual return you're getting on the actual cash you pulled out of your pocket to buy the property.
Think of it this way: if you put $50,000 of your money into a stock and it paid you $5,000 in dividends that year, your return is 10%. Cash-on-Cash Return applies that same, simple logic to your investment home.
The formula looks like this:
Cash-on-Cash Return = (Annual Cash Flow / Total Cash Invested) x 100
"Total Cash Invested" includes your down payment, all your closing costs, and any cash you spent on immediate repairs to get the place rent-ready. A higher Cash-on-Cash Return is a clear sign that you're getting more profit for every dollar you've put in. It’s an fantastic metric for comparing different properties side-by-side.
Valuing Property Like a Pro: The Capitalization Rate
Finally, let’s talk about the Capitalization Rate, or Cap Rate. This metric helps you understand a property's profitability relative to its market price, completely independent of your personal financing. It’s a way to measure the potential return as if you had bought the property with all cash.
Cap Rate = (Net Operating Income / Property Purchase Price) x 100
Your Net Operating Income (NOI) is your annual rental income minus all operating expenses except for your mortgage payment. The Cap Rate is a powerful tool used by commercial investors to quickly size up income-producing properties. Generally, a higher cap rate suggests a higher potential return (and often, a bit more risk).
To see how these numbers come together, let's look at a hypothetical property.
Calculating Profitability for a Sample Investment Home
| Financial Metric | Calculation/Formula | Example Value |
|---|---|---|
| Purchase Price | N/A | $300,000 |
| Total Cash Invested | Down Payment (20%) + Closing Costs | $65,000 |
| Gross Annual Rent | Monthly Rent ($2,500) x 12 | $30,000 |
| Net Operating Income (NOI) | Gross Rent – (Taxes + Insurance + Vacancy + Repairs) | $18,000 |
| Annual Cash Flow | NOI – Annual Mortgage Payments | $6,000 |
| Cash-on-Cash Return | (Annual Cash Flow / Total Cash Invested) x 100 | 9.23% |
| Capitalization (Cap) Rate | (NOI / Purchase Price) x 100 | 6.0% |
This table shows how you move from basic rent to the metrics that truly matter. It’s this level of detail that empowers you to make smart, data-driven decisions.
One often overlooked aspect of your real profit is tapping into tax benefits. To see how this can boost your bottom line, check out this guide to maximizing your short-term rental tax deductions.
Mastering these numbers can feel like a lot at first, which is why a dedicated tool can be a game-changer. For a simple way to run these scenarios, this https://edinhart.com/rental-property-roi-calculator/ is incredibly helpful. By digging into these metrics, you shift from being a hopeful landlord to a strategic investor who builds wealth based on data, not just a gut feeling.
Avoiding Common First-Time Investor Mistakes
One of the smartest things you can do when getting into investment homes is to learn from the expensive lessons others have already paid for. The road to a successful portfolio is paved with potential pitfalls that can quickly sour what looks like a great deal. If you know what these traps are ahead of time, you can build a much stronger strategy right from the start.
Probably the biggest blunder I see is investors underestimating the true cost of ownership. It's easy to get tunnel vision, focusing only on the purchase price and potential rent. But what about the new HVAC system you'll need in five years? Or the roof replacement that's looming in ten? These aren't just possibilities; they are eventual certainties that you must budget for.
Another classic error is buying with your heart instead of your calculator. It’s natural to fall in love with a property’s charm, but successful real estate investing is a numbers game, plain and simple. An emotional purchase almost always means you’ve overlooked something critical, like sky-high property taxes, a neighborhood that's slowly declining, or a quirky floor plan that renters in that area just don't like.
Sidestepping Financial and Logistical Traps
Beyond the property itself, there are plenty of financial missteps that can sink your investment before it even has a chance to float. Taking on too much debt too quickly—being over-leveraged—is a common one. It might seem like a good way to grow fast, but it leaves you with zero wiggle room. Just one unexpected vacancy or major repair bill can completely wipe out your cash flow.
Likewise, ignoring the reality of the local market is a recipe for disaster. A classic example is failing to factor in a typical 3-5% vacancy rate into your calculations. That's like planning your personal budget assuming you'll never get sick or have an unexpected car problem. A realistic plan always accounts for those inevitable gaps between tenants.
To avoid these problems, you need to follow a clear, logical process. This infographic lays out the basic workflow you should follow when looking for investment homes.
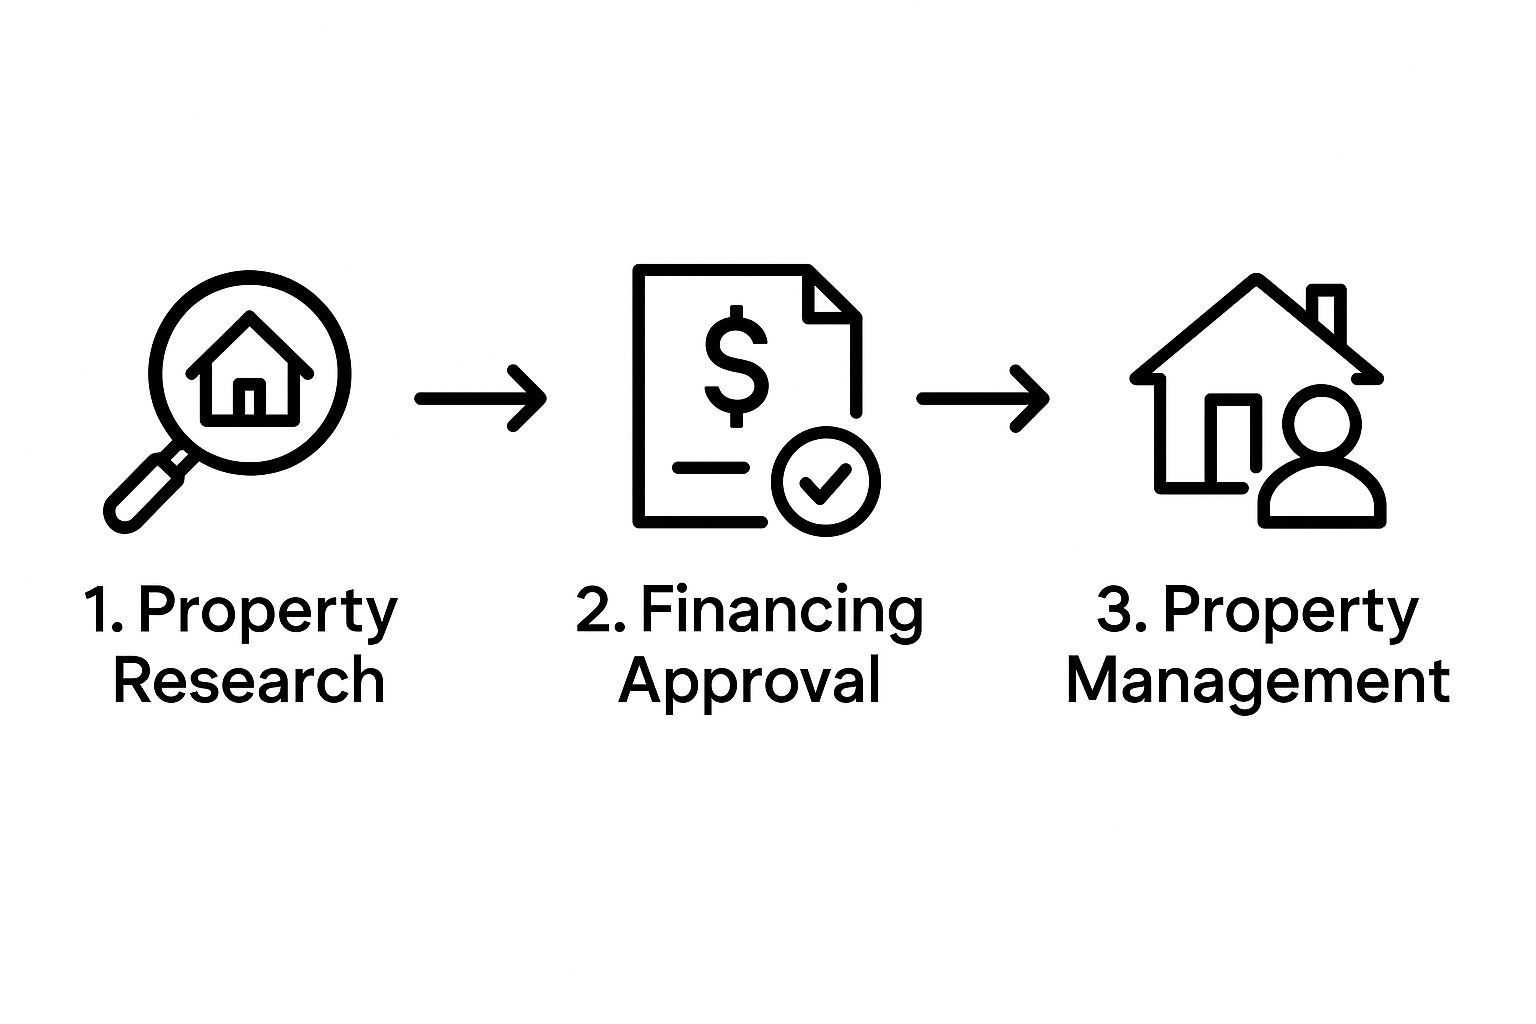
As you can see, successful investing isn't a single action but a sequence of distinct stages. Each one demands your full attention before you can confidently move on to the next.
The most critical lesson is this: treat your investment like a business from day one. That means keeping meticulous records, building up cash reserves, and having a data-driven reason for every single decision you make.
Finally, a lot of new investors simply aren't ready for the administrative side of being a landlord. This covers everything from solid lease agreements to proper financial statements. For some great advice on getting organized, you can learn how to prepare for tax season when you own a rental and make sure you’re staying compliant while maximizing your returns.
By sidestepping these common mistakes, you’ll be laying a solid foundation for a successful, long-term real estate venture.
Your Questions About Investment Homes Answered
It's one thing to read about real estate investing, but it's another thing entirely to actually do it. When you're ready to make a move, a lot of practical questions naturally start bubbling up. Let's walk through some of the most common ones that new investors ask.
How Much Cash Do I Really Need?
This is always the first question, and for good reason. While you’ve probably heard about the standard 20-25% down payment for an investment property loan, that's just the starting line.
Don't forget to factor in closing costs, which typically run another 2-5% of the home's purchase price. On top of that, you absolutely need a cash reserve for immediate repairs and updates. You want the property to be move-in ready for your first tenant, and you can't rely on day-one rental income to cover those initial fixes.
Do I Need an LLC for My Rental Property?
The question of legal structure comes up a lot. Should you create a Limited Liability Company (LLC) for your investment home? For your very first property, it might not be necessary, but it's a smart strategy to consider as you grow.
Think of an LLC as a protective wall. It separates your personal finances (like your family home and savings) from your investment business. If a lawsuit ever arises related to your rental, the LLC helps shield your personal assets, limiting your risk to the assets owned by the company itself.
Should I Buy a Single-Family or Multi-Family Home?
This is a classic crossroads for new investors, and there's no single right answer—it depends on your goals.
Single-Family Homes: These are often the simpler choice. Management is more straightforward, and when you eventually sell, you'll have a huge pool of potential buyers (not just other investors). They also tend to attract families who stay longer and often treat the home as if it were their own.
Multi-Family Properties: The big draw here is scaled-up cash flow. With multiple units under one roof, you get several streams of income. This also means a single vacancy won't wipe out your entire monthly revenue. The trade-off? More tenants often means more management headaches.
What Are the Key Tax Benefits?
Taxes are where real estate investing truly shines, and it’s a huge motivator for many. Two of the most powerful tax advantages are interest deductions and depreciation.
You get to deduct the mortgage interest you pay each year, which directly lowers your taxable income. But the real game-changer is depreciation. The IRS lets you write off the value of the building (but not the land) over 27.5 years. This creates a substantial "paper loss" that can offset your rental profits, even when the property is putting cash in your pocket every month.
These aren't just minor perks; they are fundamental benefits that can dramatically boost your bottom line and make investment homes an incredibly effective tool for building wealth.
Navigating these decisions is always easier with an experienced partner. At Edinhart Realty and Property Management, we specialize in helping investors maximize their returns with expert guidance and property management. Learn more about how we support your investment journey.


