

If you're looking at buying a home in California right now, you’ve probably noticed that interest rates are a hot topic. They're currently hovering in the mid-to-high 6% range for a typical 30-year fixed loan, which is a big change from the rock-bottom rates we saw just a few years ago.
This number is more than just a percentage; it's the key that determines your monthly mortgage payment and, ultimately, how much home you can truly afford. Getting a handle on the most common loan types is your first big step in making a smart move in this market.
A Snapshot of Current California Mortgage Rates
When you start digging into home loans, you'll quickly find a few core options. It helps to think of them as different routes to homeownership—each one designed for a different financial situation and set of goals. The one you land on could save you—or cost you—tens of thousands of dollars over the years.
By far, the most popular choice in the Golden State is the 30-year fixed-rate mortgage. Its appeal is simple: stability. Your interest rate is locked in for the entire three decades, which means your principal and interest payment will never change. That kind of predictability makes budgeting a whole lot easier.
Comparing Loan Types and Their Rates
Another great option is the 15-year fixed-rate mortgage. It works just like its 30-year cousin but on a much faster track. Because you’re paying off the loan in half the time, your monthly payments will be higher. The trade-off? You build equity incredibly fast and pay a lot less in total interest.
Finally, you have the Adjustable-Rate Mortgage (ARM). An ARM usually starts with a lower, "teaser" interest rate for a fixed period, like 5 or 7 years. After that initial term, the rate adjusts up or down with the market. This can be a savvy move if you think you’ll sell the house before that introductory period is up.
Today's rates are a direct reflection of a complex economy. As of August 22, 2025, the average 30-year fixed-rate mortgage in California was sitting around 6.58%. While that’s a slight dip from the previous month, it’s still much higher than where we were a year ago.
Making the Right Choice for Your Goals
So, which loan is right for you? It all comes down to your personal finances and what you want to achieve. Are you aiming for the absolute lowest monthly payment you can get? Or is your priority to own your home free and clear as quickly as possible, saving a bundle on interest?
Your answer points you to the best loan. While many buyers are searching for their forever home, others might be focused on investment properties, like the opportunities available in the market for condo rentals in Fresno, CA.
To make it a little easier, let's break down the most common loan types for California homebuyers side-by-side.
Comparing Common California Mortgage Types
This table summarizes the main home loan options available, highlighting their key characteristics and typical interest rate structures to help you choose.
| Loan Type | Typical Term Length | Interest Rate Behavior | Who It Is Best For |
|---|---|---|---|
| 30-Year Fixed | 30 Years | Rate remains the same for the entire loan term | Homebuyers who want predictable, lower monthly payments and plan to stay in their home long-term. |
| 15-Year Fixed | 15 Years | Rate is fixed, often lower than a 30-year loan | Borrowers who can afford higher monthly payments and want to build equity faster while saving on total interest. |
| 5/1 ARM | 30 Years | Fixed for the first 5 years, then adjusts annually | Buyers who plan to sell or refinance before the initial fixed-rate period ends or expect their income to rise. |
Each of these loans serves a different purpose, and understanding the nuances is the key to securing a mortgage that truly works for you and your family.
What Really Determines Your Mortgage Rate
Watching mortgage rates for homes in California bounce around can feel totally random, but there are some serious forces pulling the strings behind the scenes. It helps to think of the economy as a big, complex weather system. Just like atmospheric pressure and temperature create sun or storms, certain economic factors set the climate for mortgage rates. These are the huge, national influences that create a baseline rate before a lender even glances at your loan application.
The biggest player in this whole system is the Federal Reserve, or "the Fed." Now, the Fed doesn't actually set the rate on your 30-year fixed mortgage, but its decisions cause massive ripples through the entire financial world. When the Fed wants to cool down an overheating economy and get inflation under control, it raises its key interest rate. This makes it more expensive for banks to borrow money from each other, and you can bet they pass that cost right on to us—the consumers—through higher rates on mortgages, car loans, and credit cards.
We’ve seen this exact scenario play out in a big way recently. To fight runaway inflation, the Federal Reserve started hiking its rates back in 2022. That single policy move was the main reason we saw mortgage rates jump from historic lows near 3% to over 7% in what felt like the blink of an eye.
The Bond Market's Critical Role
Another huge piece of the puzzle is the bond market, especially U.S. Treasury bonds and mortgage-backed securities (MBS). You can think of these as financial thermometers for the economy’s overall health. When investors feel good about the economy and are ready to take on more risk, they tend to sell off these safer bonds. That selling pressure causes bond prices to fall and their yields—which is basically their interest rate—to rise.
Mortgage rates have a habit of shadowing the yield on the 10-year Treasury note. If you see on the news that Treasury yields are climbing, it’s a very strong signal that mortgage rates are about to do the same. Lenders literally use these market benchmarks to price their own loans, making the bond market a direct, day-to-day influence on the rate you're offered.
The connection is so tight that daily swings in the bond market can cause mortgage rates to change from the morning to the afternoon. This is exactly why getting a rate lock is so critical once you find a rate you’re happy with.
Inflation: The Silent Rate Hiker
Inflation is like a constant headwind pushing interest rates higher. When the price of everything is going up, the fixed monthly payment a lender receives from a mortgage becomes less valuable over the life of the loan. A dollar they get back from you ten years from now will buy a lot less than a dollar does today.
To protect themselves from this loss of future buying power, lenders charge higher interest rates from the get-go. This ensures that the return they make on their investment at least keeps up with the pace of inflation. It's the key reason why the inflationary surge after 2021 caused such a sharp and painful increase in interest rates for homes in California.
How Lenders Set Their Final Rates
Once the big economic "weather" sets the general rate climate, individual lenders then tweak their own rates based on their internal business needs. This is where the specific rate you see advertised actually comes from. A few factors are at play here:
- Operational Costs: Lenders are businesses with bills to pay. Everything from employee salaries to office rent and marketing gets baked into the rates they offer.
- Risk Appetite: Not all lenders view risk the same way. One might offer super-low rates to attract only the most qualified borrowers with pristine credit, while another might price their loans a bit higher to comfortably serve a wider range of credit profiles.
- Profit Margin: At the end of the day, lending is a business designed to make money. A piece of that interest rate is simply the lender's profit for providing you with the loan.
This is precisely why it is so important to shop around. One lender's overhead and profit goals could be completely different from the one down the street, leading to real differences in the rates they offer for the exact same loan. Understanding these layers—from the Fed's national policy down to an individual loan officer's pricing—pulls back the curtain and gives you the power to find the best possible deal.
To really get a handle on today's California mortgage rates, you have to look back. The numbers we see today didn't just appear out of thin air; they’re part of a much bigger economic story, one with some serious peaks and valleys. When you see the market through a historical lens, you start to realize these rates move in cycles. They aren't permanent.
Think of it like the ocean tide. Sometimes it's incredibly high, making it tough to get anywhere. Other times, it pulls way back and reveals all sorts of new opportunities. For homebuyers, these tides are shaped by decades of economic policy, fights against inflation, and overall market confidence.
What we call "high" today is a walk in the park compared to what our parents or grandparents dealt with. The history of mortgage rates in California shows a wild ride of economic shifts that directly impacted the dream of homeownership for millions.
The Era of Extreme Highs
The early 1980s were the most dramatic chapter in this story. The Federal Reserve was in an all-out war against runaway inflation, and they cranked interest rates up to levels that are almost hard to believe now. It was an incredibly tough time to be a homebuyer.
In 1981, the average 30-year fixed mortgage rate shot past a staggering 16%. That's not a typo. This peak made financing a home so expensive that it pushed countless would-be buyers to the sidelines. To get a better sense of this chaotic period, you can check out the historical mortgage rate trends on Bankrate.com.
The Record-Breaking Lows
On the complete opposite end of the spectrum, the years after the 2008 financial crisis—and especially 2020 and 2021—saw rates hit rock bottom. To jumpstart the economy, the Fed kept rates near zero, which created a golden opportunity for anyone looking to borrow money.
This period triggered a massive wave of homebuying and refinancing as people locked in rates that were often below 3%. This incredible affordability supercharged the housing market, but it also set the stage for the sharp rate hikes we've seen since 2022.
The swing from over 16% in 1981 to under 3% in 2021 is immense. It just goes to show how much the economic climate can change the cost of buying a home. Today’s rate is just one point on a much, much longer timeline.
This chart gives you a quick visual of just how dramatic the recent shifts have been.
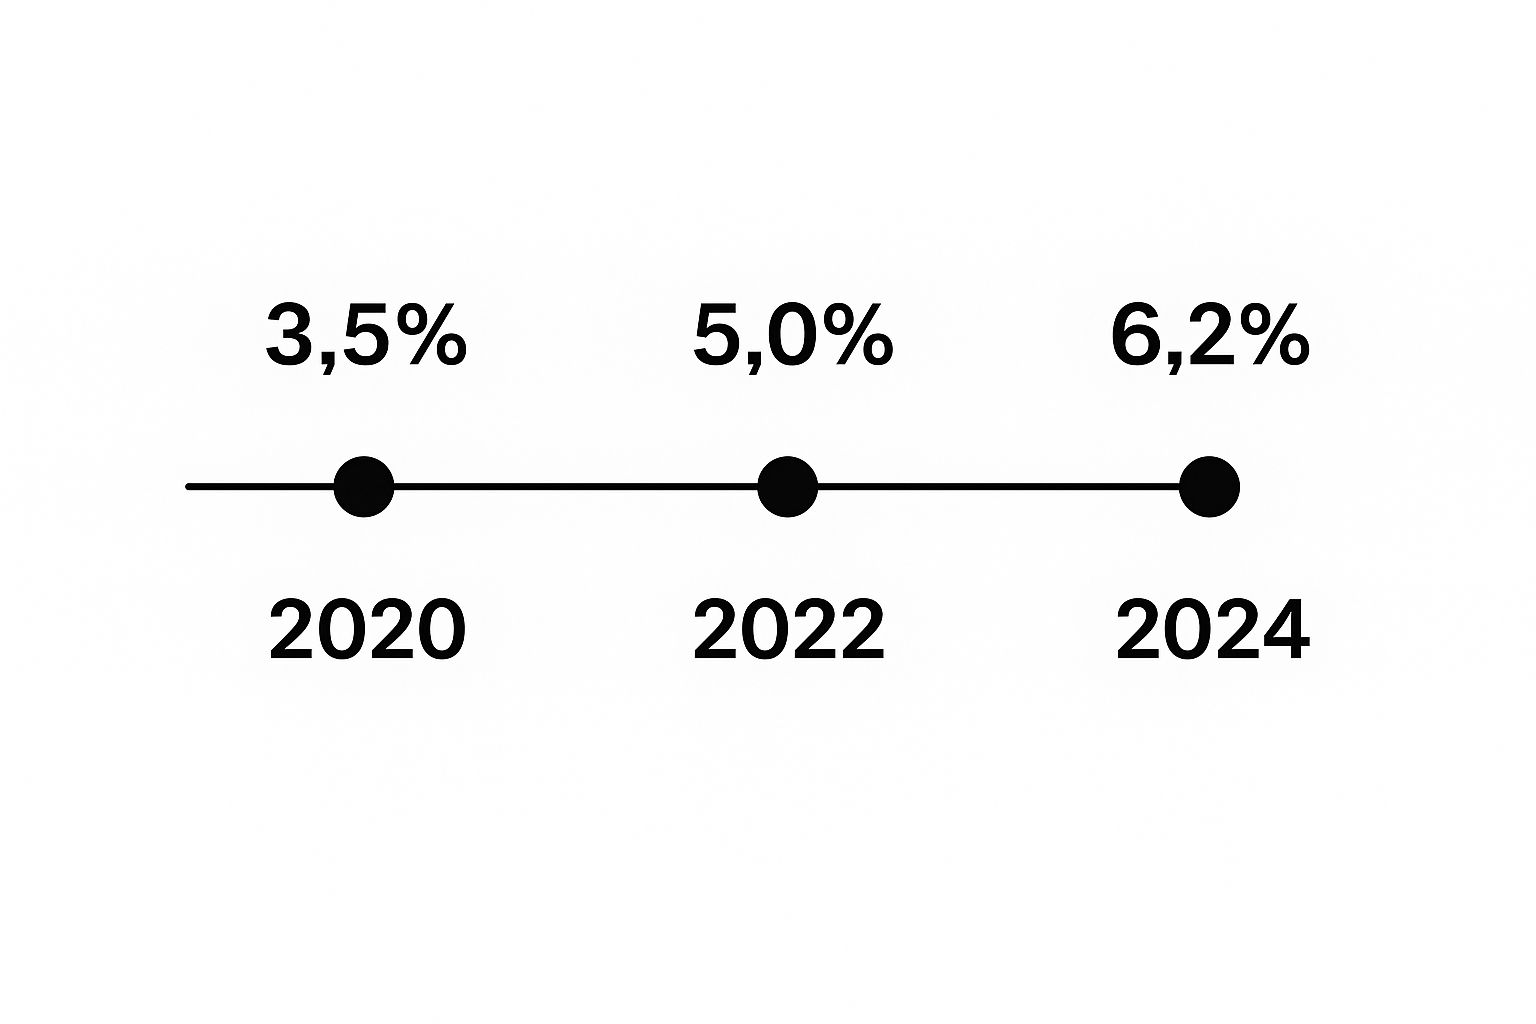
You can clearly see that steep climb from the lows of 2020, a stark reminder of how quickly the market can pivot.
Lessons from the Past
Knowing this history is a powerful tool. It teaches you that high-rate environments don't last forever, but neither do the super-low ones. These cycles are driven by huge economic forces, and if you can recognize them, you can make smarter long-term decisions. For instance:
- Patience Can Pay Off: Sometimes, just waiting for the market to shift can save you a significant amount of money over the life of your loan.
- Refinancing is Your Friend: People who bought homes when rates were high often get a chance to refinance later when the cycle turns and rates drop.
- Context is Everything: Understanding the historical range helps you see if a current rate is genuinely high, low, or just somewhere in the middle.
Ultimately, looking back gives you valuable perspective. It helps you cut through the noise and navigate the complexities of buying a home in California with a much clearer view of the road ahead.
How Your Finances Shape Your Interest Rate
While the big-picture economy sets the stage for interest rates, the actual number you get is all about you. Think of it this way: the economy sets the temperature of the water, but your personal financial health determines how well you swim. For lenders, it really boils down to one simple question: how much of a risk are you?
The less risky you appear as a borrower, the more confident a lender feels, and the better the rate they'll offer. A strong financial profile is your way of showing them you're a solid bet who will make your payments on time.
Luckily, the things they look at aren't some big secret. Knowing what lenders are digging into gives you a clear roadmap to get your finances in shape and lock in the best possible rate on a California home. It’s all about taking control of the pieces of the puzzle that are actually in your hands.
Your Credit Score: The Financial Report Card
Your credit score is easily the single most important number in this whole process. It’s like a financial report card, giving lenders a quick summary of how you’ve handled debt in the past. A high score sends a clear message: you have a track record of borrowing responsibly.
Lenders use a tiered system, and better credit scores unlock lower interest rates. A borrower with an "excellent" score (usually 760 or above) might get a rate a full percentage point lower than someone with a "fair" score. On a 30-year mortgage, that difference can literally save you tens of thousands of dollars.
If you're worried about your score, figuring out why your credit score might be dropping is the perfect first step to turning things around.
The Power of Your Down Payment
How much money you put down up front—your down payment—speaks volumes to a lender. A larger down payment means you're borrowing less, which immediately lowers their risk. This is all measured by something called the loan-to-value (LTV) ratio.
For instance, putting 20% down on a house gets you an 80% LTV, which is the gold standard for most lenders. A lower LTV usually gets you a better interest rate because you have more "skin in the game" right from the start.
A hefty down payment doesn't just help you get a better rate. It can also help you dodge Private Mortgage Insurance (PMI), which can add a big chunk to your monthly payment.
Managing Your Debt-to-Income Ratio
Finally, lenders are going to take a hard look at your debt-to-income (DTI) ratio. This number compares your total monthly debt payments (think car loans, student loans, credit cards) to your gross monthly income. It gives them a clear picture of whether you can truly handle a new mortgage payment.
Here's the simple math:
DTI = Total Monthly Debt Payments / Gross Monthly Income
Most lenders really want to see a DTI of 43% or less, although some loan programs can be a bit more flexible. A low DTI tells them you aren't stretched too thin and can comfortably afford the new house payment. You have two main ways to improve it:
- Pay down existing debt: Start chipping away at credit card balances or other loans before you apply.
- Increase your income: If you can, finding ways to boost what you earn will also help your ratio.
By getting a handle on these three key areas—your credit, your down payment, and your debt—you put yourself in the driver's seat. You’re no longer just accepting whatever rate comes your way; you're actively working to earn the best one out there.
Proven Strategies to Secure a Lower Rate
Getting the best possible mortgage rate isn't about luck—it's about strategy. In a market as competitive as California's, even a tiny difference in your rate can save you tens of thousands of dollars over the life of your loan.
One of the costliest mistakes you can make is just accepting the first offer a lender hands you. The real key is to be proactive and understand which levers you can pull to get yourself a much better deal. Lenders are competing for your business, and their first offer is almost never their best. A little preparation and negotiation are your most powerful tools here.
Never Stop at the First Offer
Think about it like buying a car. You wouldn't just walk into the first dealership you see and agree to pay the sticker price. The exact same logic applies to mortgages, but it's amazing how many buyers don't shop around.
It is absolutely essential to get quotes from multiple lenders to get a real feel for the market. Don't just look at the big national banks, either. Cast a wider net.
- Large Retail Banks: These are the household names you see everywhere, and they offer a huge range of loan products.
- Local Credit Unions: Because they're non-profits, credit unions can often pass the savings on to their members with more competitive rates and lower fees.
- Mortgage Brokers: A good broker is a fantastic resource. They work with dozens of different lenders and do all the comparison shopping for you to find the best fit.
Try to get at least three to four official Loan Estimates. This gives you a crystal-clear picture of what’s out there and provides some serious leverage when it's time to negotiate.
Lock in Your Rate Strategically
Once you find a rate you're happy with, it's not yours until you "lock" it in. A rate lock is basically a promise from your lender to honor a specific interest rate for a set amount of time, usually 30 to 60 days. This is your shield against market swings while your loan is being finalized.
If rates suddenly jump a week before you close, your locked rate stays put. But be aware of the flip side: if rates happen to fall, you're still committed to your higher locked rate unless your agreement includes a "float-down" option, which lets you take advantage of the drop.
Understanding Mortgage Points
When you get offers from lenders, you'll often see the option to buy mortgage points, sometimes called discount points. This is just a way to prepay some of your interest right at the beginning in exchange for a lower rate over the entire life of the loan.
Here’s how it works: one point costs 1% of your total loan amount. So, on a $500,000 loan, one point would cost you an extra $5,000 at closing. That payment might knock your interest rate down by a fraction of a percent, say from 6.75% to 6.50%.
The decision to buy points all comes down to your "break-even point"—the moment when the monthly savings from your lower rate finally cover what you paid for the points upfront. If you plan on staying in the home long past that point, buying down the rate can be a very smart financial move.
This is where it helps to think about the bigger picture. Understanding why buying single-family homes can be a good investment can offer some perspective on whether paying more now for long-term savings fits with your overall financial goals.
Deciding if You Should Pay for Mortgage Points
This table breaks down whether paying more upfront for a lower interest rate is the right financial move for your situation.
| Consideration | Paying for Points (Lower Rate) | Not Paying for Points (Standard Rate) |
|---|---|---|
| Upfront Cost | Requires more cash at closing. | Preserves your cash for other expenses like moving or furnishing. |
| Monthly Payment | Results in a lower monthly mortgage payment. | Your monthly payment will be slightly higher. |
| Best For | Homebuyers planning to stay in the home for many years, well past the break-even point. | Buyers who are shorter on cash at closing or may sell or refinance within a few years. |
Ultimately, taking these steps—shopping around, locking your rate wisely, and carefully weighing the pros and cons of mortgage points—puts you firmly in the driver's seat. You go from being a passive rate-taker to an active participant who can secure a much better financial future.
Common Questions About California Home Loans
Even after you get the basics down, you probably still have a few questions rolling around in your head. That’s completely normal. The world of California home loans can feel like a maze, but getting clear, straightforward answers is the best way to feel confident about your next move.
Think of this section as a final Q&A session to clear up any lingering confusion and get you ready for the journey ahead.
What Is the Difference Between Interest Rate and APR?
This is easily one of the most common points of confusion for homebuyers, and it’s a great question. The two numbers look similar, but they tell you slightly different things about what you’re actually paying.
The interest rate is like the sticker price of the loan. It’s the direct percentage the lender charges you for borrowing their money, and it’s the number that determines your monthly principal and interest payment.
The Annual Percentage Rate (APR), on the other hand, is the total cost. It bundles the interest rate with other lender fees, like origination fees or closing costs. Because it includes those extras, the APR is almost always a bit higher than the interest rate.
When you're shopping around and comparing loan offers, always look at the APR. It gives you a true apples-to-apples comparison of what each loan will really cost you. It’s the more honest number.
Can I Renegotiate My Interest Rate Before Closing?
Sometimes, but it’s not a given. Once you have a signed contract and your lender has locked in your rate, that rate is usually set in stone for a specific period, typically 30 to 60 days.
However, some lenders offer what’s called a "float-down" option. If market rates happen to take a nosedive after you’ve already locked, this feature might let you snag that new, lower rate. These options usually come with a fee and have specific rules, so it's smart to ask your lender about their float-down policy before you lock. Otherwise, you’re committed to the rate you agreed on.
How Often Do Mortgage Rates Change?
Daily. And sometimes, multiple times a day. Mortgage rates aren't set by some government committee; they bounce around in real-time based on the bond market, investor moods, and the latest economic news.
This constant fluctuation is exactly why a rate lock is so crucial. It puts a freeze on your interest rate, protecting you from any sudden spikes that could happen while your loan is being processed.
Do Rates Vary by Location Within California?
Yes and no. The big economic forces pushing rates up or down are national, but you can find slight differences from one part of California to the next. It’s less about the base interest rate and more about local market factors.
For instance, lenders in super-competitive markets like Los Angeles or the Bay Area might offer slightly different fee structures or promotions to win your business. In more rural areas, you might see less of that. The core interest rate will be very similar across the state since it’s tied to the same national benchmarks, but the final package can vary.
What Is the "Lock-In Effect" in California?
The "lock-in effect" is a huge deal in California’s housing market right now. It describes homeowners who are sitting on mortgages with incredibly low rates—many below 3% or 4% from the 2020-2021 refi boom. They have a powerful financial reason not to sell their homes and buy a new one at today’s much higher rates.
This has choked off housing supply, as fewer people are listing their properties. A recent study showed that California cities like San Jose and San Francisco are among the most "locked-in" in the U.S., which helps explain why home prices remain stubbornly high. If you're thinking about buying another property, this practical guide to financing a second home can offer some valuable insights.
Are Today's Rates Considered High Historically?
While rates in the 6-7% range feel steep compared to the last few years, they're actually much closer to the long-term historical average. We’ve all been spoiled by the record lows around 3% back in 2021.
Looking back, rates were hovering under 4% for much of 2019 and averaged over 8% in the more distant past. For today’s California homebuyers, it means adjusting budgets and expectations. It also means it’s more important than ever to explore every loan option available. For those who own property, navigating this climate also means staying sharp on rental laws; knowing the ins and outs of landlord-tenant law in California is critical for managing an investment successfully.
Whether you are buying, selling, or managing property in the Central California region, the expert team at Edinhart Realty and Property Management is here to help you achieve your real estate goals. Our deep understanding of the Fresno and Clovis markets, combined with professional service, ensures you get maximum value from your investment. https://edinhart.com


