

You pull up your home value online, see a number that looks strong, and your first thought is simple. If I sell my home, how much will I make?
That question comes up constantly with Fresno and Clovis homeowners. The hard part isn't finding a rough sale price. The hard part is figuring out what lands in your bank account after the mortgage, selling costs, prep work, and possible tax issues are dealt with.
A lot of sellers start with the headline number and mentally spend from there. That's where people get blindsided. The sale price matters, but net proceeds matter more. If you want a realistic answer, you need to work from the top down and subtract the right things in the right order.
Your Home Sale Profit Is More Than Just the Price Tag
A Fresno seller accepts an offer at a price that feels great, then sees the settlement statement and realizes the check is far smaller than expected. That gap usually comes from focusing on market value without running the full sale math first.
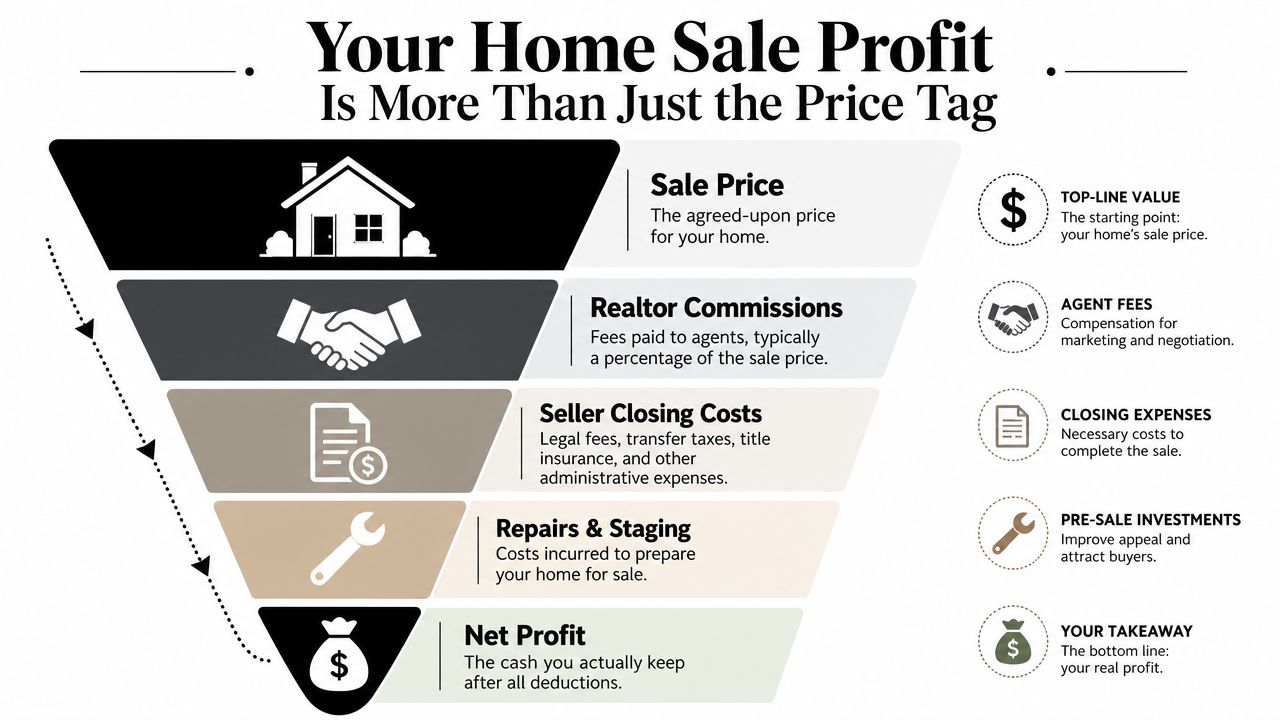
The cleanest way to estimate what you may make is to separate three numbers that sellers often blend together:
- Sale price is the amount a buyer agrees to pay.
- Net proceeds is what remains after loans and selling expenses are paid through escrow.
- True profit goes further and compares your result to your original cost basis, including certain capital improvements and any taxable gain.
That third number matters more than many homeowners expect. I have seen sellers in Fresno and Clovis estimate their move based on equity alone, then realize later that taxes could change the picture. A simple calculator can miss that. A scenario-based estimate is more useful because it lets you test a few sale prices, compare likely costs, and check whether the primary residence exclusion may reduce or eliminate capital gains tax.
If you want a better handle on value before you run those scenarios, review this guide on how to price a home for sale in Fresno. Price drives every number that follows, but it still is only the starting line.
If you're still getting familiar with the language of ownership and equity, this Equity guide for Florida homeowners does a good job explaining the basic relationship between value, debt, and what you own. The examples are Florida-based, but the core concept applies anywhere.
What usually gets deducted
From my experience working with Fresno-area sellers, the math is easiest to break into four buckets:
Your loan payoff
The mortgage gets paid through escrow at closing. Home equity lines, solar loans tied to the property, delinquent property taxes, or other recorded liens can reduce proceeds too.Selling expenses
This includes agent compensation, escrow and title charges, transfer-related fees, and buyer credits if you agree to them in the contract.Pre-sale work
Paint, cleaning, yard cleanup, staging, and repairs often help a home sell faster or stronger, but they still come out of your overall result.Taxes
This is the piece sellers skip too often. Cash at closing and taxable gain are separate calculations. If the home has been your primary residence, the exclusion may protect a large portion of gain. If it has been a rental, inherited property, or long-term hold with major appreciation, the tax side deserves a closer look before you commit to a move.
A realistic seller estimate answers a practical question. After debt, selling costs, and possible taxes are handled, how much cash is left for the next purchase, payoff, or relocation plan?
That approach turns the sale from a rough guess into a working set of numbers you can use.
Establishing Your Realistic Sale Price
The first number in your worksheet has to be realistic. Not optimistic. Not emotional. Not pulled from an automated estimate that doesn't know your lot placement, interior updates, traffic exposure, or how your home compares to the one around the corner that sold with a remodeled kitchen and new flooring.
In Fresno, Clovis, and nearby neighborhoods, small details change the result. A home near a well-regarded school boundary, one with a cleaner layout, or one that shows better online can attract stronger offers than a nearby property with similar square footage. That's why a Comparative Market Analysis, or CMA, is still the best place to start.
Why a CMA beats a quick online estimate
A strong CMA looks at actual comparable sales, active competition, and recent pending activity. It also adjusts for condition and presentation. If two homes have similar bones but one is dated and the other is dialed in for photos and showings, they won't perform the same.
That local context matters more than many sellers think. Fresno buyers compare homes fast. They're watching condition, layout, lot utility, neighborhood feel, and what else they can get for the same money.
A realistic price range is more useful than a single flattering number.
Use three price cases, not one guess
The highest-accuracy method is a side-by-side scenario analysis built around comparable sales, not a single point estimate. One expert workflow recommends entering multiple sale-price scenarios into separate columns, then subtracting expenses from each to compare expected profit outcomes, which helps reduce the risk of overpricing and the longer market time that can follow, according to this scenario-based home sale estimate workflow.
That approach works well in practice because sellers rarely have just one possible outcome. You might have:
- A conservative case based on a quick sale and clean terms
- A likely case based on current comparable sales
- A stronger case if presentation, timing, and buyer demand line up well
This is also why pricing strategy matters more than pride. A home that starts too high can lose momentum. Buyers assume there's a problem, showings slow down, and the seller often gives up money later through price cuts or concessions.
For a deeper look at how to set that range, this guide on how to price a home for sale is a useful reference point.
Look beyond your own neighborhood when needed
Sometimes sellers benefit from seeing how other markets explain community value. For example, a page covering Pine Canyon Club amenities and HOA shows how neighborhood features and ownership costs shape buyer perception. Different market, same lesson. Buyers don't pay for square footage alone. They pay for the full living experience.
A realistic sale price starts with comps, but it gets sharper when you test more than one likely outcome. That's the foundation for the rest of your numbers.
Subtracting Your Mortgage and Other Debts
This part is usually the easiest because it's the least speculative. You're not estimating buyer behavior here. You're identifying debts that have to be paid when escrow closes.
Most homeowners start with the mortgage statement, but the balance shown there isn't always the exact payoff amount. Lenders often calculate a formal payoff that includes interest through a specific date and any required fees tied to closing the loan. If you want a clean estimate, request a mortgage payoff statement from your lender.
What to check before you list
Use this short checklist:
- Primary mortgage payoff: Ask your lender for the current payoff, not just the unpaid principal balance.
- HELOC or second mortgage: If you borrowed against the home later, that amount also has to be cleared.
- Property tax or contractor liens: Escrow will usually uncover these, but it's better to know early.
- HOA balances or transfer-related charges: If your property has an association, ask what gets billed to the seller.
In my experience, homeowners typically either feel relief or surprise. Relief if the debt is lower than expected. Surprise if there's an old line of credit, deferred maintenance bill, or lien they forgot was attached to the property.
Why this number matters early
A seller can have strong equity on paper and still feel squeezed if the loan payoff is high. That's common with people who refinanced, took cash out, or used a HELOC for upgrades or other expenses.
Get exact payoff figures before you start planning your move. The wrong debt number can throw off every other estimate.
Once you know the debt side, your math gets cleaner. You're no longer asking vague questions. You're narrowing in on actual proceeds. Then the variable part begins, which is where most of the decision-making lives.
Calculating the Variable Costs of Selling
A Fresno seller accepts an offer at a price that feels strong, then the closing statement shows a different reality. Commission, escrow and title fees, prep work, repair credits, and a few smaller charges cut into the number fast. That is why I run this part as a range, not a single estimate.
These costs move because your sale strategy moves. A home in move-in condition with clean disclosures usually carries a different expense profile than a rental with deferred maintenance, an older home with inspection issues, or a property that needs help on presentation before it hits the market.
Commissions and transaction costs
Agent compensation is usually the first line item sellers ask about, and it should be. It is also only one part of the sale expense picture.
Closing costs can include escrow fees, title charges, county recording or transfer-related costs, HOA document or transfer fees, and administrative charges that show up on the settlement statement. Some are modest. Together, they still matter.
I tell clients to compare options based on expected net, not one line item. Marketing quality, pricing discipline, buyer traffic, negotiation, and contract management all affect the amount you keep. A lower fee does not help if the home sits, attracts weak terms, or ends in larger credits after inspections.
Repairs, prep, and presentation
This category has the widest spread.
One seller spends a few hundred dollars on cleaning, mulch, touch-up paint, and professional photos. Another needs roof work, pest treatment, section one repairs, hauling, and staging. Both are selling a home. Their cost structure looks nothing alike.
Common variable expenses include:
- Repair work: Leaks, broken fixtures, damaged trim, HVAC issues, and other deferred maintenance buyers flag during inspections
- Cosmetic prep: Paint, deep cleaning, carpet replacement, yard cleanup, and small updates that improve first impressions
- Marketing presentation: Staging, photography, video, and other listing materials that affect online response and showing activity
- Seller credits: Money offered to the buyer for repairs, rate buydowns, or closing costs to keep the deal together
The practical question is simple. If you spend $5,000 before listing, does that improve your likely net by more than $5,000, or does it just make the house nicer? Those are different outcomes.
A sample way to map the math
I like to sketch this out before a seller approves any prep budget or responds to repair requests. It keeps the decision tied to proceeds instead of guesswork.
| Item | Amount | Remaining Balance |
|---|---|---|
| Contract sale price | $450,000 | $450,000 |
| Mortgage payoff | Varies | Sale price minus payoff |
| Selling charges | Varies | Sale price minus payoff and selling charges |
| Repairs and prep | Varies | Sale price minus payoff, selling charges, and prep |
| Seller credits if any | Varies | Sale price minus all above items |
| Estimated net proceeds before tax analysis | Varies | Final estimated cash |
If you want a local worksheet for these line items, this California seller closing costs calculator is a useful starting point.
Where sellers usually help or hurt their net
The sellers who protect their proceeds tend to be selective. They fix defects buyers will notice, spend on items that show well in photos and tours, and avoid pouring money into personal-preference upgrades that the market may not pay back.
A few patterns come up often in Fresno and Clovis:
- Visible condition problems get penalized hard. Buyers usually assume the repair is bigger than it is.
- Light cosmetic work often pays better than niche upgrades. Clean, bright, and cared-for beats customized.
- Credits can be smart. In some cases, giving a buyer money at closing is cheaper and cleaner than rushing repairs with contractors under deadline.
- Terms affect your bottom line. A slightly lower offer with fewer contingencies, stronger financing, and less repair pressure can leave you with more cash at closing.
That last point matters more than many sellers expect. I have seen contracts with the bigger sale price lose ground after inspection credits, appraisal issues, and extra carrying time. The better offer is the one that produces the stronger net after the full deal structure is on paper.
Factoring In Taxes on Your Home Sale Profit
This is the part many online tools barely touch, and it can make a major difference. Net proceeds are the cash left after paying selling expenses and debt. Taxable gain is a separate calculation used to determine whether tax may be owed on the profit recognized by the IRS.
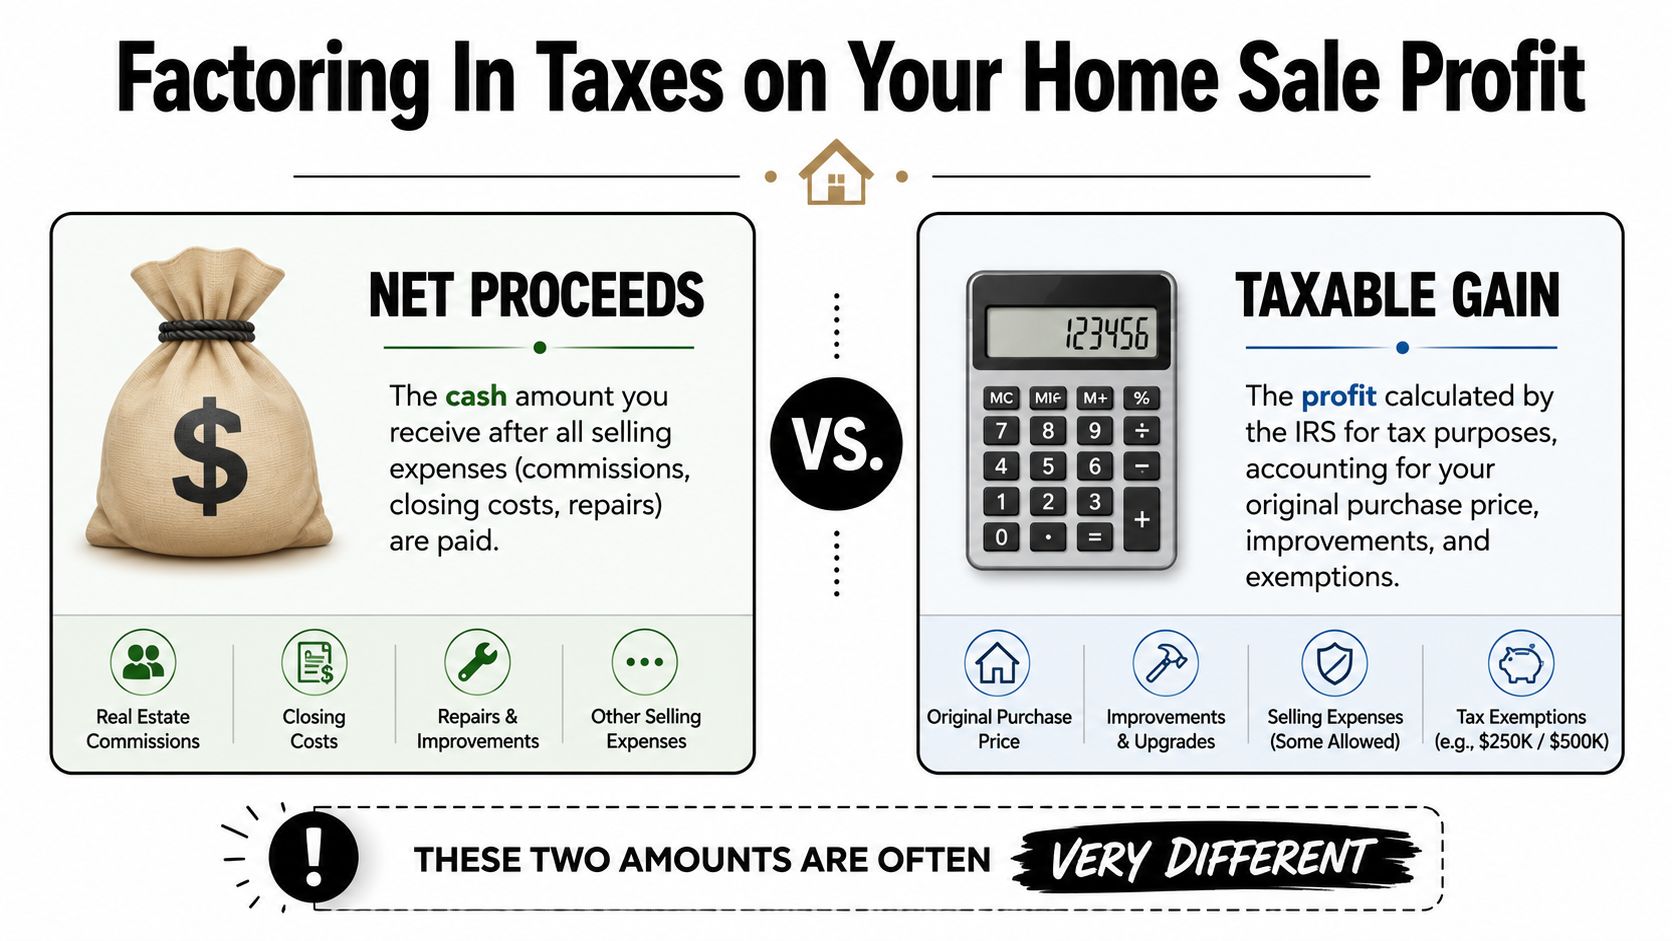
A seller can walk away with substantial net proceeds and still have little or no taxable gain. The reverse can also happen. That's why “how much will I make” isn't just a closing statement question. It's also a tax planning question.
Net proceeds and taxable gain are not the same
Profit for tax purposes generally depends on more than sale price minus mortgage. It can involve your original purchase price, certain improvements, and other factors. That's one reason broad online calculators often leave people with an incomplete picture.
Many online calculators subtract mortgage payoff and commissions but fail to model capital-gains treatment. For a qualifying primary residence, the exclusion can allow up to $250,000 of gain for single filers and $500,000 for joint filers, which can materially affect final take-home cash, as noted in this home sale calculator discussion of capital gains treatment.
When the primary residence exclusion matters
For many homeowners, this exclusion is the biggest overlooked issue in the whole process. If the property has been your primary residence and you meet the ownership and use tests referenced in the verified guidance, that exclusion may shelter a substantial amount of gain.
That doesn't mean everyone qualifies in the same way. Questions come up when the property wasn't your main home, when occupancy history is mixed, or when part of the property had some other use. Those situations deserve tax advice, not guesswork.
For a practical local primer, this resource on capital gains tax on a home sale is worth reviewing before you list.
Here's a quick visual explainer that helps frame the issue:
The mistake sellers make
The common error is treating taxes as an afterthought. A seller sees a strong market value, subtracts loan payoff and selling costs, and assumes that's the final answer. Sometimes it is close. Sometimes it isn't.
Ask two separate questions: “What are my net proceeds at closing?” and “What part of my gain, if any, may be taxable?”
Those are different conversations. One belongs in your sale worksheet. The other belongs with your tax professional before the property closes.
How to Maximize Your Proceeds and Plan Your Next Move
The biggest gains usually come from discipline, not from throwing money at the house. Sellers increase proceeds when they improve marketability, avoid waste, and make decisions based on net outcome instead of emotion.
Start with the upgrades buyers notice immediately. Clean condition, sharp photos, strong curb appeal, and a realistic list price often do more for a sale than expensive projects that reflect personal taste. If you're considering a larger kitchen update before listing, it helps to run the numbers first with a tool that can calculate kitchen renovation return. Not every remodel pays back the way sellers expect.
A simple seller checklist
- Build three sale scenarios: conservative, likely, and stronger outcome
- Request exact payoff figures: include every loan tied to the property
- Map all selling costs: transaction charges, prep costs, and likely concessions
- Separate cash from tax questions: don't treat net proceeds and taxable gain as the same
- Choose prep work strategically: focus on work that improves presentation and buyer confidence
Sellers usually lose money in one of two ways. They overprice and chase the market down, or they overspend on improvements that don't change buyer behavior enough to justify the cost.
A practical plan is better than a perfect guess. If you're trying to answer, “If I sell my home, how much will I make,” the most reliable path is a local net sheet built from actual comps, actual debts, and likely terms, not a one-number online estimate.
Frequently Asked Questions About Home Sale Proceeds
Is a repair credit better than lowering the price?
It depends on the contract and the buyer's financing, but the two aren't automatically equal. A lower sale price changes the top-line number. A repair credit keeps the price higher but still reduces your net. In some deals, keeping the higher price supports appraisal or financing strategy better. In others, a clean price reduction is simpler.
Can home improvements reduce capital gains tax?
They can matter if they count toward your basis calculation, but accurate records are essential. Keep invoices, receipts, and a clear paper trail for qualifying work. Cosmetic touch-ups right before listing may help the sale, but that doesn't mean they affect taxes the same way. Your tax professional should review what qualifies.
Do I avoid taxes if I sell and buy another home right away?
Buying another home doesn't automatically erase taxes from the sale of the old one. What matters is whether you qualify for the primary residence exclusion and how your gain is calculated. Sellers sometimes assume a quick purchase of the next property changes everything. It often doesn't.
The practical takeaway is simple. Don't rely on timing myths, rough online estimates, or guesswork from friends. If the numbers matter, run the sale side and the tax side separately.
If you want a personalized estimate instead of a generic calculator, Edinhart Realty and Property Management can help you build a realistic net sheet based on local comparable sales, your current loan payoff, expected selling costs, and the specific trade-offs that apply to your Fresno, Clovis, Friant, or Central California property. That kind of planning makes the move easier because you're working from real numbers, not hopeful ones.


