

So, you're thinking, "I want to rent out my home." That’s a huge financial step and, frankly, your first real move into real estate investing. The biggest hurdle isn't the paperwork or the repairs—it's the mental leap from homeowner to landlord. You have to start seeing your property not just as your home, but as a business asset that needs smart management to actually make you money.
Transitioning From Homeowner to Landlord
Choosing to rent out your property is about more than just finding someone to live there and collecting a check. It’s a deliberate decision to become a business owner, with your home as the main asset. This whole process demands a completely new way of thinking, one that’s laser-focused on profitability, legal compliance, and protecting your investment.
This first phase is all about getting the lay of the land. What’s the rental market in Central California really like right now? What are your legal obligations as a landlord here? And what do you actually need to do to get your home ready for the kind of high-quality, reliable tenants who will treat it right?
Before you get too deep in the weeds, it's worth taking a moment to make sure this is the right path. Our guide comparing whether you should rent or sell your house is a great resource to help you get clear on that big initial decision.
The Landlord Mindset
Adopting a landlord mindset is all about detaching emotionally from the property. Your decisions need to be driven by business logic, not by how much you love the new kitchen backsplash.
- You are a service provider: Your job is to offer a safe, habitable home in return for rent. That means handling repairs in a timely manner and always communicating professionally.
- Your property is an investment: The goal here is to maximize your return through steady rental income while keeping the property in great shape to preserve its value.
- Proactive management is everything: Just waiting around for things to break is a recipe for disaster (and expensive repairs). A savvy landlord anticipates maintenance needs, keeps an eye on market trends, and stays up-to-date on all the legal stuff.
This diagram really breaks down the core stages of your transition: first, shifting your mindset, then prepping the property, and finally, getting a handle on your legal duties.
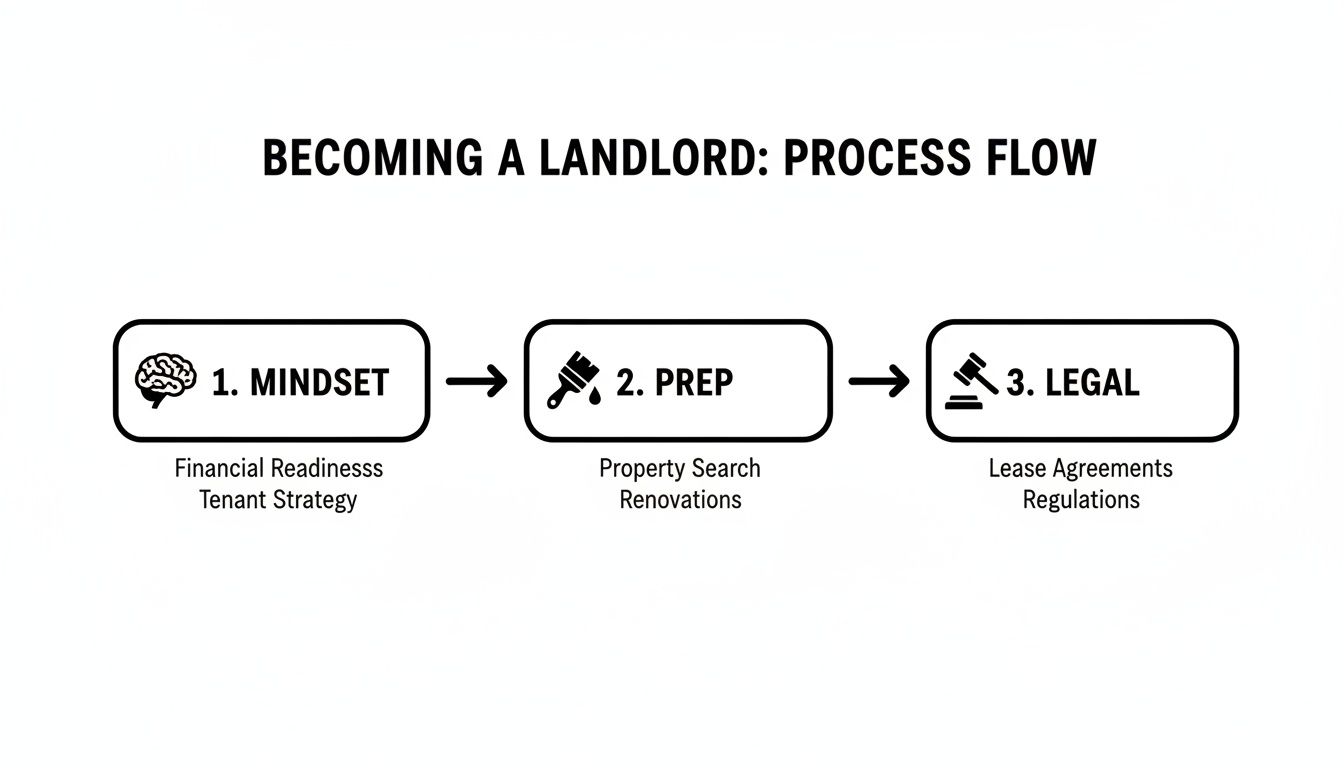
Looking at your journey in these distinct phases helps turn what feels like a massive undertaking into small, manageable steps.
Navigating the Modern Rental Market
The decision to rent out your home is also being shaped by some major global trends. The worldwide vacation and long-term rental market was valued at around USD 174.84 billion in 2024 and is expected to blow past USD 396.93 billion by 2032.
For a homeowner in a place like Fresno or Clovis, this explosion means that today's tenants have much higher expectations. They want professionalism and quick responses. To compete and succeed, you need to rely on data-driven pricing, smart marketing, and an ironclad screening process.
A successful transition into being a landlord isn't just about the physical property; it's about building a solid operational framework. This includes everything from your tenant screening process to your financial record-keeping and your plan for handling late-night repair calls.
Getting Your Property Rent-Ready for Maximum Appeal
Before you even think about taking photos or writing a listing, the real work begins. Getting your home "rent-ready" is what makes the difference between a property that sits vacant for months and one that attracts great tenants and top dollar right out of the gate. This isn't just about a quick clean-up; it's about strategically preparing your home to be a durable, appealing rental.
Think of it this way: you're preparing a product for the market. The goal is to present a clean, safe, and welcoming space where potential renters can immediately picture their lives. Every little detail, from a squeaky hinge to an old light fixture, shapes their first impression.
Prioritize Repairs and Smart Upgrades
First thing's first: do a thorough, top-to-bottom inspection. You have to switch your mindset from a homeowner—who might be used to a few quirks—to a landlord. That dripping faucet or sticky lock you barely notice anymore? To a tenant, it's a legitimate problem and a reason to call you at 10 PM.
Make a checklist and get these done before anything else:
- Plumbing and Electrical: Fix every leak, slow drain, and faulty outlet. Make sure all light switches and fixtures work perfectly.
- Appliances: Run every appliance—the dishwasher, the oven, the works—to confirm they’re in good shape.
- HVAC System: Get your heating and cooling systems professionally serviced. This is one of the best preventative moves you can make to avoid a costly emergency call on a hot summer day.
- Safety Devices: Install or test all smoke and carbon monoxide detectors to ensure they comply with California law.
Once the essentials are handled, think about small, high-impact upgrades. You don't need a full-blown remodel. Sometimes, just replacing dated cabinet hardware, swapping out old light fixtures, or installing a modern faucet can totally change the feel of a room without draining your budget.
The Power of a Fresh Coat of Paint
I can't stress this enough: never underestimate what a fresh coat of paint can do. It's hands-down one of the most cost-effective ways to make a property feel clean, bright, and cared for. When it comes to color, the goal is mass appeal.
You might love a dramatic accent wall, but tenants need a blank canvas to imagine their own furniture and style. Neutral colors are your best friend. Light grays, beiges, and soft off-whites make spaces feel larger and newer. To make it easy, we've put together a guide on choosing paint colors for your rental home that highlights durable and popular options.
A clean, neutral backdrop doesn’t just attract more applicants; it also makes your life easier. Touching up a neutral wall between tenants is a breeze, saving you time and money on turnovers.
Deep Cleaning and Boosting Curb Appeal
After the repairs and painting, a professional-level deep clean is non-negotiable. This goes way beyond your typical Saturday morning tidy-up. We're talking every nook and cranny—inside cabinets, behind the fridge, baseboards, window tracks—everything should be spotless. This sets the standard for how you expect the property to be kept and returned.
And don't forget the outside! The curb appeal is the very first thing a prospective tenant sees, and that first look is powerful.
- Landscaping: Mow the lawn, trim back any overgrown bushes, and pull all the weeds.
- Entryway: Sweep the porch and walkway. A new welcome mat and a couple of potted plants can add a welcoming pop of color.
- Windows and Doors: Clean all the exterior windows and wipe down the front door. If it’s looking tired, a fresh coat of paint works wonders.
Making a Lasting Digital Impression
Let's be honest, the first "showing" always happens online. Blurry, dark photos from your phone will get your listing scrolled past, no matter how great the place is in person.
To really stand out and draw in the best applicants, it’s worth investing in professional real estate photography. A pro knows how to use light and angles to make rooms look spacious and inviting. This single investment can lead to more inquiries and a shorter vacancy period, paying for itself almost immediately.
How to Price Your Rental and Project Your Profitability
Nailing down the right rent for your property is less of a science and more of an art—but it's an art that's deeply rooted in good data. If you aim too high, you’re staring down the barrel of long, expensive vacancies. Go too low, and you're literally giving away money month after month. The goal is to hit that sweet spot that attracts great tenants fast while maximizing what you earn.
The first thing to do is a comparative market analysis (CMA). This isn't just about a quick scan of Zillow. It’s about a deep dive into what similar properties—what we call "comps"—are actually renting for right in your neighborhood.
Finding and Analyzing Rental Comps
Your analysis needs to be laser-focused. You're looking for rentals within about a half-mile radius that are as close a match to your own home as possible.
- Property Type: A single-family home should only be compared to other single-family homes, not condos or townhouses.
- Bedrooms and Bathrooms: If you have a three-bed, two-bath, that’s your benchmark. Don't compare it to a four-bed, three-bath.
- Square Footage: Stick to properties within a 10-15% size range of your home.
- Age and Condition: A completely remodeled home is in a different league than an original 1970s build and will absolutely command a higher rent.
- Amenities: Things like a swimming pool, a two-car garage, or a brand-new kitchen carry real weight and need to be factored in.
Once you’ve got three to five solid comps, you can start to see a clear range. For instance, if similar homes are getting between $2,200 and $2,400 a month, you've found your baseline. If your property has a stunning new kitchen while the others are dated, you can confidently aim for the top of that range.
Here's a pro tip: the list price isn't always the final price. Try to find out how long a property sat on the market. A comp that was snapped up in a week was probably priced right. One that languished for 45 days? Almost certainly overpriced.
This kind of analysis is even more important when you look at the bigger picture of supply and demand. Occupancy rates can sometimes tell a more revealing story than the rent numbers alone. As you can read in this detailed analysis of rental market statistics, how you present and price your property becomes a game-changer, especially in a crowded market.
Calculating Your True Expenses
The rent you collect is just one side of the coin. To really get a grip on your profitability, you need a painfully honest look at your expenses. So many first-time landlords make the classic mistake of thinking their profit is just the rent minus the mortgage payment. It’s way more complicated than that.
Your financial projections have to include every single potential cost that comes with owning and managing a rental.
Fixed Monthly Costs:
- Mortgage Principal & Interest: Your main loan payment.
- Property Taxes: Take your annual bill and divide it by twelve.
- Homeowners Insurance: You’ll need to switch to a landlord policy, which typically costs about 25% more than a standard policy.
- HOA Fees: Don't forget these if your property has them.
Variable and Long-Term Expenses:
- Vacancy Fund (5-10% of rent): Let's be real—no property stays rented 100% of the time. You have to set money aside to cover the gaps between tenants.
- Maintenance & Repairs (5-10% of rent): This is your fund for everything from a leaky faucet to a busted water heater. Even if you don't touch it for months, you’ll be glad it’s there when a big-ticket repair pops up.
- Property Management Fees (if applicable): These usually run between 8-12% of the monthly rent.
Let's see how this plays out in the real world. Imagine you set your rent at $2,500. Your mortgage, taxes, and insurance come to $1,700. After you sock away 10% for vacancies ($250) and another 10% for repairs ($250), your actual monthly cash flow isn't $800—it's $300. This kind of realistic forecast is absolutely essential for making smart decisions and ensuring your rental property is a sustainable investment.
Understanding California Landlord Tenant Law
Stepping into the role of a landlord in California means you're doing more than just handing over a set of keys. You're entering one of the most heavily regulated rental markets in the country. When you decide, "I want to rent out my home," you're also signing up for a serious set of legal responsibilities.
Navigating this web of laws isn't just good practice—it's absolutely mandatory for protecting your investment and avoiding some truly painful legal trouble. These rules are designed to balance the rights of both landlords and tenants, and ignoring them, even by accident, can lead to steep financial penalties and disputes you could have easily sidestepped.
Getting a handle on these obligations from day one is the foundation of a solid, professional landlord-tenant relationship. It lets you operate with confidence, knowing you're compliant and prepared. For a deeper look, our comprehensive guide on California's landlord-tenant law breaks down these crucial topics even further.
Fair Housing and Avoiding Discrimination
Before you even think about posting your rental listing, you have to get familiar with the Federal Fair Housing Act and California’s Fair Employment and Housing Act (FEHA). These laws are crystal clear: you cannot discriminate against tenants based on a long list of protected characteristics.
In California, that list is extensive. It includes:
- Race, color, and national origin
- Religion and sex (including gender identity and sexual orientation)
- Familial status (having kids) and marital status
- Disability (both physical and mental)
- Ancestry, source of income, and veteran status
This means you can’t refuse to rent to someone, offer different terms, or write an ad that shows a preference for or against any of these groups. Even an innocent-sounding phrase like "perfect for a young professional" could be seen as discriminatory against families or older renters. To keep things legal from the get-go, make sure you're using the right documents, like a compliant California rental application form.
Handling Security Deposits Correctly
California has some of the strictest security deposit laws in the nation, and they aren't suggestions. These are hard-and-fast rules you must follow to the letter.
First off, the most you can charge for a security deposit is two times the monthly rent for an unfurnished unit. If your place is furnished, you can go up to three times the rent. You can't call any part of it "non-refundable," either. All deposits are considered the tenant's money until you can legally claim a portion for specific, documented reasons.
Once a tenant moves out, the clock starts ticking. You have exactly 21 calendar days to either return the full security deposit or send an itemized statement of deductions. If any repair or cleaning cost is over $125, you must include receipts.
Missing that 21-day deadline can have serious consequences. A judge could order you to return the entire deposit and pay the tenant up to twice that amount in damages—even if there was legitimate damage to your property.
The Implied Warranty of Habitability
Every rental agreement in California automatically includes an "implied warranty of habitability." Think of it as a legal guarantee that your property will be kept in a livable condition for the entire tenancy. This isn't just about the big stuff; it covers a whole range of essential features.
Legally, you're on the hook to provide:
- Effective waterproofing on the roof and exterior walls.
- Working plumbing with both hot and cold running water.
- A functional heating system.
- Safe electrical lighting and wiring that's up to code.
- Clean and sanitary grounds, free from pests and vermin.
- Enough trash cans for the building.
- Floors, stairways, and railings that are kept in good repair.
When a tenant reports a problem that affects the home's habitability, you are required by law to fix it within a reasonable amount of time. Being proactive with maintenance isn't just good business; it's a legal duty that protects both you and your tenant. This is one of the most critical responsibilities you have as a landlord in California.
So, you’ve sorted out the legal basics and whipped your property into shape. Now comes the big one. It's the decision that will define your life as a landlord, impacting everything from your free time to your stress levels to your bank account: should you manage the place yourself or bring in a professional?
When you first think, "I want to rent out my home," this is the crossroads you’ll inevitably face. There's no magic formula here; the right choice is completely tied to your personality, your expertise, and just how hands-on you really want to be.
Going it alone gives you total control and, of course, you pocket the management fees. But that also means you’re the one fielding a call about a busted water heater at 2 AM. On the flip side, professional management takes that entire operational headache off your plate, but it comes at the cost of a slice of your monthly rent.
The Realities of Self-Management
Let’s be honest, managing your own rental can be incredibly satisfying. You learn the ropes of the business, and every dollar of profit, minus expenses, is yours to keep. But you have to be brutally honest with yourself about what the job actually involves.
This isn't just about cashing a check once a month. When you self-manage, you're wearing multiple hats at once.
- You're the marketing guru: Crafting eye-catching listings, snapping professional-quality photos, and coordinating all the showings.
- You're the detective: Running background checks, meticulously verifying income, and chasing down references—all while navigating the minefield of Fair Housing laws.
- You're the bookkeeper: Diligently tracking every cent of income and expenses, handling security deposits according to California's strict rules, and getting everything squared away for tax time.
- You're the repair coordinator: Answering tenant maintenance calls at all hours and having a trusted network of insured and reliable vendors on speed dial.
Here's the gut-check question: Do you truly have the time, and more importantly, the temperament for all this? If you live across the state, have a demanding career, or just know deep down that dealing with tenant drama will drive you crazy, self-management can get overwhelming, fast.
The Case for Professional Property Management
Hiring a property manager is really an investment in your own peace of mind. You're trading a percentage of your rental income for deep industry expertise and, frankly, freedom from the daily grind of being a landlord. A good management company is your professional buffer, handling everything from collecting rent to managing those inevitable emergency repairs.
This professional layer is quickly becoming more of a necessity than a luxury. We're seeing a huge shift in the rental market, moving away from the casual, handshake-deal style of self-management toward more professional, tech-forward services. This is especially true as tenants' expectations get higher and the legal landscape gets more complicated. Choosing a full-service or placement-only model isn't just about convenience anymore; it’s a strategic move to meet high screening standards and shield yourself from legal risk. You can dig into more on this industry trend and its growth to see where things are headed.
A professional manager is a game-changer, especially for:
- Out-of-State Owners: Trying to manage a property from hundreds of miles away is a recipe for disaster.
- Busy Professionals: If your time is more valuable when focused on your career, outsourcing makes perfect financial sense.
- Owners with Multiple Properties: Once you start juggling several rentals, it becomes a full-time job.
Finding the Right Fit: Two Management Models
Property management isn't a one-size-fits-all service. At Edinhart, we get that every owner is different. That’s why we offer a couple of distinct service models. Figuring out which one clicks with your needs is key.
1. Placement-Only Service
Think of this as the perfect hybrid solution. It’s for the landlord who feels comfortable with the day-to-day stuff but wants an expert to handle the most critical part: finding and placing a top-tier tenant. This service is all about getting you started on the right foot—we handle the marketing, showings, intensive applicant screening, and drafting a rock-solid lease. Once the tenant has the keys, we hand the reins back to you.
2. Full-Service Monthly Management
This is the "set it and forget it" option. A full-service manager is your partner for the long haul, handling everything from A to Z. It includes all the placement tasks and then continues with rent collection, maintenance coordination, all tenant communication, detailed financial reporting, and more. It’s the go-to choice for anyone who wants the financial benefits of owning a rental property without any of the hands-on work.
Property Management Decision Checklist: Edinhart Services
Deciding between full-service management and a placement-only service really comes down to your lifestyle, experience, and how involved you want to be. This checklist breaks down the responsibilities to help you see which Edinhart service is the best fit for your landlord style.
| Feature / Responsibility | Full-Service Monthly Management | Placement-Only Service |
|---|---|---|
| Marketing & Advertising | ✅ Included | ✅ Included |
| Professional Photography | ✅ Included | ✅ Included |
| Tenant Showings | ✅ Included | ✅ Included |
| In-Depth Tenant Screening | ✅ Included | ✅ Included |
| Lease Drafting & Signing | ✅ Included | ✅ Included |
| Move-In Inspection | ✅ Included | ✅ Included |
| Ongoing Rent Collection | ✅ Included | ❌ Owner's Responsibility |
| Maintenance Coordination | ✅ Included | ❌ Owner's Responsibility |
| 24/7 Emergency Calls | ✅ Included | ❌ Owner's Responsibility |
| Tenant Communication | ✅ Included | ❌ Owner's Responsibility |
| Lease Enforcement & Notices | ✅ Included | ❌ Owner's Responsibility |
| Financial Reporting | ✅ Included | ❌ Owner's Responsibility |
| Move-Out Process & Evictions | ✅ Included | ❌ Owner's Responsibility |
Whether you want a partner for the entire journey or just an expert to get you started, understanding these differences will ensure you make a choice that gives you confidence and peace of mind.
Got Questions About Renting Your California Home?
Even with a great game plan, the thought, "I want to rent out my home," usually brings up a million little questions. Diving into the world of property management for the first time can feel like learning a new language. We put this section together to give you clear, no-nonsense answers to the most common questions we hear from new landlords right here in California.
Think of this as your quick-reference guide. We’re tackling the real-world uncertainties that pop up as you make the switch from homeowner to landlord, armed with both legal know-how and years of on-the-ground experience.
Do I Need a Different Kind of Homeowners Insurance?
Yes, you absolutely do. This is one of the most critical steps, and it's amazing how often it gets missed. A standard homeowners policy is written for a property you live in. The moment a tenant moves in, the risks change dramatically, and your current policy will almost certainly not cover you if something goes wrong.
You need to get a landlord insurance policy, sometimes called a dwelling policy. It's specifically designed for rental properties and covers a different set of risks.
- Property Damage: This protects the actual structure of your house from disasters like a fire or a major storm.
- Liability Protection: This is huge. It covers you if a tenant or their guest gets hurt on your property and decides to sue.
- Loss of Rental Income: If a covered event (like that fire) makes your home unlivable, this can pay you for the lost rent while the property is being repaired.
Expect a landlord policy to cost about 25% more than what you're paying now for homeowners insurance. It's a non-negotiable cost of doing business. Skipping this could mean a denied claim, leaving you on the hook for thousands in damages.
How Long Does It Take to Find a Good Tenant?
That's the million-dollar question, isn't it? The real answer is: it depends. The timeline is heavily influenced by market conditions, how you've priced the home, its condition, and your marketing efforts. In a balanced market like Fresno, a sharp-looking, well-priced home should land a qualified tenant within 2 to 4 weeks.
Here’s a breakdown of what speeds things up or slows them down:
- Pricing: If you price your home too high, it will just sit there. A property priced competitively based on solid market data will always move faster.
- Condition: All that "rent-ready" prep work we talked about earlier really pays off here. A clean, updated, and well-maintained home attracts more applicants—and better ones, too.
- Time of Year: The rental market is seasonal. Spring and summer are the hot seasons with tons of demand. Things tend to quiet down quite a bit around the holidays and in the middle of winter.
Minimizing your vacancy time starts with a powerful marketing strategy. Professional photos, a great description, and getting your listing on all the major rental sites are essential to getting your home rented quickly.
Can I Refuse to Rent to Someone with Pets?
This is a tricky one. Generally speaking, you are allowed to have a "no pets" policy for your rental in California. You can legally turn down an applicant just because they have a dog or a cat.
But—and this is a big one—you have to understand the major exception: service animals and emotional support animals (ESAs). Under the Fair Housing Act, these animals are not considered pets. They are assistance animals that are medically necessary for a person with a disability.
- You cannot charge a "pet deposit" or "pet rent" for a legitimate assistance animal.
- You cannot deny an otherwise qualified applicant because they have a verified service animal or ESA, even with a strict no-pets policy in place.
It's so important to handle these requests carefully and by the book to avoid a costly discrimination lawsuit. You are allowed to request a letter from a medical professional verifying the need for the animal, but the law is very specific about what you can and cannot ask.
How Should I Handle Late Rent Payments?
Dealing with late rent is just part of being a landlord; it's going to happen. The key is to have a crystal-clear, legally sound process that you follow every single time with every single tenant. No exceptions.
Your lease agreement needs to spell everything out:
- The exact date rent is due (e.g., the 1st of the month).
- The specific late fee amount and when it kicks in (California has laws limiting how much you can charge).
- The ways a tenant is allowed to pay their rent.
The moment rent is late, your process should start. This usually begins with a polite but firm reminder. If the rent still doesn't show up, the next step is serving a formal, written "3-Day Notice to Pay Rent or Quit." In California, this is the official legal document required before you can even think about starting an eviction.
Being firm, fair, and consistent is the best way to manage your property. It sets a professional tone from day one and makes it clear that paying rent on time isn't optional.
Navigating these questions is much easier with an expert partner by your side. Edinhart Realty and Property Management offers both Placement-Only and Full-Service Management to give you the exact level of support you need. Let us help you manage your property with confidence by visiting us at https://edinhart.com.


