

So, you're thinking about renting out your condo? It's a fantastic way to build some long-term wealth and get some extra cash flowing each month. But let's be real—it's not as simple as just finding someone to move in. To do it right and turn your property into a stress-free asset, you need a solid game plan.
Think of yourself as a business owner now. From the moment you decide to rent, every step you take matters. This guide is your roadmap, designed to walk you through the entire process, from dealing with the HOA to finally handing over the keys. We’ll break it all down so you can sidestep the common mistakes that often trip up new landlords.
Your Roadmap to Becoming a Profitable Condo Landlord
The whole journey, from start to finish, rests on a few key pillars. Getting these right from the beginning will save you a world of headaches down the road.
Here's a quick look at the major milestones you'll hit:
- Due Diligence: First things first, you've got to dig into your condo association's rules on rentals and get familiar with local landlord-tenant laws. This isn't the fun part, but it's non-negotiable.
- Getting Market-Ready: This is where you get your unit looking its best with smart touch-ups and then crunch the numbers to set a competitive rental price based on what's happening in the market.
- Finding Your Tenant: You'll need to create a listing that really pops and then have a rock-solid screening process to find someone reliable.
- The Nitty-Gritty: This involves drawing up a strong lease that protects everyone and managing a smooth, well-documented move-in day.
To give you a clearer picture, here’s a breakdown of how these stages fit together.
Condo Rental Process At a Glance
This table simplifies the journey, outlining what needs to happen at each point and why it's important for your success as a landlord.
| Stage | Key Action | Primary Goal |
|---|---|---|
| Phase 1: Foundation | Review HOA bylaws & local laws. | Ensure full legal compliance before you start. |
| Phase 2: Preparation | Make necessary repairs and set the rent price. | Maximize your unit's appeal and profitability. |
| Phase 3: Marketing | List the property with pro photos and a great description. | Attract a large pool of qualified applicants. |
| Phase 4: Screening | Conduct background checks, credit reports, and reference calls. | Select a responsible and reliable tenant. |
| Phase 5: Legal & Move-In | Sign a comprehensive lease and document property condition. | Establish clear expectations and protect your asset. |
| Phase 6: Management | Collect rent, handle maintenance, and manage the tenancy. | Maintain a positive tenant relationship and cash flow. |
Seeing it laid out like this helps put the entire process into perspective, turning a big task into a series of manageable steps.
DIY Landlord or Professional Management?
Right out of the gate, you'll face a big decision: are you going to manage this yourself, or bring in a professional? There’s no single right answer—it really comes down to how much time you have, your experience level, and how hands-on you want to be.
A successful rental strategy isn’t just about finding a tenant; it’s about finding the right tenant and building a system that protects your investment for the long haul. This decision fundamentally shapes your role as a landlord.
This choice is a classic trade-off. You can save money on management fees by doing it all yourself, or you can invest in professional help for peace of mind and expert handling.
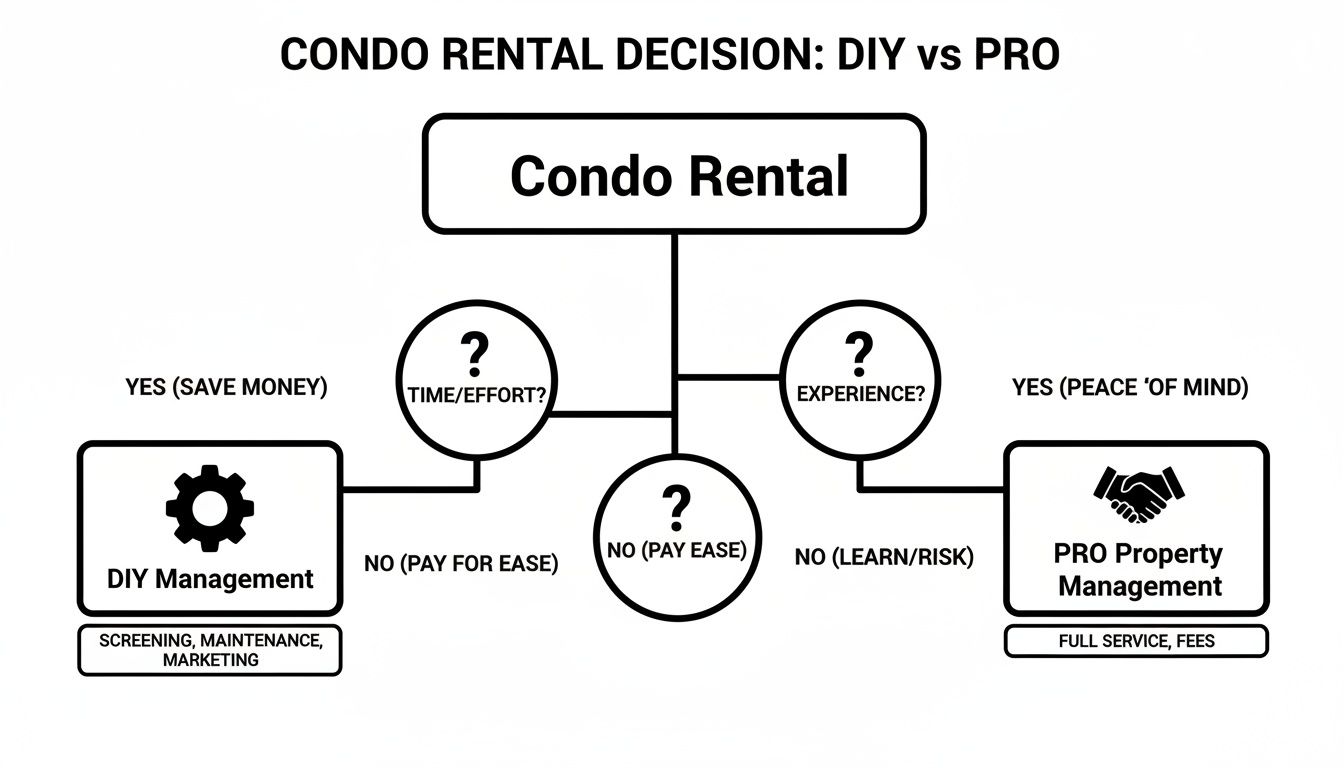
For a lot of owners, a Placement-Only service strikes the perfect balance. We handle the heavy lifting of marketing and finding you a top-notch tenant, and then you take over the day-to-day management. It's the best of both worlds.
First Things First: Getting Clear on HOA Rules and Local Rental Laws
Before you even start thinking about listing photos or what to charge for rent, pump the brakes. The very first, non-negotiable step is a deep dive into the rules and regulations governing your property.
Honestly, this is where many first-time condo landlords get tripped up. Skipping this homework can land you in a world of hurt—think hefty fines from your association, legal battles, and even the nightmare scenario of having to evict a tenant you just placed.
Your compliance journey begins with your Homeowners Association (HOA). Those governing documents—usually called bylaws or Covenants, Conditions, and Restrictions (CC&Rs)—are the law of the land in your community. You need to get your hands on the latest version and read the section on rentals with a magnifying glass.
Decoding Your HOA's Stance on Rentals
Don’t just give the documents a quick skim. You’re hunting for specific clauses that can make or break your rental plans. Some HOAs are landlord-friendly, but many are actively trying to limit rentals to maintain a certain community feel.
Here’s exactly what to look for:
- Rental Caps: A big one. Many associations cap the percentage of units that can be rented out at one time. If your building has hit its cap, you’ll likely be put on a waiting list, which could take years.
- Minimum Lease Terms: To avoid a revolving door of residents, it’s common for HOAs to mandate 6-month or 12-month minimum lease terms. This immediately rules out any short-term rental ambitions.
- Tenant Approval Process: Does the HOA board need to approve your tenant? They might require you to submit the full application for their review, giving them veto power and adding days or weeks to your timeline.
- Owner Occupancy Requirements: Some bylaws state that an owner must physically live in the unit for a set period—often one or two years—before they earn the right to rent it out.
Getting a firm grip on these rules is crucial. For a more detailed breakdown of what’s typical, our guide on whether you can rent condos digs deeper.
I’ve seen it happen time and again: a new landlord assumes they can rent their unit because a neighbor is doing it. But rules change, caps get hit, and what was allowed last year might be forbidden today. Always, always verify the current rules for yourself directly with the HOA.
Looking Beyond the HOA: City and County Rules
Okay, so your HOA gives you the green light. Great! But you’re not done yet. Your city or county has its own separate rulebook for landlords, and ignorance is no excuse.
You’ll need to do a little research on what’s required in your specific area. Many cities, for example, require landlords to get a business license or formally register their rental property. This usually involves an application and a fee.
On top of that, local jurisdictions often have health and safety codes your condo must meet. This could mean a formal inspection to check for things like properly placed smoke detectors, carbon monoxide alarms, and secure window locks. These aren't just bureaucratic hoops; they’re about ensuring a safe living space for your tenant.
Understanding the Financial and Tax Side
Local laws also have a lot to say about the money. In recent years, many cities and resort towns have cracked down on condo rentals. It’s not uncommon to see associations enforcing 30 to 90-day minimum lease terms, and some even require owners to live in the unit for 12–24 months before leasing is allowed.
Then there are the taxes. If you’re in an area popular with tourists, you may be on the hook for collecting and remitting transient occupancy taxes, which can range anywhere from 5% to 14% of the gross rent. You can dig into more data on these kinds of trends over at airdna.co.
As the landlord, it’s 100% your responsibility to understand and handle these tax obligations. Messing this up can lead to back taxes, penalties, and interest payments that can completely wipe out your profit. This due diligence isn’t the most exciting part of the process, but it’s the absolute bedrock of renting your condo out the right way.
Getting Your Condo Rent-Ready and Priced Right
Once you've navigated the legal and HOA side of things, it’s time for the fun part: turning your condo into the hottest rental on the market. This is more than just a quick clean-up. We're talking about a strategic approach to make your property shine, attract top-tier tenants, and command the best possible rent.
Think of it this way: your condo is now a product. And in a competitive market, first impressions are everything—especially online, where a renter's search begins.
Smart Upgrades That Actually Pay Off
You don't need to gut the place to make a big impact. The smartest move is to focus on high-return, low-cost improvements that tenants really notice. Little things like worn-out fixtures or dated paint can send the wrong message, suggesting the property isn't well cared for.
Here are a few of the most effective updates we recommend to our clients:
- Fresh Paint is a Must: A new coat of paint in a neutral color—think soft grays, warm whites, or greige—works wonders. It instantly makes the space feel brighter, bigger, and gives tenants a blank canvas to imagine their own life in.
- Swap Out Fixtures and Hardware: It's amazing what a difference new cabinet pulls, doorknobs, and modern light fixtures can make. This is a quick and relatively cheap facelift that elevates the whole feel of the condo.
- Deep Clean Everything: This is non-negotiable. Go beyond your usual tidying up and hire a professional crew. They'll hit the carpets, windows, grout, and appliances, leaving the unit sparkling. A professionally cleaned condo is a huge plus for prospective tenants.
- Tackle the Small Repairs: That leaky faucet, the constantly running toilet, those nail holes in the wall? Fix them. These minor issues can look like major red flags to a detail-oriented renter during a walkthrough.
The goal here is "rent-ready." You're not renovating for your own taste; you're creating a clean, modern, and functional space that will appeal to the widest possible audience of quality renters.
Why Professional Photos Are a Game-Changer
Let's be blunt: in today's rental market, your listing photos are your most powerful marketing tool. Grainy, poorly-lit pictures taken on your phone will get your listing ignored, no matter how fantastic the condo is in person.
Investing in a professional real estate photographer is one of the best decisions you can make. They know how to use lighting, angles, and composition to make every room look spacious, bright, and inviting. It signals to the market that this is a premium property managed by a serious landlord.
Want to stand out even more? Consider adding a virtual tour or a video walkthrough. These tools give potential tenants a genuine feel for the condo's layout and flow before they even schedule a showing, which saves you from wasting time on tours with people who aren't a great fit.
Your rental listing is a marketing campaign, and your photos are the headline ad. High-quality visuals don't just attract more applicants—they attract better-quality applicants who are willing to pay top dollar.
Nailing the Perfect Rental Price
Pricing your condo is a delicate dance. Go too high, and you're looking at a long and costly vacancy. Go too low, and you're leaving money on the table month after month. The only way to get it right is with a data-driven approach.
This is done through a comparative market analysis (CMA), which is just a fancy way of saying you need to see what similar condos in your building and neighborhood are renting for. Look for units with the same number of bedrooms, bathrooms, and comparable square footage and amenities.
Pay close attention to how long other listings have been on the market. If a similar unit has been sitting empty for over a month, it's a good sign it's overpriced. If places are getting snapped up in under a week, you know the market is hot. For a more in-depth look, our guide on how to determine rental price walks you through the entire process.
Calculating Your True Profitability
With a target rent in mind, it's time to crunch the numbers and see what your actual profit will look like. The gross rent is just the starting point. Most landlords aim for an annual gross rental yield between 3% and 8%, but your real profit comes after deducting all operating costs, which can easily eat up 20% to 40% of your rental income.
Here's a quick look at the expenses you absolutely must account for:
- Mortgage (Principal & Interest)
- Property Taxes
- Landlord's Insurance Policy
- Monthly HOA Dues
- Vacancy Fund (Set aside 5-10% of annual rent for this—it's a lifesaver)
- Maintenance & Repair Fund (Budget another 5-10%)
- Property Management Fees (If you hire a pro)
Once you subtract these costs from your expected annual rent, you're left with your net operating income. That's the number that truly tells you how your investment is performing.
Marketing Your Rental and Screening for the Right Tenant
Alright, your condo looks fantastic and you've landed on a smart price. Now comes the most critical part: getting the word out to find the perfect person to call it home. This isn't just about filling a vacancy quickly; it’s about protecting your investment for the long haul.
A well-executed marketing and screening plan is probably the single biggest factor in whether you have a great experience as a landlord or a stressful one.
Think of your listing description as a story, not just a spec sheet. Anyone can list "2 beds, 2 baths." You need to sell a lifestyle. Is your condo the ideal spot for a young professional who wants to be in the heart of the action? Or is it a peaceful retreat with a killer balcony for sipping morning coffee? Use language that paints a vivid picture.
Be sure to call out the specific features that make your place special—the recently renovated kitchen, the unbelievable convenience of an in-unit washer and dryer, or the building’s awesome fitness center. These are the details that grab attention and justify your asking price in a sea of other listings.
Creating a Listing That Gets Clicks
Once you’ve crafted the perfect description, it’s time to get it in front of the right eyeballs. While posting on social media might get you some inquiries, the most serious and qualified renters are hunting on the major real estate sites.
Your marketing plan should include a few key elements:
- Top-Tier Listing Sites: Put your efforts into platforms like Zillow, Trulia, and Realtor.com. They push your listing out to a massive network, reaching people who are actively looking for their next home.
- Professional Photography: We can't say it enough—great photos are non-negotiable. It's the first thing a prospective tenant sees, and it can make or break their interest in a split second.
- Video Walkthroughs: A quick video tour can work wonders for engagement. Learning how to create video ads that actually convert is a game-changer, helping you pre-qualify leads and save a ton of time on showings for people who aren't a good fit.
This multi-channel approach helps ensure you aren't just getting a flood of applicants, but the right applicants.
The Art and Science of Tenant Screening
Marketing gets people to raise their hand; screening is how you protect your property. A thorough, consistent, and legally sound screening process is your best defense against late rent, property damage, and the nightmare of eviction. Whatever you do, don't rush this part just to get someone in quickly.
Your screening should be a methodical process where every single applicant is measured against the same objective standards. This isn’t just good business—it’s essential for complying with Fair Housing laws.
The quality of your tenant will determine the quality of your experience as a landlord. A great tenant pays on time, cares for your property, and communicates proactively. A bad tenant can turn your investment into a nightmare. Screening is your filter.
It all starts with a detailed rental application that gathers everything you need, from work history to references from previous landlords. From there, you'll dig a little deeper.
Our team at Edinhart has a finely-tuned system, but here are the absolute must-haves you need to cover:
- Credit Report: You’re looking for more than just a score. You want to see a solid history of on-time payments and a reasonable debt-to-income ratio. It’s a clear snapshot of their financial responsibility.
- Background Check: This uncovers any relevant criminal history. The key here is to have your criteria set in stone and apply it consistently to every single applicant to remain compliant.
- Income Verification: The industry rule of thumb is that a tenant’s gross monthly income should be at least 3 times the rent. Always confirm this with recent pay stubs or an official offer letter.
- Reference Checks: Actually call their current and past landlords. Ask the important questions: Did they pay on time, every time? How did they maintain the property? And the million-dollar question: Would you rent to them again?
This whole process can feel like a full-time job, which is why many owners bring in a professional. For a deep dive into our best practices, check out our guide on how to screen tenants. Whether you use our Placement-Only service or handle it yourself, getting this stage right is the key to your success.
Crafting the Lease and Managing Your Property
You found the perfect tenant, and they flew through the screening process. Great! Now, the real work begins. It’s time to shift gears from *finding* a renter to actually *managing* the tenancy. This part is all about locking things down with a solid lease and setting up professional, clear systems for everything that comes next, from move-in day chaos to late-night maintenance calls.
A well-written lease is more than just a piece of paper; it's the foundation of your entire landlord-tenant relationship. It’s a binding legal contract that clearly lays out everyone's rights and responsibilities. Getting this document right from the start is your best defense against future misunderstandings and protects your investment by creating a clear roadmap for any issue that might pop up down the line.
Building an Ironclad Lease Agreement
Your lease needs to be detailed, specific to your property, and completely in line with California and local landlord-tenant laws. It can be tempting to just grab a generic template online, but for a condo, that's a mistake. You have to account for things like HOA rules, which absolutely must be included.
Here are the non-negotiable clauses every lease should have:
- Rent and Fees: Spell out the exact monthly rent, the due date (e.g., the 1st of the month), and any grace period. Be just as clear about late fees—the amount and when they apply—making sure they comply with local laws.
- Security Deposit: State the security deposit amount, where you'll hold it, and the specific conditions for its return. You’ll want to reference California's laws on the timeline for returning it after the tenant moves out.
- Maintenance Responsibilities: Draw a clear line in the sand. Landlords typically handle the big stuff like appliances, plumbing, and HVAC. Tenants are usually on the hook for general upkeep and small things like changing a lightbulb.
- HOA Rules and Regulations: This is a huge one for condos. Attach the full HOA rulebook as an addendum to your lease. Then, include a clause where the tenant acknowledges they've received, read, and agreed to follow every single rule. This simple step makes an HOA violation a direct breach of the lease.
Pulling together a lease can feel overwhelming. Using comprehensive resources like free rental agreement templates can give you a solid starting point. Just remember to customize it meticulously for your specific unit and local regulations.
The Move-In Day Checklist
The first day sets the tone for the rest of the tenancy. When you handle the move-in process smoothly and professionally, it shows your new tenant that you're organized and serious. More importantly, it creates a crucial baseline record of the condo's condition.
Your most powerful tool on move-in day is a detailed Move-In Condition Report. This isn't something to rush. You and the tenant should walk through the unit together, room by room, documenting the state of everything—walls, floors, appliances, fixtures, you name it.
Never, ever skip the move-in inspection. A detailed checklist, signed by both of you and backed up with photos, is the single best piece of evidence you'll have if a security deposit dispute ever comes up. It removes all the "he said, she said" drama.
Take photos. Lots of them. Get video, too. Document every little scuff, scratch, or ding, no matter how minor it seems. Once you’re both satisfied, you and the tenant should sign and date the report. Make sure you both get a copy. This simple act protects everyone and ensures a fair process when it's time to move out.
Self-Management vs. Hiring a Professional
With the lease signed and the tenant settled in, you've hit a major fork in the road. Are you going to manage this property yourself, or is it time to hire a pro? The right answer really depends on your lifestyle, how close you live to the condo, and frankly, how willing you are to be on the front lines of landlording.
This decision is also influenced by whether you're renting your condo as a long-term rental or a short-term vacation spot. Long-term rentals generally maintain a steady 90%–95% annual occupancy, with management fees in the 6%–12% range. Short-term rentals are a different beast, with more seasonal occupancy between 40%–75% and much higher operating costs, including hefty management fees of 15%–30% of the booking revenue.
Let's break down your two main options:
| Aspect of Management | DIY Landlord (Self-Management) | Edinhart's Professional Management |
|---|---|---|
| Rent Collection | You're the one chasing down rent and dealing with late payments. | We handle automated collections and enforce late fee policies professionally. |
| Maintenance Calls | You get that 2 a.m. call about a leaking water heater or a backed-up sink. | Tenants call our 24/7 line, and we dispatch our vetted, reliable contractors. |
| Tenant Communication | You're the direct contact for every question, complaint, and random issue. | We act as the professional buffer, managing all communication for you. |
| Cost | You save on management fees but pay with your own time, energy, and stress. | A small percentage of the rent buys you complete peace of mind. |
For many condo owners, our Full-Service Management is the perfect fit. It effectively turns what could be a part-time job into a truly passive investment. At Edinhart, we take care of everything—from the routine maintenance checks to the middle-of-the-night emergencies—so you can enjoy the financial rewards of your property without any of the operational headaches.
Common Questions About Renting Your Condo
Even the most buttoned-up plan hits a few speed bumps. As you start the process of becoming a condo landlord, questions are going to come up—it’s just part of the deal.
We get calls about this stuff all the time. To help you get ahead of the curve, we’ve put together a few of the most common questions we hear from first-time landlords, with clear answers to keep you moving forward.
How Much Can I Realistically Earn From Renting My Condo?
The rent check you deposit isn't pure profit. The real money is what’s left after every single bill is paid, and that magic number is called your Net Operating Income (NOI). This is the figure that actually tells you if your condo is making you money.
To figure it out, you start with your Gross Potential Rent—what you'd make if the unit was rented every day for a year. Then, you start subtracting.
- HOA Dues: This is a big one for condos, a non-negotiable monthly expense.
- Property Taxes: Your yearly tax bill, just broken down into monthly chunks.
- Landlord Insurance: You absolutely need a specific policy for rentals. More on that below.
- Maintenance Fund: Smart landlords stash away 5-10% of the monthly rent for those inevitable repair calls.
- Vacancy Fund: Don't assume 100% occupancy. Plan on the unit being empty for about a month a year by setting aside 8-10% of the rent.
What's left after all that? That's your NOI. That's your real cash flow.
What Kind of Insurance Do I Need for a Rental Condo?
This is a critical detail that trips up a lot of new landlords. Your standard homeowner's policy (the HO-6) is officially void the second a tenant moves in. That policy is only for owner-occupied units. When your risk changes, your coverage has to change with it.
You’ll need to switch over to a dedicated landlord insurance policy (sometimes called a DP3 or Dwelling Fire policy). It’s built specifically for rentals and gives you three layers of protection you can't afford to skip.
Your insurance is your financial safety net. Skimping here is one of the riskiest decisions a landlord can make. A single uncovered incident could wipe out years of profit.
A solid landlord policy should always include:
- Property Damage Protection: This covers the physical unit itself—the walls, floors, and fixtures—from things like fire or a major leak.
- Liability Coverage: If a tenant or their guest gets hurt on the property and you're found responsible, this protects you from financial ruin.
- Loss of Rent Coverage: If a fire or other covered event makes your condo unlivable, this coverage replaces that lost rental income while you’re making repairs.
On top of your own policy, you should always, always require your tenants to carry their own renter's insurance. It protects their stuff and gives them their own liability coverage, which adds another valuable layer of protection for everyone.
Should I Rent My Condo Furnished or Unfurnished?
This decision completely changes your target market, your potential rent, and your day-to-day responsibilities. There’s no right or wrong answer—it all comes down to your specific building, your city’s rental market, and your goals.
Offering a furnished unit can let you charge a premium, sometimes 15-20% more. It’s a huge draw for people on corporate relocations, traveling nurses, or anyone new to the area who doesn’t want to deal with buying and moving furniture. The trade-off? You’re on the hook for buying, maintaining, and eventually replacing every single item in that unit.
An unfurnished condo, on the other hand, is the standard for the long-term rental market. You’ll attract tenants who see themselves staying for a year or more and want to bring their own belongings to make the place feel like home. This route means way lower upfront costs for you and zero responsibility for worn-out couches or broken coffee tables.
How Should I Handle Maintenance Requests and Emergencies?
A clear, documented system for handling repairs is non-negotiable. It keeps your tenants happy (which means they’re more likely to renew) and protects the physical condition of your biggest asset.
For the day-to-day stuff—a leaky faucet, a squeaky door—set up an online portal or a dedicated email. This gives you a written, time-stamped record of every request.
Emergencies are a totally different ballgame. A burst pipe, a dead furnace in January, or a major electrical failure needs to be handled now. Before you even list the property, you should have a pre-vetted list of trusted 24/7 contractors: a plumber, an electrician, and an HVAC tech you can call at 2 a.m. Give that list to your tenants. Empowering them to make that first call can be the difference between a small problem and a full-blown, wallet-draining catastrophe.
Getting these details right is what makes the difference between a successful investment and a constant headache. At Edinhart Realty and Property Management, we manage this entire process, turning your condo into a truly passive, profitable asset. Find out how we can give you complete peace of mind at https://edinhart.com.


