

If you own a rental property, getting ready for tax season really comes down to one thing: staying organized all year long. It’s not about some last-minute scramble in April. It’s about building simple habits like separating your finances, finding a record-keeping system that you’ll actually stick with, and having all your important documents—leases, mortgage statements, big repair receipts—ready to go.
Get this foundation right, and you’ll turn tax time from a chaotic nightmare into just another part of running your business.
Getting Started Without The Stress
Honestly, the key to a calm tax season isn't some complicated secret. It’s just about being proactive. Too many landlords push it off, only to find themselves frantically digging through shoeboxes for receipts and missing out on valuable deductions. The best way to avoid that pain is to set up a solid system from the very beginning.
Putting good financial habits in place is the first step. You can find some easy tips to organize your finances that will help you get your records in order and build a strong foundation for tax time.
Separate Your Finances Immediately
This is your first move, and it's non-negotiable. Go open a separate bank account and credit card that are used only for your rental property. I can't stress this enough. This one action is your single best defense if you ever face an audit, creating a crystal-clear trail of all your income and expenses.
When every rent check, every trip to Home Depot, and every plumber’s bill runs through that dedicated account, there’s no room for error. You completely avoid the messy situation of commingling personal and business funds, making it incredibly simple to prove your deductions and see exactly how your investment is performing.
Pro Tip: We’ve all done it—paid for a rental expense with a personal card by mistake. Don’t just let it slide. The minute it happens, transfer the exact amount from your business account back to your personal one. Make a quick note of the transaction and what it was for. This keeps your books clean and accurate.
Choose a Record-Keeping System That Works For You
Next, you need to decide how you're going to track everything. The "best" system is simply the one you'll use consistently. There’s no need to overcomplicate things.
- Simple Spreadsheets: If you just have a property or two, a basic Excel or Google Sheet can work perfectly. Just set up columns for the date, what the expense was, the category (like "Repairs" or "Utilities"), and the amount.
- Dedicated Software: For landlords managing several properties or who just want more automation, software is a lifesaver. Tools like QuickBooks or Stessa can link directly to your business bank account and pull in transactions automatically, which saves a massive amount of time.
It doesn’t matter if you choose a simple spreadsheet or sophisticated software. The goal is the same: to have one central place for every single piece of financial data. This habit is the bedrock of a smooth tax season.
Mastering Your Income and Expense Tracking
Let's be honest, accurate financial records are the absolute backbone of a successful rental business. If you want a stress-free tax season and a clear view of your investment's health, you have to get this right. Mastering how to prepare for tax season when you own a rental means meticulously tracking every single dollar coming in and going out. It's so much more than just logging rent checks.
First things first, you need to understand what the IRS actually counts as rental income. Many new landlords are surprised to find it's a much broader category than they initially thought.
- Advance Rent: If a tenant pays you in December for January's rent, that money is income in the year you received it—December.
- Lease Cancellation Payments: That fee you collect when a tenant needs to break their lease early? Yep, that's rental income.
- Tenant-Paid Expenses: Say a tenant pays a water bill or a minor repair that's technically your responsibility. That amount counts as income for you, but don't worry—you can then deduct it as a rental expense.
- All Those Fees: Application fees, pet fees, and late fees all get added to your gross rental income.
Drawing The Line Between Repairs and Improvements
One of the biggest financial tripwires for landlords is confusing a repair with a capital improvement. Getting this wrong can lead to inaccurate deductions and, worse, a headache with the IRS.
A repair is basically maintenance. It's an expense that keeps your property in good, working condition but doesn't add significant value or extend its life. Think of fixing a leaky faucet or replacing a single broken windowpane. These costs are fully deductible in the tax year you pay for them.
A capital improvement, however, is a major upgrade. We're talking about things that add substantial value, prolong the property's life, or adapt it to a new use. Replacing the entire roof, installing a new HVAC system, or adding a deck are classic examples. You can't deduct these big-ticket items all at once. Instead, you "capitalize" them, meaning you recover the cost over time through depreciation.
This distinction is non-negotiable for accurate tax filing. A $400 plumbing repair is a current-year expense. A $15,000 new roof is an asset you'll deduct a piece of for years to come. Getting this right on your Schedule E is essential.
The IRS is crystal clear: rental property owners must report all income and deduct all eligible expenses. This isn't just a good idea; it's a requirement. Meticulous documentation is your best defense against costly errors or an audit. You can get the full rundown on the IRS website for more details on their requirements.
Build a Year-Round Tracking Habit
Your record-keeping can't be a mad dash in March. It needs to be a continuous, year-round habit. Whether you use a simple spreadsheet or dedicated software like Stessa or Buildium, your system has to capture the details.
Having a checklist of what to keep is half the battle. This table breaks down the essentials you absolutely must track.
Essential Record-Keeping Checklist for Rental Properties
| Document Category | Specific Examples | Why It's Important |
|---|---|---|
| Income Records | Bank deposits, digital rent payment confirmations, fee logs, copies of checks | Provides a clear, auditable trail of all money coming in from the property. |
| Expense Receipts | Invoices from contractors, receipts from Home Depot, utility bills, property tax statements | This is your essential proof for every single deduction you claim on your tax return. No receipt, no deduction. |
| Travel Logs | Mileage records for property visits, supply runs, or meeting contractors (dates, miles, purpose) | Substantiates travel expense deductions, a commonly overlooked but valuable write-off for landlords. |
| Legal & Financial | Lease agreements, mortgage statements, insurance policies, closing documents | Documents the key legal and financial terms that directly impact your tax obligations and depreciation schedule. |
By diligently filing away every receipt and logging every transaction as it happens, you'll have everything you need when it’s time to file. This systematic approach turns tax prep from a frantic scavenger hunt into a calm review of well-organized data. It’s a game-changer.
Uncovering Every Landlord Tax Deduction
Leaving money on the table is one of the most common—and most expensive—mistakes landlords make. It’s easy to track the obvious expenses like mortgage interest and insurance, but minimizing your tax bill means digging deeper. Understanding every single available deduction is a core part of preparing for tax season when you own a rental property.
Believe me, failing to claim every legitimate write-off adds up fast. One survey found that a staggering 70% of U.S. rental property owners miss at least one major deductible expense each year. This leads to some serious overpayments to the IRS. The most frequently overlooked deductions? Depreciation, travel, and legal fees.
The Power of Depreciation
Depreciation is, without a doubt, the most powerful tax deduction for landlords. It’s also the one that's most often misunderstood or missed entirely.
The concept is simple: the IRS allows you to deduct a portion of your property’s cost (the building itself, not the land) over its useful life. For residential rentals, this period is 27.5 years.
Think of it this way—even as your property’s market value goes up, the IRS lets you write off its gradual wear and tear. This is a non-cash expense, meaning it can create a paper loss that dramatically reduces your taxable rental income without you having to spend an extra dime that year. It's a game-changer.
Beyond the Obvious Deductions
While you’re almost certainly tracking the big-ticket costs, a lot of smaller but equally valid expenses get forgotten in the shuffle. Getting granular here can lead to substantial savings.
- Travel Expenses: Did you drive to your property to show it to a prospective tenant, meet a contractor, or just drop off supplies? That mileage is deductible. Keep a simple log of the date, mileage, and purpose for each trip. It adds up.
- Home Office Deduction: If you have a specific, exclusive area of your home dedicated to managing your rental business, you might be able to claim a home office deduction. This can cover a portion of your utilities, insurance, and even your home's depreciation.
- Legal and Professional Fees: Any money you spend on lawyers, accountants, or property managers is fully deductible. This includes the cost of drafting a lease, handling an eviction, or hiring someone to prepare your Schedule E tax form.
Engaging legal counsel for tenant issues can be a deductible expense. Navigating complex situations requires a firm grasp of local regulations, so it's wise to understand the specifics of landlord-tenant law in California or your state to ensure compliance and protect your investment.
Properly accounting for all these varied expenses is what separates a savvy investor from one who leaves cash on the table for the IRS. To really maximize what you can save, it pays to dive deeper into the specific tax deductions for landlords.
Every single dollar you can legitimately deduct directly boosts your cash flow and makes your rental property that much more profitable.
Deciding Between DIY Taxes and Hiring a Pro
One of the biggest crossroads you’ll hit as a landlord is deciding whether to tackle your taxes yourself or bring in a professional. There’s no single correct answer here; it really boils down to the complexity of your rental business. Getting this choice right can save you a lot of money and headaches down the road.
For some landlords, especially those with a single, straightforward rental, using tax software can work out just fine. If your income and expense records are crystal clear, you might feel comfortable handling it. Modern software guides you through Schedule E, but it makes one big assumption: that you already know what numbers to plug in and, more importantly, why.
When to Call in a Professional
As your portfolio grows, so does the complexity. Certain situations should be immediate red flags, telling you it’s time to invest in expert help. If your rental business involves any of the following, a DIY approach could end up costing you far more than you save:
- You own multiple properties. Juggling the income, expenses, and depreciation for several properties gets complicated—fast.
- You're dealing with complex depreciation. Calculating and recapturing depreciation is one of the trickiest parts of rental taxes, and mistakes here have long-term consequences.
- You have passive activity losses. The rules around deducting rental losses are notoriously complex, particularly if your income is over certain thresholds.
- You might qualify as a Real Estate Professional. This tax status can unlock some incredible benefits, but the IRS has strict requirements you have to prove you meet.
In these cases, a Certified Public Accountant (CPA) with real estate experience isn't just someone entering data. They're a strategist. They can help you legally structure your finances to maximize every possible deduction and keep you compliant. A pro can also help with a landlord insurance comparison to ensure all financial aspects of your investment are properly protected.
Understanding the Cost and Value
Hiring an expert is absolutely an investment, not just another expense. In most major markets, professional tax prep for a landlord will run you anywhere from $175 for a simple return to over $500 for a more complicated portfolio. Costs have definitely crept up in recent years due to ever-changing tax codes. The real driver is complexity—a single property is on the low end, but issues like depreciation recapture or passive losses will increase the fee. You can get more detail on how professionals determine tax preparation rates on MasseyAndCompanyCPA.com.
The most important thing to remember? Fees paid to a tax professional for your rental business are a tax-deductible expense. You’re essentially getting a discount on expert advice that could easily save you thousands by finding deductions you would have otherwise missed.
Navigating Estimated Taxes and Key Deadlines
When you own a rental property, you're officially running a business. That means your tax life gets a little more complex than just hitting a single deadline in April. If your property is turning a profit, the IRS expects you to pay estimated taxes throughout the year to stay on their good side.
Ignoring this is a classic rookie mistake that can lead to a nasty surprise—a significant underpayment penalty when you file your annual return. The government wants its cut as you earn it, not all at once a year later. Getting this right is a huge part of knowing how to prepare for tax season as a landlord.
Who Needs to Pay Estimated Taxes
So, do you fall into this category? As a general rule, you’ll need to pay estimated taxes if you expect to owe $1,000 or more in tax for the year, after accounting for any withholding from a day job and other credits.
For many landlords with W-2 jobs, their employer’s withholding might be enough to cover the extra income from the rental. But if your rental income is your main gig, or just a substantial side hustle, quarterly payments are pretty much non-negotiable.
It's a serious matter, and you can learn more about the implications of skipping quarterly estimated tax payments from tax pros who see the consequences firsthand.
The whole process boils down to this: project your annual rental income, subtract all your deductible expenses to find your estimated profit, and then calculate the tax you'll owe on that amount.
This quick visual shows the basic cycle you'll get into for managing your estimated tax obligations.
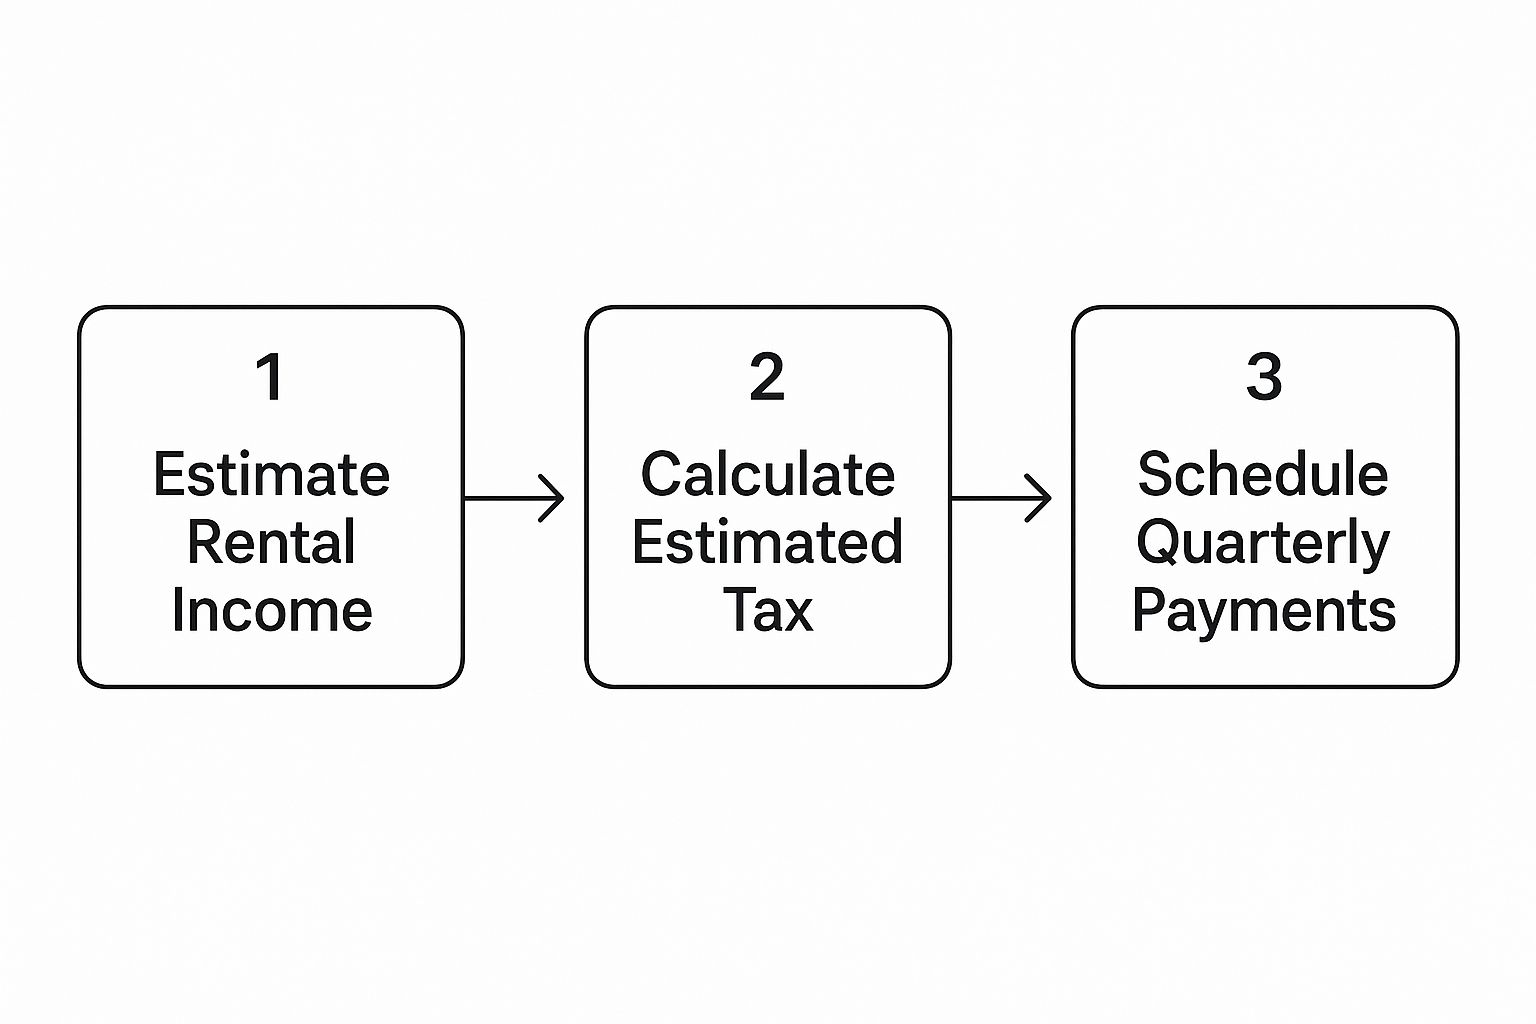
As you can see, it’s a repeating loop of estimating, calculating, and paying. Following this process not only keeps you compliant but also helps you manage your cash flow without any last-minute shocks.
The Unmissable Quarterly Deadlines
These payments are due four times a year. But don't let the word "quarterly" fool you—the deadlines aren't spaced out perfectly every three months. You absolutely need to get these dates on your calendar:
- Payment 1: April 15 (for income earned Jan 1 – Mar 31)
- Payment 2: June 15 (for income earned Apr 1 – May 31)
- Payment 3: September 15 (for income earned Jun 1 – Aug 31)
- Payment 4: January 15 of next year (for income earned Sep 1 – Dec 31)
Key Takeaway: Missing these deadlines or underpaying can trigger penalties, even if you’re actually due a refund when you file your final return. The IRS values consistency above all else.
Juggling these financial tasks can feel like a full-time job, especially if you're new to being a landlord or are busy growing your portfolio. That's where working with experts in https://edinhart.com/fresno-property-management/ can be a game-changer. A good property manager ensures your financial reporting is spot-on, helping you accurately calculate and schedule these critical payments without all the stress.
Common Questions on Rental Property Taxes
Let's be honest, even for seasoned landlords, rental property taxes can feel like navigating a maze. Every year, the same tricky questions seem to pop up. Getting clear, straightforward answers is the only way to file with confidence and make sure you're not leaving money on the table.
We're going to tackle some of the most common points of confusion we see landlords struggle with, giving you the clarity you need for your own tax planning.
What Is the Difference Between a Repair and an Improvement?
This is a big one, and getting it wrong can be a costly mistake. The distinction is critical for your accounting. A repair is something you do to keep your property in its current good condition. Think fixing a leaky faucet, patching a hole in the wall, or replacing a single broken window. These costs are fully deductible as expenses in the year you pay for them. Simple.
An improvement, on the other hand, is a capital expenditure that makes your property better, extends its useful life, or adapts it for a new purpose. We're talking about major projects like a brand-new roof, a full kitchen remodel, or installing a central air conditioning system. You can’t just write these off in one go. Instead, they have to be capitalized and depreciated over several years.
Can I Deduct My Mortgage Principal Payments?
This is a hard no, and it's a common misunderstanding for new landlords. You can't deduct the principal portion of your mortgage payment. Why? Because that payment is building your equity by paying down your loan. It’s not an operating expense; it's you investing back into your own asset.
However, you absolutely can—and should—deduct the mortgage interest you pay all year long. Your lender makes this easy by sending you Form 1098, which clearly states the total interest you've paid. This is often one of the largest and most important deductions a landlord can take.
Key Insight: The principal isn't deductible, but the interest is. Think of it this way: the interest is the fee you pay for the privilege of borrowing money to own the property, making it a legitimate business expense. The principal is just you paying yourself back.
How Do I Handle Security Deposits for Taxes?
When a tenant first gives you a security deposit, it's not income. You don't report it. Since you're obligated to return that money at the end of the lease (assuming the tenant leaves the place in good shape), the IRS doesn't consider it yours yet.
A security deposit only becomes taxable income if you have a legitimate reason to keep some or all of it. For instance, a tenant moves out and you have to use $300 of their deposit to repair a damaged wall they caused. That $300 instantly becomes income you must report for that tax year. On the flip side, the money you spent on the repair itself would then become a deductible expense.
What Happens If My Rental Expenses Exceed My Income?
It happens. Sometimes your deductible expenses for the year are more than the rent you collected, leaving you with a net rental loss. Whether you can deduct this loss against your other income (like from your day job) is where things get complicated, thanks to the "passive activity loss" rules.
- Active Participation: If you actively manage the rental and your Modified Adjusted Gross Income (MAGI) is under $100,000, you can typically deduct up to $25,000 in rental losses against your other income.
- Income Phase-Out: This valuable deduction starts to disappear as your income rises. It phases out completely once your MAGI is between $100,000 and $150,000. If you earn more than that, you likely can't deduct any of those passive losses in the current year.
But those losses aren't gone for good. They get suspended and carried forward to future tax years. You can use them to offset rental profits down the road, or you can deduct them all at once when you eventually sell the property. This area of tax law is complex, and getting advice from a tax professional is always a smart move.
Navigating the financial side of a rental property demands expertise and a sharp eye for detail. At Edinhart Realty and Property Management, we provide the professional oversight needed to ensure your financial records are spot-on and your investment is protected. Learn how our services can bring you peace of mind and maximize your returns.


