

Before you even pull up a spreadsheet, you need to get your head around rental yield. Think of it as your property's financial pulse—a single percentage that tells you exactly how hard your investment is working.
It's the ultimate tool for cutting through the marketing fluff and comparing a downtown condo to a suburban duplex, revealing its true profit potential. This isn't just some fancy metric for Wall Street types; it's a critical first step for anyone serious about buying a rental property. It forces you to make decisions based on cold, hard numbers, not just a gut feeling.
The Two Flavors of Rental Yield
To get a complete picture, you need to know that rental yield comes in two main flavors. Each one tells a different part of your investment's story.
Gross Rental Yield: This is your quick-and-dirty, back-of-the-napkin calculation. It’s perfect for the initial screening phase when you're looking at a dozen properties and need a fast way to weed out the obvious duds.
Net Rental Yield: This is the number that serious investors live and die by. It digs deeper by factoring in all the real-world operating expenses that chip away at your income, giving you a far more accurate picture of your actual return.
Understanding both isn't just a good idea—it's essential for making smart, confident investment moves.
To help you see the difference clearly, here’s a quick breakdown:
Gross Yield vs Net Yield At a Glance
| Metric | What It Measures | Calculation Complexity | Best For |
|---|---|---|---|
| Gross Yield | Pure income potential before any expenses. | Simple | Quick initial property comparisons and market analysis. |
| Net Yield | Actual profitability after all operating costs are paid. | More Involved | Detailed deal analysis and long-term financial planning. |
While gross yield gives you a starting point, net yield is where the rubber meets the road. It shows you what you'll actually put in your pocket.
A Universal Benchmark for Smart Investing
Rental yield acts as a standardized ruler, letting you measure one property against another, no matter the price or location. This isn't a new concept. Economists have been using yield for ages to compare real estate returns against other assets like stocks and bonds.
Historically, after you account for costs like maintenance and vacancies, gross rental yields often land somewhere between 3% and 6%.
A property's yield tells a more complete story than its price tag alone. A lower-priced property with a high yield can often be a more powerful wealth-building tool than an expensive one with a weak return.
Ultimately, whether you're a hands-on landlord or an out-of-state investor using professional Fresno property management, mastering this calculation is your first step. It gives you the power to analyze opportunities with a critical eye, making sure every dollar you invest is working as hard as it possibly can for you.
Your First Look With Gross Rental Yield
Alright, let's get our hands dirty with the first, most essential calculation every real estate investor needs to master. Gross Rental Yield is your go-to metric for making quick, high-level comparisons of a property's income potential.
Think of it as your first filter. It helps you quickly weed out the obvious underperformers before you spend hours digging into the nitty-gritty details of operating expenses.
The formula itself is refreshingly simple. But to get a result that's even remotely useful, you have to nail down two key numbers: the property's annual rental income and its total cost. Getting these figures right is everything.
Defining Your Numbers Accurately
First, you need a realistic projection of what the property will bring in each year. This is no time for wishful thinking. Before you do anything else, you need to accurately calculate your rental income by researching what comparable rentals ("comps") in the immediate area are actually leasing for. Look for properties with similar square footage, condition, and amenities.
Next up is the total property cost, which is almost always more than the shiny price tag you see on the listing. So many new investors stumble here, and it can throw off your entire analysis from the very start.
Your total property cost should include the purchase price plus all the costs to acquire it. That means factoring in closing costs, home inspection fees, and any cash you need for immediate repairs or renovations to get the place rent-ready.
A Real-World Gross Yield Example
Let's walk through this with a real-world scenario. Say you're looking at a duplex in a growing market like Clovis, California.
Here’s how the numbers stack up:
- Purchase Price: $400,000
- Closing Costs & Fees: $8,000
- Initial Renovations (new paint, flooring): $12,000
- Total Property Cost: $420,000 ($400k + $8k + $12k)
After checking local comps, you feel confident you can rent each unit for $1,600 a month. That gives you a total monthly income of $3,200, which works out to $38,400 a year.
Now, we just plug those numbers into the formula:
Gross Rental Yield = (Annual Rental Income / Total Property Cost) x 100
( $38,400 / $420,000 ) x 100 = 9.14%
That quick math gives you a solid 9.14% gross yield. It’s a powerful starting point. It doesn't tell the whole story (we'll get to that with net yield), but it tells you this property is absolutely worth a deeper look and gives you a solid, apples-to-apples way to compare this duplex to other potential deals on your list.
Calculating Net Rental Yield for True Profitability
A good-looking gross yield can get you excited about a property, but it's really just the tip of the iceberg. If you want to understand how a rental will actually perform financially, you have to dig deeper and calculate the net rental yield. This is the metric that separates the pros from the hobbyists because it shows you what you'll really put in your pocket after all the bills are paid.
This calculation is so important because it forces you to look at the real-world operating expenses that will chip away at your rental income. I’ve seen it happen time and again—ignoring these costs is one of the quickest ways to watch a promising investment turn into a financial headache.
The core of finding your net yield is getting to your Net Operating Income (NOI), which is simply your gross rent minus all those pesky operating costs.
Accounting for Every Operating Expense
The secret to an accurate net yield is leaving no stone unturned when it comes to expenses. These are the recurring costs of owning and running the property, and they go way beyond just the mortgage payment.
Your list of annual operating expenses needs to include:
- Property Taxes: This is a big one and it’s unavoidable. The rates can change dramatically depending on the city and county, so always pull the current tax records for the specific property you're analyzing.
- Homeowner's Insurance: Absolutely essential. Make sure you get a landlord-specific policy, not just a standard homeowner's policy.
- Maintenance and Repairs: Things break. Pipes leak, appliances fail. It's not a matter of if, but when. A solid rule of thumb is to budget 1% of the property’s value each year for maintenance. For a $400,000 property, that’s $4,000 annually.
- Vacancy Costs: No property stays rented 100% of the time. People move out. It takes time to find a new tenant. I always recommend clients budget for a vacancy rate of 5-10% of their gross annual rent.
- Property Management Fees: If you hire a pro to handle the day-to-day, expect to pay 8-12% of the monthly rent. It's an expense, but it can save you a ton of time and stress.
- HOA Dues: If your property is in a homeowners association, these monthly or annual fees are a fixed cost you can't forget.
This visual guide breaks down the data you need to gather to get started.
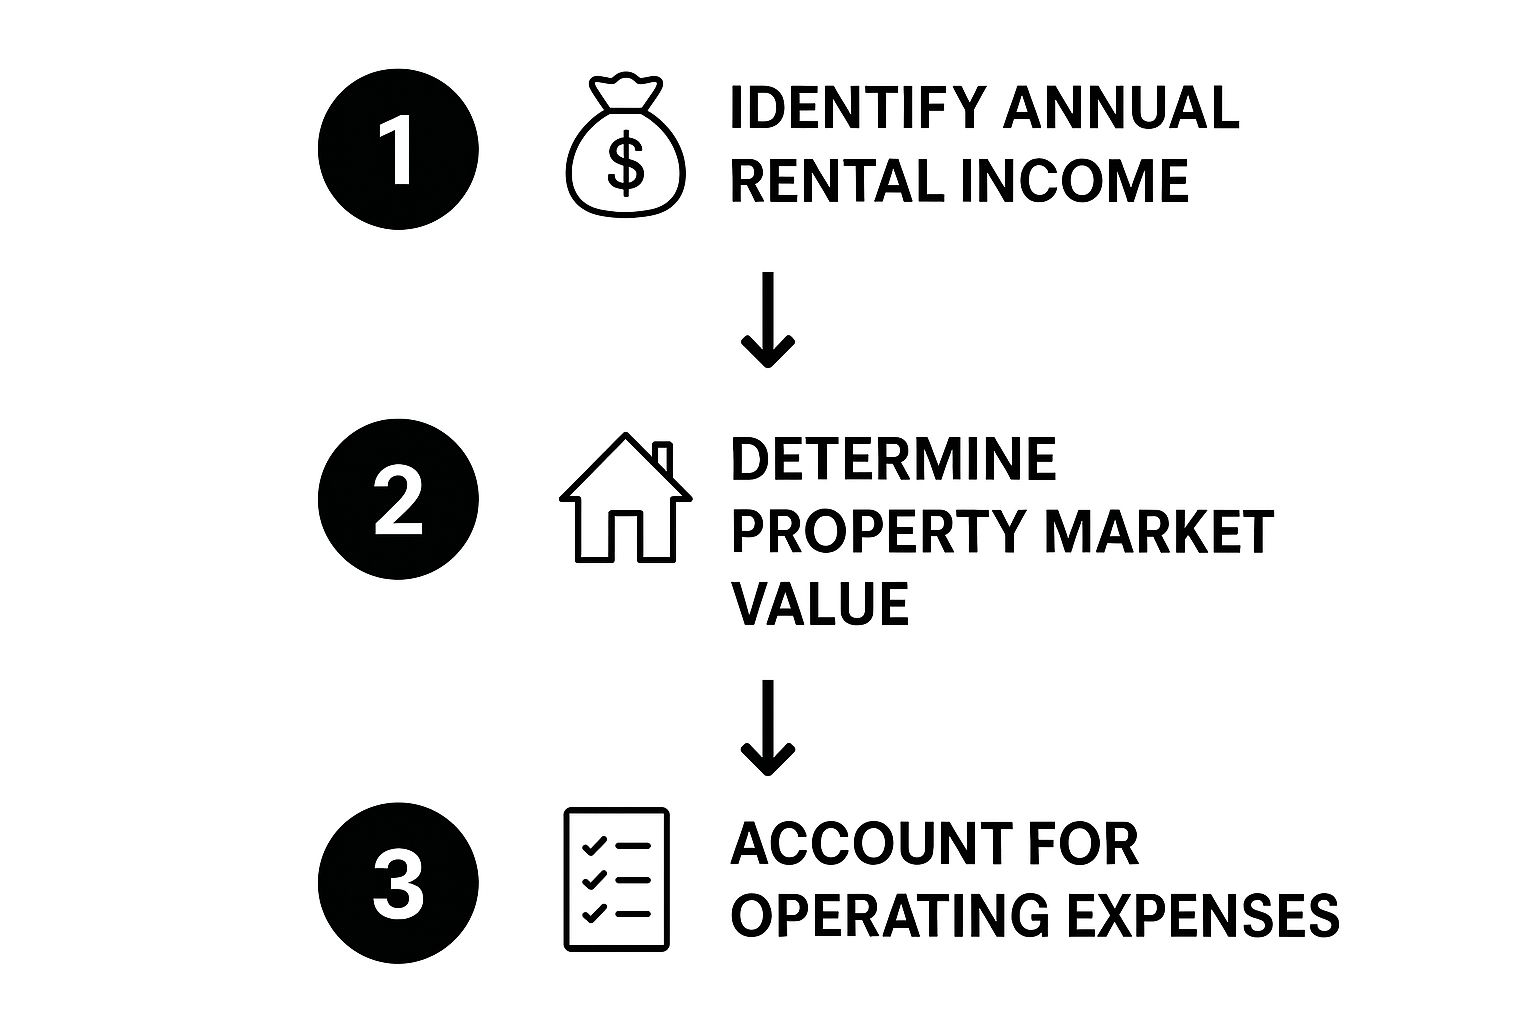
As you can see, you start with the income and property value, but the most critical part is factoring in all of your operating expenses to get to the true net figure.
Putting It All Together With Our Duplex Example
Let's circle back to our $420,000 duplex in Clovis that brings in $38,400 in gross annual rent. Now, it's time to get real and factor in the estimated annual expenses to see its true profitability.
Here’s a realistic breakdown:
- Property Taxes: $5,250 (roughly 1.25% of the purchase price here in California)
- Insurance: $1,500
- Maintenance (1% Rule): $4,000
- Vacancy (5% of Gross Rent): $1,920
- Property Management (8% of Gross Rent): $3,072
- Landscaping & Utilities: $1,200
Total Annual Expenses: $16,942
First, let's find the Net Operating Income (NOI):
$38,400 (Gross Rent) – $16,942 (Expenses) = $21,458 (NOI)
With our NOI in hand, we can finally calculate the net rental yield.
Net Rental Yield = (Net Operating Income / Total Property Cost) x 100
($21,458 / $420,000) x 100 = 5.11%
So, after doing our homework, that exciting 9.14% gross yield has settled into a much more realistic 5.11% net rental yield. This is the number that truly reflects the investment's performance. Getting the rent right from the start is a huge part of making these numbers work, which is why you should check out our guide on how to price a rental property.
While you're focused on rental income, it never hurts to understand the full picture of real estate investing, which can include profits from flipping. A real estate flip profit estimator can be a useful tool for this kind of broader analysis.
Recent data pegs the average gross rental yield in the U.S. at around 6.51%. This really drives home why calculating the net yield is so critical—those operating expenses we just detailed can easily eat up a huge chunk of your returns, and the gross number just doesn't tell that story.
What’s a Good Rental Yield in Today’s Market?
So, you've crunched the numbers and you have your rental yield percentage. Now for the big question: Is it any good? What does that number actually mean for your investment?
The honest answer is that there’s no single magic number. What’s considered a “good” yield depends heavily on the property, the market it’s in, and, most importantly, your personal investment goals.
For most investors I talk to, a net rental yield somewhere between 5% and 8% is the sweet spot. A yield in this range usually means you have a healthy cash flow coming in after all your expenses are paid—a solid return. But this isn't a hard-and-fast rule. Context is everything.
High Yield vs. High Appreciation
Let’s think about two completely different investment plays. You might find a property in a stable, smaller city that boasts a fantastic 10% net yield. It throws off great monthly cash, but its actual market value might only creep up a little each year.
Now, compare that to a modern condo in a booming coastal tech hub. That property might only give you a 3% net yield, barely covering its own costs. But what if that area has explosive job growth and a tight housing supply? The property's value could jump 15% in a single year. An investor playing the long game for wealth growth would happily take that lower cash flow for a shot at that kind of appreciation.
It all comes down to the classic trade-off: Do you want cash flow today or wealth tomorrow? There’s no right or wrong answer—just the one that fits your financial plan.
How Local Factors Set the Bar
Beyond your personal strategy, the local economy is a massive piece of the puzzle. The rental market dynamics in your specific area can completely change what a "good" return looks like.
In certain global real estate markets, intense demand can push yields way up, even when property prices are sky-high. For instance, the rental index for small apartments in Hong Kong recently shot up 6.9% year-over-year. That’s a clear signal of how critical it is to understand the supply and demand pressures right where you plan to buy.
To figure out a realistic benchmark for your potential property, you have to dig into these local factors:
- Job Growth: Is the city adding jobs? A healthy job market brings in new people, which fuels rental demand and gives you the power to charge higher rents.
- Rental Demand: What’s the vacancy rate in the neighborhood you're eyeing? Low vacancy is a great sign—it means demand is strong and you’ll have more leverage.
- Property Class: Are you buying a new, high-end Class A property, a well-kept but older Class B, or a Class C property that needs some work? Each one has its own risk level and typical yield.
Some investors I know prioritize stability above all else. They hunt for unique situations like properties with assured rental income from the government that offer guaranteed, long-term contracts.
At the end of the day, a good yield isn't just a number. It's a number that works for your market and your goals.
Avoiding Common and Costly Calculation Mistakes
A shaky rental yield calculation is like building a house on a bad foundation—it’s only a matter of time before things go wrong. Getting your numbers right from the start isn’t just good practice; it’s the critical final check before you commit your hard-earned money to a property.
Let's walk through some of the most common—and expensive—traps I've seen investors fall into over the years, and more importantly, how you can avoid them.
One of the biggest blunders is glossing over the true cost of maintenance. It's easy enough to budget for a leaky faucet or lawn care, but many first-time investors completely forget about the big-ticket items that eventually come due. A new HVAC system or an unexpected roof replacement can vaporize years of your cash flow if you haven't been planning for it.
Pro Tip: I always advise clients to set up a separate bank account for "Capital Expenditures" or CapEx. This isn't your everyday repair fund. This money is exclusively for major system replacements, ensuring a multi-thousand-dollar bill doesn't catch you completely off guard.
Overlooking Vacancy and Other Sneaky Costs
Another classic mistake? Assuming your property will be occupied 100% of the time. That’s a fantasy that can quickly sour a deal. Every single day a unit sits empty, you're losing money. This loss directly hits your annual income, which can tank your actual net rental yield.
Beyond just vacancy, a bunch of other subtle costs often get lost in the excitement of closing a deal.
- Closing Costs: These one-time fees can easily add thousands to your initial investment, but investors often forget to factor them in when running their numbers.
- Insurance Gaps: The wrong policy can be a catastrophic error. Our landlord insurance comparison guide can help you make sure you’re properly covered for a rental.
- Tenant Turnover Costs: This is so much more than just lost rent. You're on the hook for marketing the unit, screening new applicants, and often making small repairs or updates to get it ready for the next tenant.
Relying on Unrealistic Projections
Finally, it’s all too easy to fall into the trap of using overly optimistic numbers. Taking a seller's "pro forma" rent estimates at face value without doing your own homework is a huge risk. You have to verify those projections with hard data from comparable local rentals.
The only real solution here is diligence. Create a detailed spreadsheet that accounts for every single possible expense, from property taxes down to the smallest repair. Then, stress-test your numbers. See what happens if you increase your vacancy rate or your maintenance budget. A conservative, well-researched calculation is your absolute best defense against a bad investment.
Answering Your Top Rental Yield Questions
https://www.youtube.com/embed/deRCLIdgTi4
Once you start plugging numbers into a spreadsheet, you’ll quickly realize that real-world investing brings up a lot of practical questions. The theory is one thing, but how it all works on the ground is what really matters.
Here, we'll tackle the most common questions that come up for investors, giving you the clear answers you need to analyze properties with confidence.
One of the first things that trips people up is how financing plays into the numbers. It's a critical distinction that changes which metric you should be looking at.
Should I Include My Mortgage Payment?
I get this question all the time: "Do I subtract my mortgage payment when I calculate my net rental yield?" The simple answer is no.
A standard net rental yield calculation is specifically designed to show you how the property itself performs as a standalone business. It’s all about the property's income versus its direct operating expenses, completely separate from how you chose to finance it.
If you want to see how your specific loan affects your personal returns, you'd look at a different number: Cash-on-Cash Return. That calculation directly compares the cash you have left after paying the mortgage to the initial cash you put down. Think of it this way: Net yield analyzes the asset; cash-on-cash return analyzes your deal.
How Does Property Appreciation Fit In?
It's also crucial to understand that rental income and property value growth are two totally different parts of your investment return.
- Rental Yield: This is your cash flow engine. It’s all about the income the property generates for you right now, relative to its price.
- Appreciation: This is your long-term wealth builder. It’s the increase in the property's market value over time.
You might find a property in a stable Midwest market with a fantastic rental yield but very slow appreciation. On the other hand, a property in a hot coastal city could have a razor-thin yield but huge potential for appreciation. Your personal investment strategy dictates which of these you should prioritize.
A smart investment analysis looks at both sides of the coin—yield for today's cash flow and appreciation for tomorrow's growth. The key is aligning these with your own financial goals to make the right choice.
How Often Should I Recalculate My Yield?
Finally, calculating your rental yield isn’t something you just do once and forget about. To really keep a pulse on your investment's health, you should make it a habit to recalculate it at least once a year.
This annual check-up forces you to account for the real-world changes that hit your bottom line, like increases in property taxes, new insurance premiums, or the rent hikes you've put in place.
A truly savvy investor will take it a step further and also recalculate the yield using the property’s current market value, not just what you paid for it. This gives you a "current rental yield," and it's an incredibly powerful tool. It helps you decide if your money is still working hard enough in that property or if it might be time to sell and put those profits to work somewhere else.
Navigating the complexities of property analysis and management is much easier with an expert partner. Edinhart Realty and Property Management provides the professional guidance and hands-on service needed to maximize your returns in the Central California market. Discover our management solutions today.


