

So, what actually makes a property a good investment? It’s more than just four walls and a roof; it's about acquiring an asset that consistently generates income, grows in value, and is planted in the right spot.
Think of it as a financial engine. A good investment property isn't just a place someone lives—it's a machine designed to build your wealth, combining strong rental income with the potential for long-term growth.
What Defines a Good Investment Property
Let's cut through the noise. A great investment isn't about fancy finishes or curb appeal. It’s about a property that actively works for you, and that means digging deeper than the surface to find the core elements that create real, sustainable returns.
A truly solid investment property stands on three critical pillars. Get all three right, and you've got a winner. Miss one, and you could be in for a headache.
The Three Pillars of a Strong Real Estate Investment
A successful rental property isn't a one-trick pony. It needs to perform well across three key areas. If any one of these is weak, a promising deal can quickly turn into a financial burden.
Positive Cash Flow: This is the absolute lifeblood of your investment. It's the cash left in your pocket each month after you’ve collected rent and paid all the bills—mortgage, taxes, insurance, maintenance, you name it. If you don't have positive cash flow, you’re paying to own the property, not the other way around.
Appreciation Potential: Cash flow keeps the lights on, but appreciation is what builds serious, long-term wealth. This is the simple increase in your property's market value over time, driven by things like inflation, local demand, and neighborhood improvements.
Strategic Location: You've heard it a million times because it's true: location, location, location. A property in an area with solid job growth, good schools, and low crime will always attract quality tenants and command higher property values.
A great property in a bad neighborhood is almost never a good investment. But an average property in a thriving area? That’s often a fantastic buy. A strong market lifts all boats and gives your investment a crucial margin of safety.
Recent trends are showing real strength in the market, which just highlights how important a smart strategy is. For example, global private real estate has made a serious comeback, with values climbing for five straight quarters through Q2 2025 and delivering positive returns across all 21 countries tracked.
This rebound is happening because interest rates are stabilizing and investors are feeling more confident. Transaction volumes jumped to $739 billion over the last 12 months, a 19% increase year-over-year in major markets. If you want to dive deeper, you can learn more about these global real estate trends and tactics. This data just proves that even when the economy is unpredictable, well-chosen properties are still a resilient and profitable way to invest.
Decoding the Numbers: Key Financial Metrics for Investors
A property might look perfect on the outside, but the real story is always in the numbers. When it comes to real estate, a deep dive into the key financial metrics is the only way to know if you've found a genuinely good investment. Think of these metrics as the dashboard in your car—they give you an instant, unbiased look at how the engine is performing.
Learning to read these numbers takes the emotion out of the equation. It swaps guesswork for a clear, mathematical understanding of a property's health and potential, letting you spot a winning deal with confidence.
Cash Flow: The Most Important Metric
Let's start with the absolute foundation of a solid rental property: positive cash flow. This is the money you have left in your pocket each month after collecting rent and paying all the bills, including the mortgage. It's that simple.
If a property doesn't generate positive cash flow, it isn't an asset; it's a liability you're paying for every single month. To figure it out, just subtract your total monthly expenses from your total monthly rental income. Don't forget to include everything:
- Mortgage (principal and interest)
- Property taxes and insurance
- Property management fees
- Vacancy reserves (a good rule of thumb is 5-10% of rent)
- A fund for repairs and maintenance
This is where the rubber meets the road.
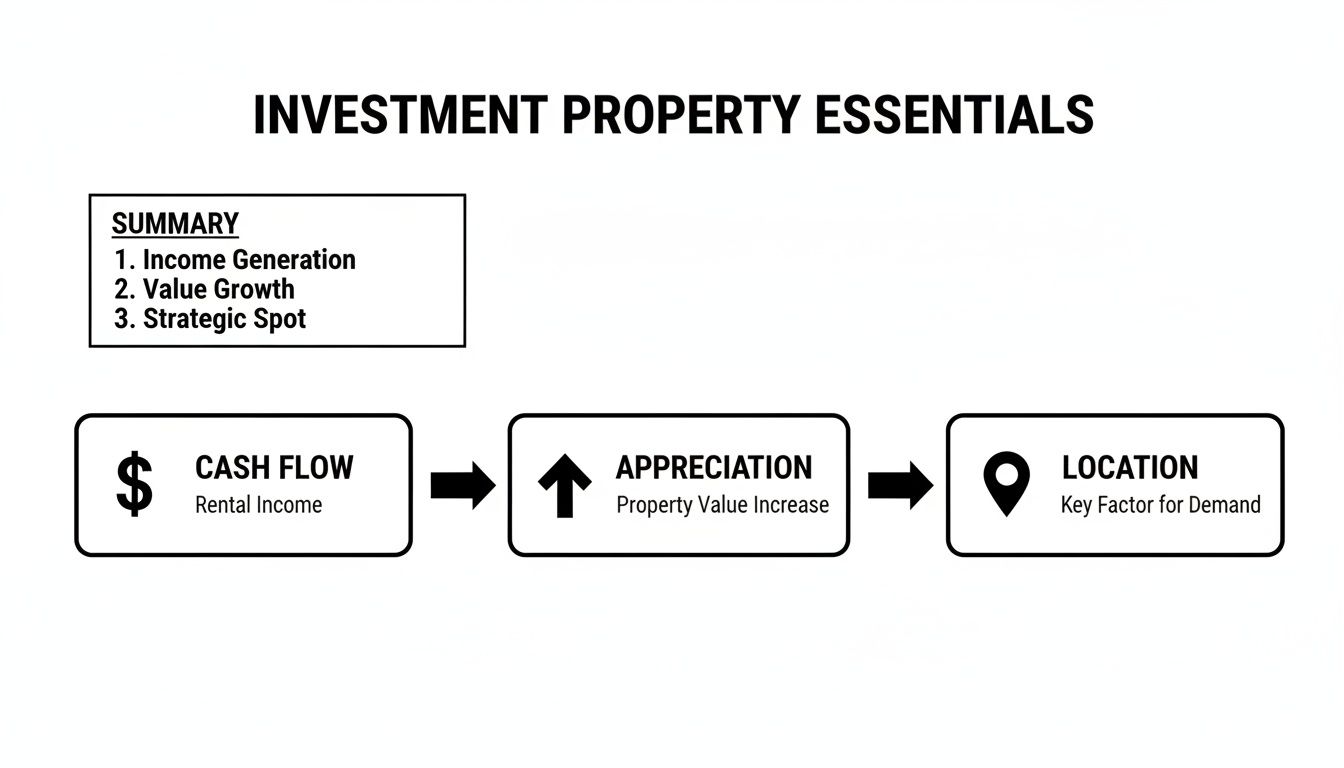
As you can see, strong cash flow, long-term appreciation, and a prime location all work together to build a stable and profitable investment for the long haul.
To give you a clearer picture, here’s a quick-reference table breaking down the core financial metrics you'll need to master.
Key Financial Metrics at a Glance
| Metric | What It Measures | Why It's Important |
|---|---|---|
| Cash Flow | Monthly profit after all expenses are paid. | The ultimate measure of a property's immediate profitability. Positive cash flow means the property pays you. |
| Cap Rate | The potential rate of return based on the property's income. | Allows for a quick, apples-to-apples comparison of different properties, regardless of financing. |
| Cash-on-Cash Return | The return on the actual cash you invested out of pocket. | Tells you how hard your personal capital is working for you, which is crucial for personal financial goals. |
These three metrics form the bedrock of any serious investment analysis. Let's dig a little deeper into the other two.
Capitalization Rate: For Quick Comparisons
The Capitalization Rate, or Cap Rate, is your go-to tool for quickly comparing the potential return of different properties on an even playing field. It shows a property's profitability before you factor in any loans, giving you a pure look at the asset's performance.
Cap Rate = Net Operating Income (NOI) / Property Purchase Price
Imagine you're eyeing two single-family homes in Fresno. Property A has a cap rate of 6%, while Property B has a cap rate of 4.5%. All other things being equal, Property A is generating a higher return on its value, making it the stronger contender right out of the gate. For a detailed breakdown of this core component, you can learn more about how to calculate net operating income in our guide.
Cash-on-Cash Return: Measuring Your True ROI
While Cap Rate is fantastic for comparing deals, Cash-on-Cash Return hits closer to home. It tells you what really matters to your wallet: how hard your invested cash is working for you. This metric calculates your annual pre-tax cash flow as a percentage of the total cash you pulled out of your own pocket.
Your total cash invested includes:
- The down payment
- All closing costs
- Upfront repair or renovation expenses
Let's say you invest $70,000 of your own money to buy a rental property. If that property puts $7,000 in your pocket (positive cash flow) for the year, your cash-on-cash return is a solid 10% ($7,000 / $70,000). Most savvy investors shoot for a return of 8-12%, making this a vital benchmark for deciding if a property meets your personal goals.
To help forecast profitability, a short-term rental income calculator can be a really useful tool for projecting potential earnings with more accuracy. By mastering these three metrics—cash flow, cap rate, and cash-on-cash return—you stop being a hopeful buyer and become an informed investor, ready to spot the kind of properties that build real wealth over time.
Choosing the Right Type of Investment Property
Once you have a handle on the key financial metrics, the next move is matching your investment strategy to the right kind of property. Let’s be clear: not all rentals are built the same. The best one for you boils down to your personal goals, how much risk you're comfortable with, and frankly, how much time you want to sink into managing it.
Think of it like picking the right tool for a job. Each property type has its own distinct purpose and benefits. Knowing the pros and cons helps you find the perfect fit, whether you're aiming for slow-and-steady growth or trying to maximize that monthly cash flow.
Single-Family Homes: The Foundation of Many Portfolios
For many new investors, the single-family home (SFH) is the natural starting point, and for good reason. They're straightforward, they're everywhere, and they tend to attract long-term tenants—think families who want stability and to plant roots in a community. That usually translates to lower tenant turnover, which means less time and money spent on marketing and getting the place ready for someone new.
For example, a three-bedroom house in a great Clovis school district is a magnet for a family that might stick around for years. The monthly cash flow might not be as high as a multi-unit property, but the potential for strong appreciation is often better, making it a solid play for building wealth over the long haul. For a deeper dive, check out our guide on why buying single-family homes can be a good investment.
The big "but" with an SFH? Your entire rental income is tied to one door. If that tenant leaves, your income plummets to zero until you find a replacement.
Duplexes and Multi-Family Units: Scaling Your Income
If your focus is on juicing your cash flow and growing your portfolio, then duplexes, triplexes, and fourplexes are absolute game-changers. These multi-family properties have one massive advantage: multiple income streams under a single roof. That built-in diversification is a huge selling point.
If one unit in your duplex goes vacant, you still have 50% of your potential rent coming in from the other side. That’s a financial cushion a single-family home just can’t offer.
A duplex near a major employer or a university in Fresno, for instance, can pump out significantly more cash than a single-family home out in the suburbs. Yes, they can require more hands-on management with multiple tenants, but the financial rewards often make it well worth the effort.
This is a big part of why residential properties are such hot investment picks right now. Globally, we're seeing chronic supply shortages and sky-high renter demand, which is pushing performance. With multi-family construction starts projected to be 74% below their 2021 peak by mid-2025, that tight supply is only going to keep rents strong. You can discover more insights about the 2025 real estate outlook to see why this trend is a tailwind for multi-family investing.
House Hacking: The Smart Start
House hacking is a brilliant strategy where you buy a multi-unit property (like a duplex or triplex), live in one unit, and rent out the others. The rent you collect from your neighbors can drastically reduce—or even completely cover—your mortgage payment. You essentially get to live for free, or close to it, while building equity in a prime asset.
This approach comes with some powerful perks:
- Lower Barrier to Entry: You can often qualify for owner-occupant financing, like an FHA loan, which lets you get in the door with a much smaller down payment (as low as 3.5%) compared to a typical investment loan.
- On-Site Management: Living right there means you can manage the property yourself. You'll save a ton on management fees and can keep a close eye on your investment.
- The Ultimate Learning Experience: It’s an incredible, hands-on way to learn the ropes of being a landlord with very little financial risk.
Picking the right property type really sets the tone for your entire investment journey. Whether you like the stability of a single-family home, the cash flow of a multi-family, or the savvy efficiency of house hacking, the key is aligning the property with your goals. That’s your first real step toward building a successful real estate portfolio.
Analyzing Markets and Neighborhoods Like a Pro
We’ve all heard the old saying: "location, location, location." It’s a bit of a cliché, sure, but it’s also the absolute bedrock of finding a great investment property. So, what does it really mean to analyze a location?
Seasoned investors look past a pretty street or a nice park. They’re not just seeing a neighborhood for what it is today; they're looking at what it has the potential to become tomorrow. This is the kind of deep-dive analysis that separates a decent investment from a truly profitable one. It’s about understanding the economic and social currents that drive rental demand and property values.
Think of yourself as a detective, piecing together clues that point toward future growth.
Key Drivers of a Strong Rental Market
A hot rental market doesn't just happen by accident. It's fueled by specific, measurable factors that create a steady stream of good tenants who actually want to live there. Nailing these core drivers is the first step.
Job Growth and Economic Hubs: A growing job market is the single most powerful engine for rental demand. Simple as that. Look for areas with new businesses moving in, corporate expansions, or proximity to major employers like hospitals and universities. Here in Fresno, properties near the Community Regional Medical Center or Fresno State always have a deep pool of potential renters.
Population Growth: Are people moving in or out? You can find this out from census data and local economic reports. A growing population is a clear signal of increasing demand for housing, which naturally pushes both rents and property values up.
Quality of Life Indicators: This is all about what makes a neighborhood a great place to live. Things like high-quality school districts, low crime rates, and easy access to amenities—parks, shopping, good restaurants—all add to a location’s appeal. These are the things that attract and keep good, long-term tenants.
The Art of "Path of Progress" Investing
Now, let's go a level deeper. The most successful investors I know have mastered the art of “path of progress” investing. This strategy is all about figuring out where the growth is headed next and getting in before prices catch up.
This isn't about wild speculation or gambling. It's about making educated predictions based on real, tangible evidence. When you learn to spot the early signs of revitalization or expansion, you position your investment to capture the most appreciation.
So, how do you spot these up-and-coming areas? You have to look for clues that signal future investment from both the city and private businesses.
Signs of an Emerging Neighborhood
Planned Infrastructure Projects: Get familiar with city planning documents. Is a new highway interchange, public transit line, or major road expansion in the works? These projects make an area more accessible and can dramatically increase its value.
Commercial Redevelopment: Keep an eye out for what businesses are doing. When you see new coffee shops, boutique stores, or a new grocery chain moving in, pay attention. These companies do their homework, and their arrival is a strong vote of confidence that a neighborhood is on the upswing.
Gentrification Indicators: This can be a complex topic, but signs like an uptick in home renovations, rising property values in adjacent areas, and more young professionals moving in often mean a neighborhood is in transition.
For example, let's say an investor sees that the city of Fresno has approved plans to revitalize a specific downtown corridor. By buying a duplex just a few blocks away before the bulldozers even show up, they are perfectly positioning that asset to benefit from the future improvements, increased foot traffic, and renewed interest.
This is the forward-thinking approach that helps you find good investment properties that deliver incredible long-term returns. It’s about more than just buying in an already "good" neighborhood; it's about finding the next good neighborhood.
Your Essential Due Diligence Checklist
You've analyzed the market and run the numbers. Now comes the final, most crucial step before you put your money on the line: due diligence.
Think of it as the ultimate pre-flight check for your investment. Skipping this is like buying a car without ever popping the hood—a surefire way to turn a seemingly great deal into a financial nightmare. This is where you graduate from spreadsheets to reality, personally verifying every single assumption you've made.
Physical And Structural Inspection
First things first: get a deep, hands-on understanding of the property's physical condition. A fresh coat of paint can hide a world of hurt, and a major structural issue can wipe out your budget and years of potential profit. Whatever you do, never skip a professional home inspection.
A seasoned inspector is trained to spot the red flags you’d almost certainly miss. They’re looking for things like:
- Foundation and Structural Integrity: Are there cracks, signs of settling, or water damage that point to expensive foundation problems?
- Roof and Attic: How old is that roof? It’s one of the costliest items to replace, and an inspector can give you an honest assessment of its remaining life.
- Major Systems: The HVAC, plumbing, and electrical systems are the heart of the home. An inspector checks their age, function, and safety.
- Pest and Environmental Hazards: Termites, mold, and other nasty surprises can require pricey remediation.
A $500 inspection that saves you from a $15,000 foundation repair is the best money you'll ever spend in real estate. It either gives you the power to renegotiate the price or the good sense to walk away.
This inspection report becomes your roadmap. It tells you what needs fixing now and what big-ticket items (we call these capital expenditures) are coming down the pike, letting you build a real-world budget from day one.
Financial And Legal Verification
Once you’re satisfied with the building’s physical health, it's time to put its financial and legal status under the microscope. This is how you make sure you're buying a clean asset—not inheriting someone else's mess or banking on puffed-up income claims.
Your financial and legal audit must cover a few non-negotiables:
Independent Rental Market Analysis: Never, ever take the seller's word for what the property can rent for. Do your own homework. Look at what similar properties in the neighborhood are actually renting for right now to see if the seller's numbers are grounded in reality.
Review Existing Leases: If the property has tenants, you need to read every single lease agreement, front to back. Pay close attention to the lease terms, rent amounts, security deposit details, and any weird clauses. Remember, you are inheriting these tenants and their legally binding contracts.
Title Search and Insurance: A professional title search is essential. It confirms the seller actually has the legal right to sell the property and reveals if there are any outstanding liens or claims against it. Always, always get title insurance to protect yourself from any surprise ownership disputes down the road.
This is more than just a checklist; it's a process that transforms you from a hopeful buyer into a savvy, informed investor. Due diligence isn't about finding excuses not to buy a property. It's about finding all the facts you need to buy it the right way and protect your capital.
We’ve put together a handy table to help you keep track of the key steps.
Investor Due Diligence Checklist
Use this checklist as your guide to make sure nothing falls through the cracks. It's your best defense against costly surprises and ensures you're making a sound, well-researched investment decision.
| Checklist Item | Purpose | Key Considerations |
|---|---|---|
| Professional Home Inspection | To assess the physical condition of the property and identify potential costly repairs. | Foundation, roof, HVAC, plumbing, electrical, pests, mold, and overall structural integrity. |
| Appraisal | To get an independent valuation of the property's worth, often required for financing. | Is the purchase price supported by comparable sales? |
| Review Leases & Tenant Estoppels | To verify rental income and understand the terms of existing tenancy agreements. | Rent amounts, lease end dates, security deposits, and any special clauses or concessions. |
| Verify Income & Expenses | To confirm the property's financial performance by reviewing seller-provided documents. | Rent rolls, utility bills, property tax statements, and maintenance records. |
| Title Search | To ensure the seller has a clear title to the property without any liens or encumbrances. | Unpaid taxes, contractor liens, judgments, or ownership disputes. |
| Survey | To identify the exact property boundaries and check for any encroachments. | Fences, driveways, or structures from neighboring properties that cross the line. |
| Zoning & Code Compliance | To confirm the property is being used legally and meets local municipal codes. | Permitted uses (e.g., multi-family), building permits for additions, and safety compliance. |
| Insurance Review | To determine the insurability of the property and estimate future insurance costs. | Location in a flood zone, claims history, and condition of major systems. |
Working through this list isn't just paperwork; it’s the bedrock of a successful investment. It gives you the clarity and confidence to either move forward with the deal, renegotiate terms from a position of strength, or walk away knowing you dodged a bullet.
How Professional Management Maximizes Your ROI
Finding the right property is a huge win, but it’s really only half the battle. What happens after you get the keys is what separates a good investment from a great one. Expert management protects your asset and turns a demanding side-hustle into what it was always supposed to be: a stable, passive income stream.
Lots of new investors see a management fee as an expense to avoid at all costs. But seasoned pros know the truth: professional management isn't a cost, it's an investment in itself. It’s a service that pays for itself through higher returns, fewer headaches, and genuine peace of mind.
Good management isn’t about waiting for a faucet to leak. It’s about preventing problems before they start, navigating the maze of legal compliance, and putting systems in place that make your property perform at its peak. This proactive approach is the secret weapon that separates thriving portfolios from struggling ones.
Protecting Your Asset and Boosting Your Bottom Line
Think of a professional property manager as the CEO of your investment. Their main job is to guard its value and squeeze every last drop of profitability out of it. They’re a shield, deflecting the risks that can quickly eat away at your returns.
You’ll see their impact show up directly on your financial statements:
- Reduced Vacancy Time: An expert manager knows the local market inside and out. They use targeted marketing to get your property filled faster, because every day a unit sits empty is money down the drain.
- High-Quality Tenant Screening: This might just be the most critical piece of the puzzle. A rigorous screening process—checking credit, background, and rental history—drastically reduces your risk of late payments, property damage, and the nightmare of eviction.
- Efficient Rent Collection: Professional, automated systems mean rent gets collected on time, every time. This creates consistent cash flow and saves you from the awkward job of chasing down payments.
The real value of a manager isn't just in the tasks they handle; it's in the crises they prevent. A single bad tenant can cost an investor thousands in legal fees and lost rent—a cost that professional screening almost always avoids.
The Operational Advantage
Beyond just the money, professional management brings an operational structure that most DIY landlords simply can't match. That efficiency saves you both time and money. For a deeper dive into boosting rental income through smart management, check out The Ultimate Guide to St. Augustine Property Management.
Managers streamline everything. They coordinate maintenance with vetted, cost-effective vendors and ensure every action they take complies with strict landlord-tenant laws. This keeps your tenants happy and shields you from legal trouble. To get a better sense of all the moving parts, take a look at our guide on what property management really is.
At the end of the day, partnering with a professional manager like Edinhart gives you access to expertise, systems, and resources that protect your asset and maximize its ROI. This lets you enjoy the financial upside of owning good investment properties without the daily grind, freeing you up to focus on what you do best: finding your next great deal.
Answering Your Top Questions About Investment Properties
Stepping into the world of real estate investing always kicks up a few questions. That’s perfectly normal. Getting straight answers is what builds confidence and helps you sidestep the rookie mistakes. Here, we're tackling some of the most common things we hear from investors, both new and seasoned, to give you the clarity you need to move forward.
How Much Cash Do I Really Need to Start?
The answer isn't set in stone, but for a conventional investment loan, a good rule of thumb is a 20-25% down payment. Don't forget to factor in closing costs, which usually tack on another 2-5% of the purchase price.
But the most important piece? Your cash reserves. Having a safety net of 3-6 months' worth of total property expenses is absolutely crucial. This is your emergency fund for when a tenant leaves unexpectedly or the AC unit dies in the middle of summer. Of course, there are creative ways to get in with less, like "house hacking" with an FHA loan, which can dramatically lower your initial cash outlay.
Is a Single-Family Home or a Multi-Family a Better Investment?
Honestly, this boils down to your personal goals. A single-family home often attracts a great, long-term tenant who treats the place like their own, and you might see better appreciation over the long haul. The downside? Your income is tied to one door. When that tenant moves out, your income goes to zero until you find a new one.
Multi-family properties, on the other hand, almost always generate more monthly cash flow and spread your risk.
Think about it: if one unit in a duplex is empty, you’re still collecting rent from the other. This built-in diversification makes multi-family a fantastic way to scale your portfolio faster, though it can mean a bit more hands-on management.
What Are the Biggest Mistakes New Investors Make?
The costliest blunders usually fall into a few key categories. The number one mistake is underestimating expenses, especially the big-ticket items like a new roof or HVAC system that can pop up out of nowhere. Many new investors also get tripped up by doing lazy due diligence or, even worse, failing to properly screen their tenants.
Another classic error is trying to manage the property yourself without having the time, know-how, or temperament for it. That path can lead to lost rent and serious legal headaches fast. The secret to avoiding all this? Meticulous planning and partnering up with pros who have been down this road a thousand times before.
At Edinhart Realty and Property Management, we’ve seen it all. Our team has the expertise to help you sidestep these common pitfalls and make sure your investment is working for you. Whether you need a team to handle everything with full-service management or just need help finding a quality tenant, we’ve got a solution for your goals. Learn more at https://edinhart.com.


