

Buying your first home is a monumental step, transitioning you from renter to homeowner and building long-term wealth. However, the path to closing day is filled with critical decisions, complex financial steps, and a unique vocabulary that can feel intimidating. The process involves much more than just browsing listings online; it requires careful planning, financial discipline, and a clear strategy to avoid common pitfalls. Making an uninformed decision can lead to financial strain or buyer's remorse, turning a dream into a stressful obligation.
This guide is designed to eliminate that uncertainty. We have compiled a list of essential, actionable first time home buyer tips to serve as your roadmap. Instead of generic advice, you'll find a detailed breakdown of each crucial stage, from securing your financing and understanding all associated costs to working with the right professionals. We'll demystify the mortgage process, explain the importance of a great credit score, and highlight why a thorough home inspection is non-negotiable.
Think of this article as your personal guide through the purchasing journey. Each tip is structured to provide clarity and empower you to move forward with confidence. To help you navigate the entire process, a comprehensive first time home buying checklist can be invaluable for tracking your progress. By following these steps, you’ll be well-equipped to make sound choices, find a home you love, and successfully secure the keys to your first property. Let’s get started.
1. Get Pre-approved for a Mortgage
Before you even start browsing online listings or attending open houses, one of the most crucial first time home buyer tips is to secure a mortgage pre-approval. This isn't just a casual estimate; it's a formal process where a lender thoroughly reviews your financial health, including your income, assets, debt, and credit history. The result is a conditional commitment for a specific loan amount, which effectively turns you into a power buyer.

Think of pre-approval as your ticket to the serious home-buying game. It tells sellers and real estate agents that you are a credible, well-qualified buyer who can close the deal. In a competitive market, a pre-approval letter can be the deciding factor. For example, a couple in Austin had their offer accepted over higher cash offers simply because their solid pre-approval demonstrated they could close quickly and reliably, giving the seller peace of mind.
How to Get Pre-approved and Maximize Its Power
Getting pre-approved requires organization and strategic timing. The process gives you a clear, realistic budget, preventing the disappointment of falling in love with a home you can't afford. It also empowers you to make strong, confident offers.
Here’s how to approach it effectively:
- Gather Your Documents: Lenders will need to verify your financial standing. Have these documents ready to speed up the process:
- Two years of tax returns (W-2s and/or 1099s)
- Recent pay stubs (at least 30 days)
- Bank statements for all accounts (checking, savings, investments)
- Proof of any other income sources
- Shop Lenders Smartly: To find the best interest rate and terms, compare offers from at least three to four lenders (e.g., national banks, local credit unions, and mortgage brokers). Credit scoring models typically treat multiple mortgage inquiries within a 14-45 day window as a single event, minimizing the impact on your credit score.
- Maintain Financial Stability: Once you start the process, avoid any major financial changes. This means no big purchases on credit, no new car loans, and don't change or quit your job. Lenders value stability, and any significant shifts could jeopardize your approval.
2. Save for a Down Payment and Closing Costs
Beyond mortgage approval, the most significant financial hurdle for first-time buyers is accumulating enough cash for the down payment and closing costs. These are separate, substantial expenses. The down payment is a percentage of the home's purchase price paid upfront, while closing costs cover fees for services like the appraisal, title search, and loan origination. Failing to budget for both can derail a home purchase before it even begins.
The bar chart below illustrates the typical percentages required for these upfront costs, highlighting the difference between a low-down-payment FHA loan and a conventional loan aimed at avoiding private mortgage insurance (PMI).
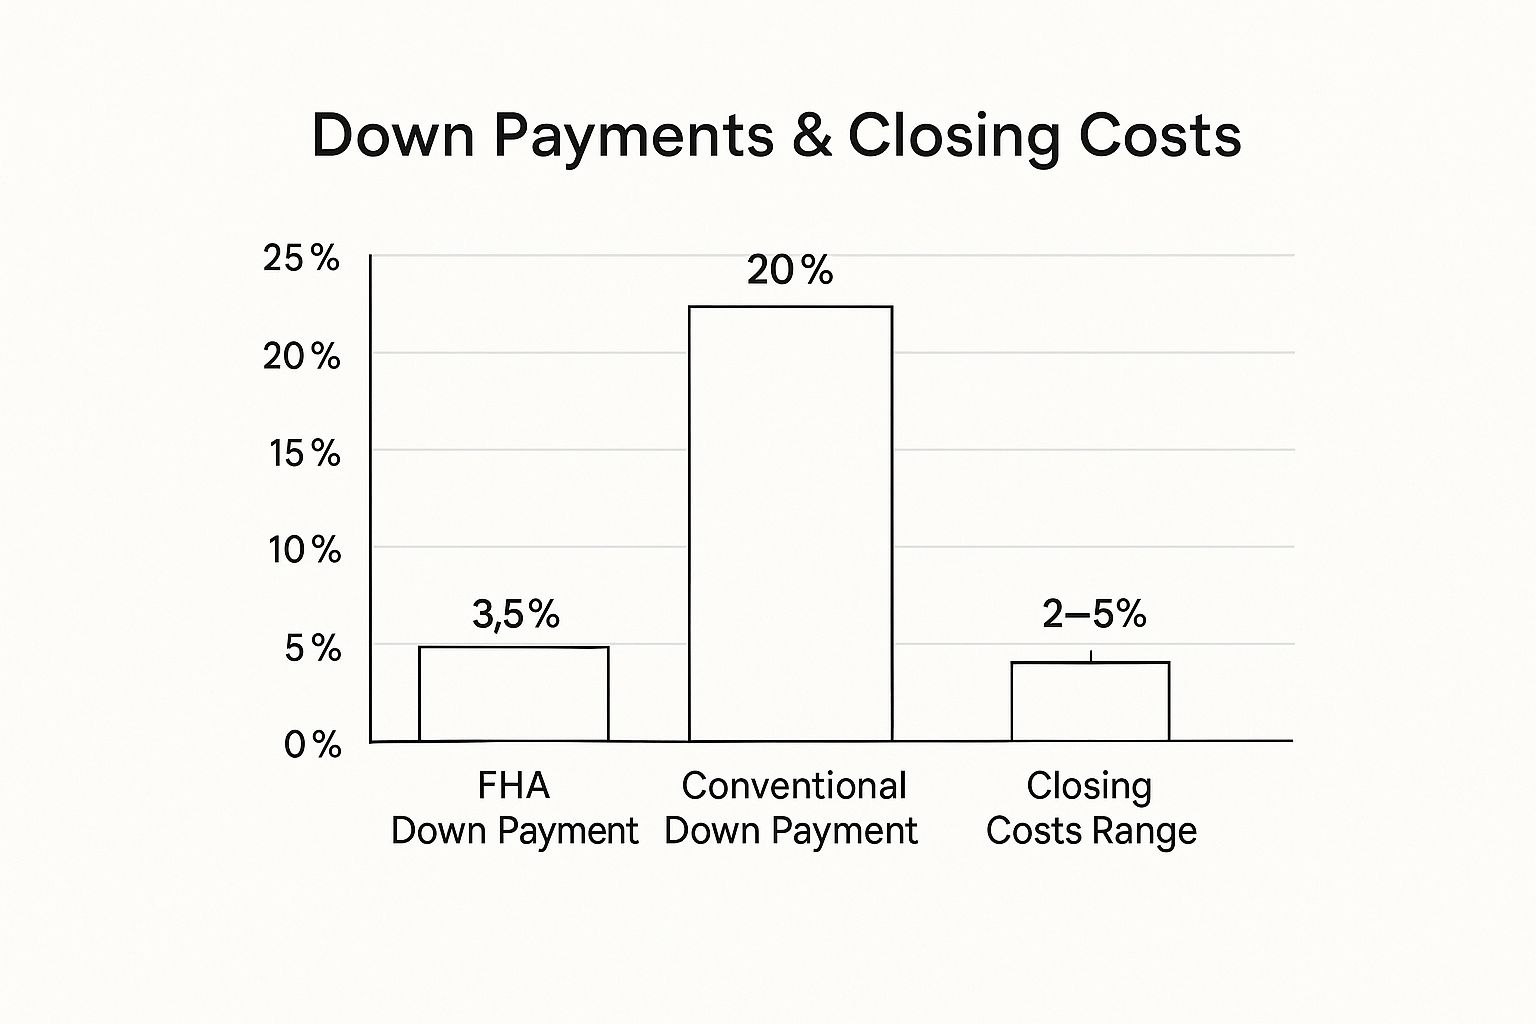
As the data shows, even with a low 3.5% down payment, a buyer must also have an additional 2-5% of the purchase price saved for closing costs. For example, a couple in Portland diligently saved for three years to put 20% down on their $300,000 home. Their $60,000 down payment allowed them to avoid costly monthly PMI and secure a lower interest rate, saving them thousands over the life of their loan. This demonstrates how a strategic savings plan is one of the most vital first time home buyer tips.
How to Strategically Save for Your Home Purchase
Building your savings requires a clear plan and disciplined execution. It’s about more than just setting money aside; it’s about optimizing your savings strategy and understanding all available resources to reach your goal faster.
Here’s how to build your funds effectively:
- Separate and Grow Your Savings: Open a high-yield savings account or a certificate of deposit (CD) specifically for your down payment. These accounts offer better interest rates than traditional savings, helping your money grow faster while keeping it safe and accessible.
- Explore Low Down Payment Programs: Don't assume you need 20%. Research first-time home buyer programs, such as FHA loans (3.5% down) or conventional 97 loans (3% down). For instance, a teacher in Denver used a state program to buy a $350,000 home with only 3% down. Military members and veterans should look into VA loans, which often require 0% down.
- Budget for Closing Costs Separately: Remember that closing costs, which typically range from 2-5% of the loan amount, are paid in addition to your down payment. On a $400,000 home, this could mean an extra $8,000 to $20,000. Budget for this as a distinct savings goal.
- Leverage Gift Funds and Assistance: Many loan programs allow you to use gift money from family for your down payment, provided it's properly documented. Also, check if your employer offers any homebuyer assistance programs, as some companies provide grants or loans to help employees purchase homes.
3. Check and Improve Your Credit Score
Your credit score is the financial backbone of your mortgage application. It's a three-digit number that lenders use to assess your creditworthiness, and it directly impacts your loan approval chances, the interest rate you'll receive, and even how much you'll pay for private mortgage insurance (PMI). Taking the time to understand and improve your score is one of the most impactful first time home buyer tips you can follow, potentially saving you thousands of dollars over the life of your loan.
Think of your credit score as your financial report card. A higher score tells lenders you're a responsible borrower, earning you a lower interest rate. For example, a buyer who spent six months improving their score from 640 to 720 could see their interest rate drop from 4.5% to 3.8%. On a $350,000 mortgage, that small difference can translate into over $40,000 in savings over 30 years. Even small, incremental improvements can have a significant long-term financial benefit.
How to Boost Your Credit Score for a Better Mortgage
Improving your credit score is a strategic process that requires patience and discipline. Starting this process at least six to twelve months before you apply for a mortgage gives you ample time to make meaningful changes. A strong score not only saves you money but also expands your loan options and strengthens your position as a buyer.
Here’s how to approach it effectively:
- Review Your Credit Reports: You are entitled to a free credit report from each of the three major bureaus (Experian, Equifax, and TransUnion) annually. Scrutinize these reports for any errors, such as incorrect late payments or accounts that don't belong to you, and dispute them immediately. Correcting inaccuracies is often the fastest way to boost your score.
- Lower Your Credit Utilization: Your credit utilization ratio, the percentage of available credit you're using, is a major factor in your score. Aim to pay down credit card balances to below 30% of their limits. For instance, if you have a card with a $10,000 limit, try to keep the balance under $3,000.
- Establish a Flawless Payment History: Your payment history is the single most important component of your credit score. Make it a priority to pay every single bill on time, every time, for at least six months leading up to your mortgage application. Set up automatic payments to ensure you never miss a due date.
- Avoid New Credit Inquiries: In the months before and during your home search, resist the temptation to open new credit cards, apply for a car loan, or finance large purchases. Each new application can trigger a "hard inquiry," which can temporarily lower your score and signal financial instability to lenders.
4. Research Different Loan Types and Programs
Once you have a handle on your finances, the next essential step is to understand the vast landscape of mortgage options. This is one of the most impactful first time home buyer tips because choosing the right loan can save you thousands over the life of your mortgage and make homeownership far more attainable. Many first-time buyers mistakenly assume there's a one-size-fits-all loan, but specialized programs and different loan types are designed to fit unique financial situations.
Exploring these options can be a game-changer. For example, a teacher in a designated rural area of Colorado was able to purchase her first home with a 0% down payment by using a USDA loan, a program she discovered through research. Similarly, a veteran family in San Diego leveraged their eligibility for a VA loan, allowing them to buy a home with no down payment and no private mortgage insurance (PMI). These programs exist to open doors for qualified buyers.
How to Navigate and Select the Best Loan
Dedicating time to research empowers you to ask lenders the right questions and confidently choose a loan that aligns with your long-term financial goals. This knowledge prevents you from overpaying or getting locked into unfavorable terms. While navigating financial products, it's always wise to be vigilant and aware of potential pitfalls; you can review these tips on how to avoid rental scams, as many of the same principles of due diligence apply.
Here’s a practical guide to your loan research:
- Compare Core Loan Types: Start by understanding the fundamentals. FHA loans, insured by the government, offer low down payments (as little as 3.5%) and are great for buyers with less-than-perfect credit. Conventional loans often require a higher credit score and down payment but may offer better long-term costs if you can avoid PMI. When exploring various financing options, a crucial aspect is understanding fixed rate mortgages, which offer predictable monthly payments.
- Investigate Government-Backed Programs: Beyond FHA, look into VA loans (for veterans and service members) and USDA loans (for homes in eligible rural areas). Both can offer 0% down payment options, providing a significant advantage for first-time buyers.
- Explore Local and State Assistance: Nearly every state and many cities have First-Time Home Buyer Assistance Programs. These can provide down payment assistance, closing cost grants, or even forgivable loans. A quick search for "[Your State] first time home buyer program" will reveal what's available to you.
- Look Beyond Big Banks: While national banks are a common choice, don't overlook local credit unions and mortgage brokers. Credit unions often have competitive rates and more personalized service, while brokers can shop your application to multiple lenders to find the best deal.
5. Understand All the Costs of Homeownership
Beyond the mortgage payment, a critical tip for any first-time home buyer is to understand that homeownership involves numerous ongoing and unexpected costs. The sticker price is just the beginning; the total cost of owning a home includes maintenance, taxes, insurance, and utilities, which can significantly impact your monthly budget. Failing to account for these expenses is a common pitfall that can lead to serious financial strain.
Think of your home's purchase price as the entry fee; the true cost of ownership is the monthly subscription. For instance, a new homeowner in Texas budgeted $300 a month for maintenance but was hit with an $8,000 roof repair in their first year. Similarly, a couple in Florida faced a sudden $12,000 HVAC replacement just two years after moving in. Understanding these potential expenses is crucial for long-term financial stability and a key aspect of making a smart purchase.
How to Budget for the True Cost of Your Home
Creating a comprehensive budget prevents surprises and ensures you can comfortably afford your new home without becoming "house poor." It involves looking past the mortgage to see the complete financial picture, which empowers you to make a more informed investment. To learn more about the long-term financial benefits, you can explore the reasons why buying single-family homes can be a good investment.
Here’s how to calculate and prepare for these costs:
- Plan for Maintenance and Repairs: A good rule of thumb is to budget 1-3% of your home's purchase price annually for maintenance. For a $400,000 home, this means setting aside $4,000 to $12,000 per year ($333 to $1,000 per month) for things like a new water heater or fixing a leaky pipe.
- Investigate Property Taxes and Insurance: Before making an offer, research the property tax rates in the area and get several homeowner's insurance quotes. These figures are part of your monthly payment and can vary dramatically by location.
- Estimate Utility Bills: Ask the seller for copies of past utility bills (electric, gas, water, and sewer) to get a realistic idea of monthly costs, which can fluctuate significantly with the seasons. A first-time buyer in Boston, for example, underestimated their winter heating costs, which topped $400 per month.
- Factor in Major System Upgrades: Pay close attention to the age of the roof, HVAC system, and water heater during the inspection. Even if they work now, knowing you may need a significant capital expense in a few years is vital. Understanding your window replacement financing options, for example, helps you plan for future energy-efficiency upgrades.
6. Get a Thorough Home Inspection
Once your offer is accepted, the work isn't over. One of the most critical first time home buyer tips is to invest in a professional home inspection. This is not a step to skip, even in a competitive market. A home inspection is a comprehensive, non-invasive examination of the home's condition, from the foundation to the roof, providing you with a detailed report on its systems and structural integrity.
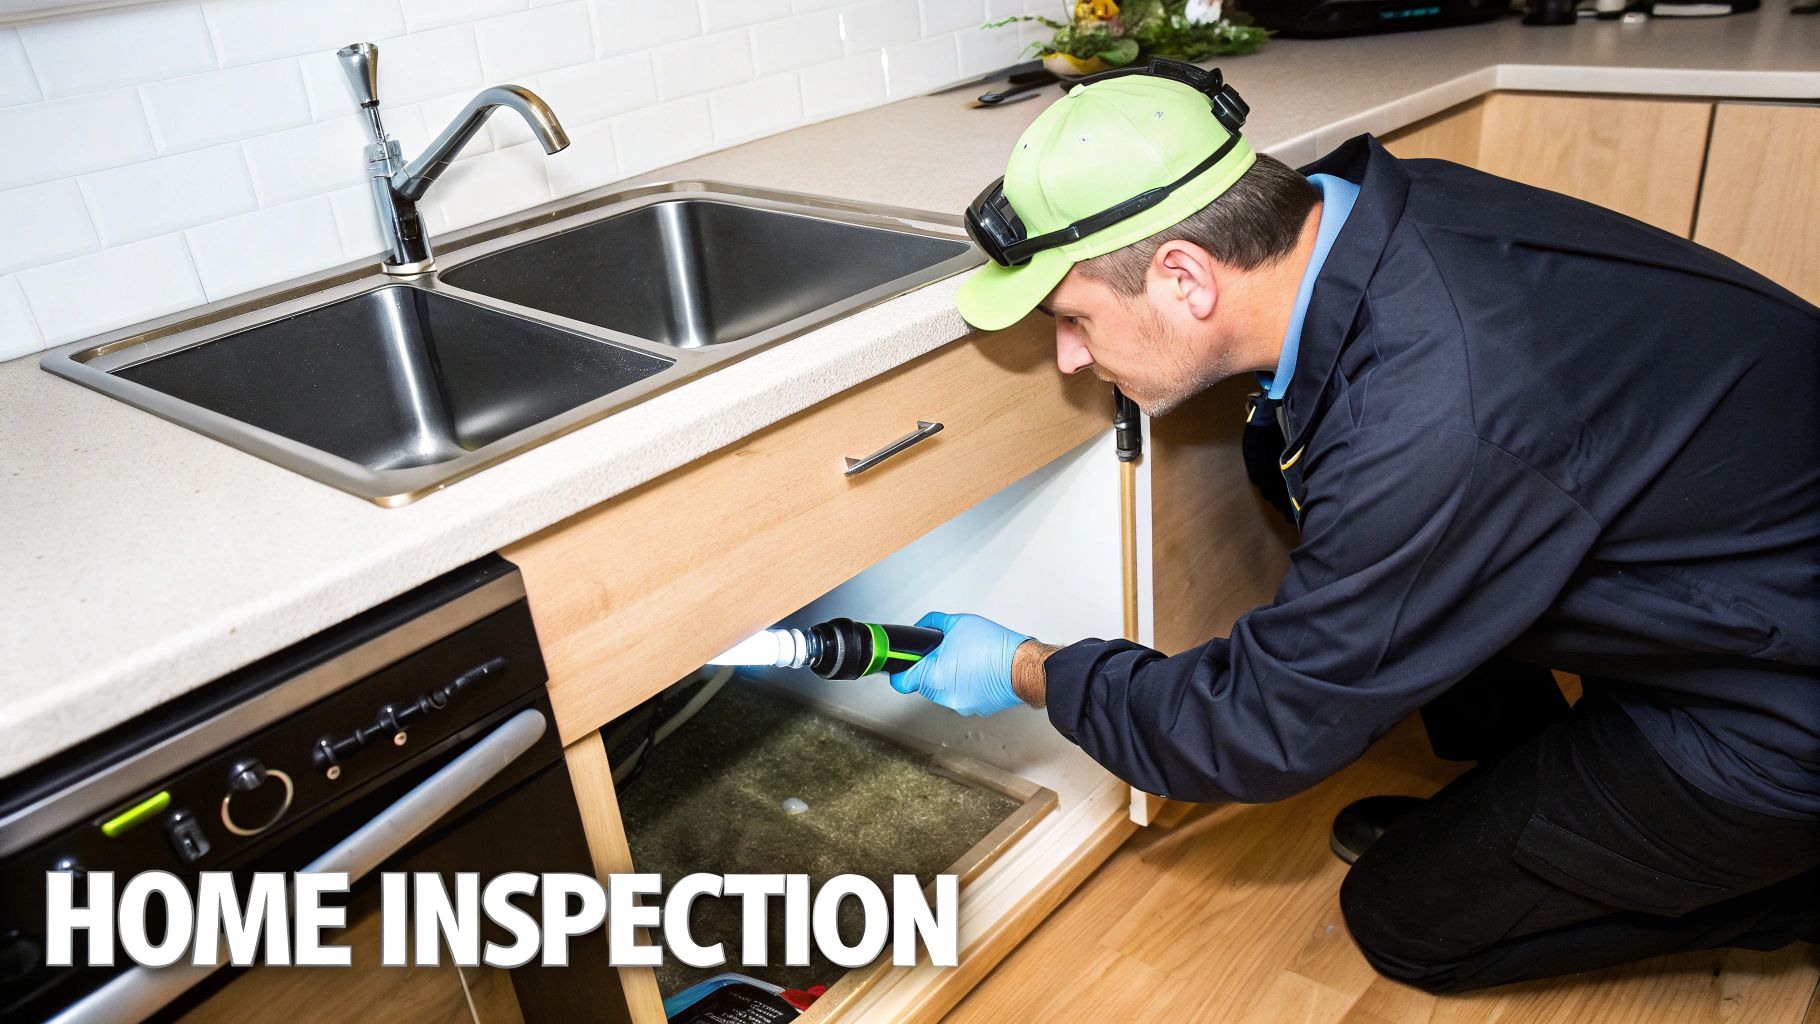
Think of the inspection as a vital diagnostic check-up before you finalize the largest purchase of your life. It can uncover potentially costly issues that are not visible during a casual walkthrough. For instance, a first-time buyer in Phoenix was able to walk away from a deal, saving themselves from financial disaster, after an inspection revealed significant foundation problems. In another case, a couple in Seattle used findings of an aging HVAC system to successfully negotiate $5,000 in seller credits toward a replacement.
How to Leverage Your Home Inspection
A home inspection contingency, typically lasting 7-10 days, gives you the power to negotiate repairs, ask for a price reduction, or even back out of the contract without losing your earnest money. It's your best tool for due diligence and protecting your investment.
Here’s how to approach it effectively:
- Choose a Qualified Inspector: Don’t just go with the cheapest option. Research and hire an experienced, certified inspector, ideally one affiliated with a reputable organization like the American Society of Home Inspectors (ASHI) or InterNACHI. Ask for sample reports to see their level of detail.
- Attend the Inspection: Be present during the inspection. This is your opportunity to see any issues firsthand, ask questions, and learn about the maintenance requirements of your potential new home. The inspector can point things out and provide valuable context that a written report alone cannot.
- Consider Specialized Inspections: Depending on the property's age, location, and features, you may need additional inspections. These can include tests for termites, radon, mold, lead paint, well water quality, or septic system functionality.
- Use the Report Strategically: After receiving the detailed report, discuss the findings with your real estate agent. Focus on major structural, safety, or system-related issues when negotiating with the seller, rather than minor cosmetic flaws. This approach is more likely to result in a successful resolution.
7. Work with Experienced Real Estate Professionals
Navigating the home buying process for the first time can be overwhelming, which is why surrounding yourself with the right team is one of the most essential first time home buyer tips. A skilled buyer's agent and a knowledgeable loan officer who specialize in working with new buyers can transform a stressful ordeal into a smooth, successful transaction. These professionals serve as your advocates, negotiators, and guides, handling complexities you may not even know exist.
The value of an experienced team cannot be overstated. For instance, an agent in Denver recently helped first-time buyers find an off-market property that perfectly fit their budget, avoiding a bidding war. In Miami, another buyer's agent successfully negotiated a $15,000 price reduction and seller-paid closing costs, saving their clients a significant amount upfront. Your team's expertise directly translates into tangible financial and emotional benefits, ensuring you make a sound investment.
How to Build Your Professional A-Team
Assembling the right professionals is about more than just finding someone with a license; it’s about finding partners who understand your specific needs as a first-time buyer. A great team will educate you, protect your interests, and provide the confidence needed to navigate the market. Exploring the benefits of hiring a Realtor can provide deeper insight into their critical role.
Here’s how to find the best professionals for your journey:
- Interview Multiple Agents: Don't settle for the first agent you meet. Interview at least three candidates and ask about their experience with first-time buyers, their familiarity with your target neighborhoods, and their communication style.
- Check References and History: A great agent will have a strong track record. Ask for references from recent first-time-buyer clients and look up their recent transaction history to confirm their expertise in your desired area and price range.
- Establish Clear Expectations: Discuss how you prefer to communicate (text, email, phone) and how often you expect updates. A clear understanding from the start prevents frustration later on.
- Understand Representation Agreements: Before signing anything, make sure you fully understand the terms of a buyer representation agreement. This contract outlines the agent's duties and your obligations, so it's crucial to know what you're agreeing to.
8. Don't Rush – Take Time to Find the Right Home
In a fast-paced market, the pressure to make a quick decision can be immense, but one of the most critical first time home buyer tips is to resist the urge to rush. Buying a home is one of the largest financial commitments you will ever make, and taking the time to find a property that genuinely fits your long-term needs, lifestyle, and budget is essential for future happiness and financial stability.
Rushing can lead to buyer's remorse when you discover unforeseen issues or realize the home doesn't suit you after all. For example, a family in Phoenix initially focused on a popular, overpriced neighborhood. By patiently expanding their search radius over a few months, they discovered an emerging area that offered a larger home, better amenities, and greater long-term value for their money. This strategic patience allowed them to make a smarter investment rather than settling due to market pressure.
How to Be Patient and Strategic in Your Home Search
A deliberate and thoughtful approach ensures you don't overlook major deal-breakers or compromise on what truly matters. This mindset transforms the house hunt from a frantic race into a well-managed project, empowering you to act decisively when the perfect opportunity arises.
Here’s how to conduct a patient yet effective search:
- Create a Needs vs. Wants List: Before you start viewing homes, create a detailed, two-column list. Needs are your non-negotiables (e.g., number of bedrooms, specific school district, a safe neighborhood). Wants are the features you’d like but can live without (e.g., a swimming pool, a finished basement). This list will be your north star, keeping you grounded and focused.
- Research Neighborhoods Thoroughly: Don't just drive through a neighborhood once. Visit at different times of the day and on different days of the week, including weekends. This will give you a real feel for the traffic, noise levels, and community vibe.
- Don't Let Emotions Rule: It's easy to fall in love with a home’s aesthetics, like a brand-new kitchen or a charming backyard. However, you must prioritize practical considerations like the roof's age, the HVAC system's condition, and the overall layout's functionality. Keep your "needs vs. wants" list handy during every showing.
- Be Prepared to Act Quickly on the Right Home: Being patient doesn't mean being slow. By doing your homework upfront and knowing exactly what you’re looking for, you’ll be able to recognize the right home immediately and submit a strong, confident offer without hesitation.
First-Time Home Buyer Tips Comparison
| Item | Implementation Complexity 🔄 | Resource Requirements ⚡ | Expected Outcomes 📊 | Ideal Use Cases 💡 | Key Advantages ⭐ |
|---|---|---|---|---|---|
| Get Pre-approved for a Mortgage | Moderate: requires documentation & credit check | Moderate: financial documents, credit report | Conditional loan commitment, stronger buyer position | Competitive markets, serious buyers | Speeds closing, confirms budget, improves negotiation |
| Save for Down Payment & Closing Costs | High: requires sustained savings effort | High: large cash amount needed | Lower monthly payments, avoids PMI | Buyers prioritizing loan terms & equity building | Higher equity, better seller leverage |
| Check and Improve Your Credit Score | Moderate to High: takes months to improve score | Low to Moderate: time, possible monitoring fees | Better interest rates, loan options | Buyers needing improved financing terms | Cost savings over loan life, more loan programs |
| Research Different Loan Types & Programs | Moderate: research required to compare options | Low: time for education, possible consultations | Access to specialized loans, better fits buyer profile | Buyers seeking tailored financing solutions | Saves money, access to assistance & flexible terms |
| Understand All the Costs of Homeownership | Moderate: requires budgeting & research | Low to Moderate: time to research and plan | Realistic budget, avoids surprises | Buyers budgeting for total homeownership costs | Prevents financial stress, supports emergency planning |
| Get a Thorough Home Inspection | Moderate: scheduling & attending inspection | Moderate: inspection fee ($300-$800) | Identifies defects, negotiation leverage | Every buyer, especially first-time | Prevents costly surprises, peace of mind |
| Work with Experienced Real Estate Professionals | Moderate: interviewing & selecting professionals | Low: mostly time, no direct cost to buyer | Expert guidance, smoother transactions | Buyers unfamiliar with process or market | Better deals, professional negotiation, expert advice |
| Don't Rush – Take Time to Find Right Home | Low to Moderate: time investment | Low: time and effort in viewings/research | Higher satisfaction, fewer buyer’s remorse | Buyers prioritizing fit & budget over speed | Avoid costly mistakes, better market understanding |
Ready to Find Your First Home?
Embarking on the journey to homeownership is one of the most significant milestones in your life. It's a path filled with complex decisions, detailed paperwork, and critical financial planning. By now, you've absorbed a comprehensive roadmap designed to demystify this process, transforming potential anxiety into actionable confidence. The collection of first time home buyer tips we've covered isn't just a checklist; it's a strategic framework for making a sound, rewarding investment in your future.
From the foundational steps of securing a mortgage pre-approval and meticulously saving for your down payment to the nuanced tasks of improving your credit and researching loan programs, you now understand that preparation is paramount. This initial financial groundwork sets the stage for everything that follows and is the single most powerful factor in determining your buying power and long-term financial health.
From Financial Prep to Finding "The One"
Once your finances are in order, the focus shifts to the practicalities of the hunt. We’ve highlighted the non-negotiable importance of a thorough home inspection, a crucial step that protects you from unforeseen and costly repairs down the line. It's the ultimate due diligence that separates a dream home from a potential nightmare.
Equally important is the team you build around you. Partnering with experienced real estate professionals, from a knowledgeable agent to a detail-oriented loan officer, provides you with invaluable guidance and advocacy. These experts navigate market complexities and contractual obligations on your behalf, ensuring your interests are always protected. Finally, we emphasized the virtue of patience. Rushing into a purchase is a common misstep, but by taking your time to find a home that truly fits your lifestyle and long-term goals, you ensure this massive investment is one you'll cherish for years to come.
Your Next Steps on the Path to Homeownership
The journey from aspiring buyer to proud homeowner is a marathon, not a sprint. The value of mastering these concepts lies in your ability to navigate the market with clarity and avoid the common pitfalls that trap many first-time buyers. You are no longer just dreaming of a home; you are actively building the foundation to acquire one intelligently.
Here are your immediate next steps, distilled from the core principles of this guide:
- Financial Health Check: Pull your credit report today. Identify areas for improvement and start making small, consistent changes.
- Create a Savings Plan: Use an online calculator to estimate your down payment and closing costs for your target home price. Automate your savings to make consistent progress.
- Start the Conversation: Reach out to a mortgage lender to understand your pre-approval potential. This provides a realistic budget and makes you a serious contender when you find the right property.
By following these first time home buyer tips, you are not just purchasing a property; you are making a deliberate, informed decision that will positively shape your financial future. The process may seem daunting, but with a solid plan and the right support system, you are more than capable of achieving your goal. You are equipped, you are prepared, and your first home is waiting.
If you're looking to buy in Fresno, Clovis, or the surrounding Central California area, having a local expert on your side is invaluable. The team at Edinhart Realty and Property Management specializes in guiding first-time buyers through every stage, providing the deep local knowledge and dedicated support needed to turn your homeownership dream into a reality. Contact us today to start your journey with a trusted partner.


