

Your offer was accepted. You're excited, a little relieved, and then the paperwork starts flying. Your agent says escrow is open, your lender talks about an escrow account, and suddenly it sounds like the same word means two different things.
That confusion is normal.
When people ask for the escrow process explained, they usually want one simple answer. But in real estate, escrow during the sale and escrow after closing are related ideas that do different jobs. If you're buying, selling, or taking over a rental property in California, understanding that distinction can save you stress and help you make better decisions.
What Is Escrow and Why Does It Matter
You can feel a deal is real when the offer is accepted. You can protect that deal when escrow opens.
In a California sale, transaction escrow is the neutral process that holds money, documents, and instructions until every agreed step has been completed. It works like a locked pass-through box. The buyer puts in the deposit. The seller signs transfer documents. The lender prepares funds. The title side clears issues. Nothing is released early, because the whole point is to protect both sides from handing over something valuable before the conditions are met.
A clear overview from the Consumer Financial Protection Bureau on closing and escrow explains the larger closing process that surrounds these handoffs.
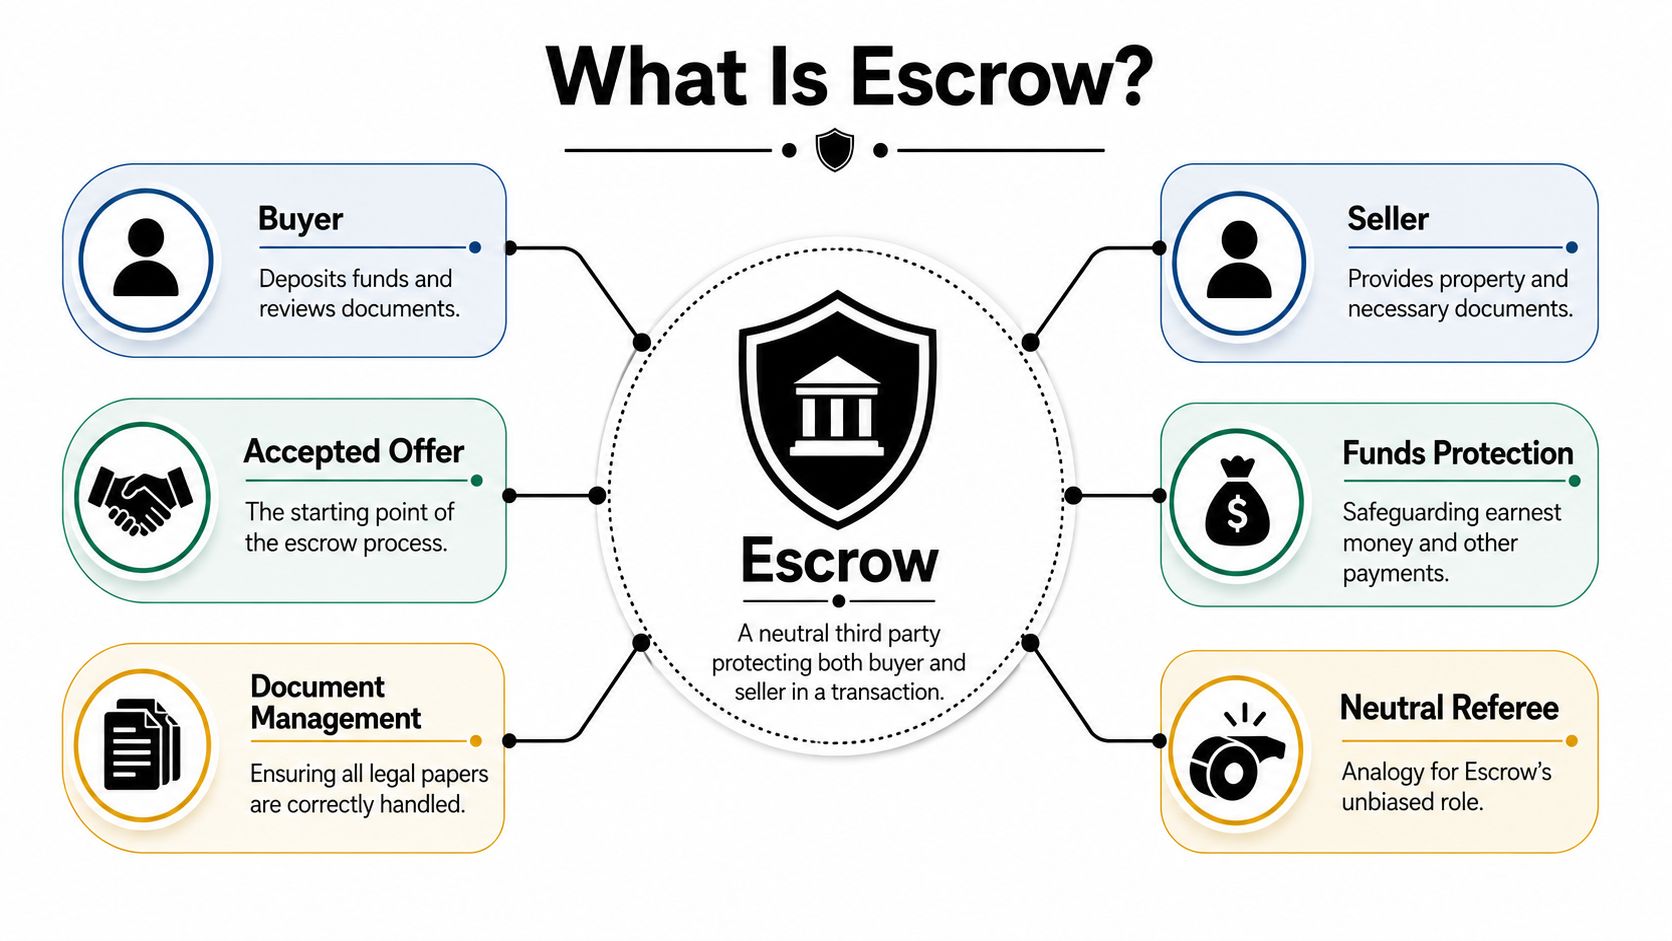
Transaction escrow versus mortgage escrow
This is the part that confuses first-time buyers, and plenty of sellers too.
Transaction escrow is the temporary holding process used to close the deal. In California, the escrow holder follows written instructions, receives funds, coordinates signatures, and helps make sure title and money change hands in the right order. If you are comparing local providers, this overview of Fresno title companies and escrow-related services can help you understand who may be involved.
Mortgage escrow is different. After closing, many lenders collect part of your monthly payment for property taxes and homeowners insurance, then pay those bills from a separate escrow account. Same word, different job. One helps you close. The other helps you budget and stay current after you own the property.
That distinction helps buyers ask better questions, helps sellers understand lender timing, and helps landlords read settlement statements and future payment schedules without mixing the two together.
Why the system exists
Real estate involves trust, but it cannot run on trust alone. A buyer needs time to inspect the property and review disclosures. A seller needs proof that the buyer is serious and able to perform. A lender needs clear title and signed documents before sending money. Escrow creates the controlled holding place for funds and instructions so each step happens in the proper sequence.
That protection is especially important with the earnest money deposit. The deposit shows good faith, but it is not a prize that the seller automatically gets or a check the buyer can freely pull back without consequences. Its release depends on the contract terms, deadlines, and whether contingencies were removed. For a useful comparison outside the U.S., this guide to home buying earnest money in Australia shows how similar concepts work in another market.
For California buyers, sellers, and landlords, the practical value of escrow is simple. It reduces the chance of money moving too soon, title transferring with unresolved problems, or a closing falling apart over missing paperwork. In a transaction involving your home or investment property, that structure is not red tape for its own sake. It is there to protect the investment.
The Key Players in Your Escrow Journey
Real estate escrow works better when you know who's responsible for what. Most confusion comes from asking the wrong person the right question.
The buyer and seller
The buyer brings in the deposit, completes inspections, applies for financing, reviews disclosures, and signs loan and closing documents. The buyer's main job is responsiveness. A missing bank statement or delayed signature can hold up the whole file.
The seller provides disclosures, cooperates with title and payoff requests, negotiates repairs if needed, and signs transfer documents. Sellers also need to keep the property in agreed condition through closing.
The escrow officer and title side
The escrow officer is the neutral party in the middle. This person doesn't represent the buyer or the seller. Instead, the escrow holder follows written instructions, receives and disburses funds, coordinates signatures, and helps move the file toward recording.
In California, buyers and sellers often work with independent escrow companies or title-related settlement teams. If you're comparing local options, a practical starting point is this overview of Fresno title companies.
The agents and lender
Your real estate agents guide the transaction from the contract side. They track deadlines, negotiate repairs or credits, help interpret disclosures, and keep communication moving. A good agent isn't replacing escrow or the lender. They're making sure all three tracks stay aligned.
The lender focuses on the loan file. That includes verifying income, assets, credit, property value, and final conditions before funding.
Here's a simple way to think about the team:
| Role | Primary focus | When you usually contact them |
|---|---|---|
| Buyer's agent | Contract deadlines and negotiation | Questions about contingencies, repairs, timing |
| Seller's agent | Listing side coordination and responses | Seller disclosures, access, negotiation |
| Escrow officer | Funds, documents, signing coordination | Deposits, wires, signatures, closing logistics |
| Lender | Loan approval and funding | Mortgage conditions, underwriting, closing funds |
| Buyer or seller | Timely decisions and documents | Throughout the transaction |
When a buyer asks, “Why hasn't escrow closed yet?” the answer often sits with a lender condition, a title item, a missing signature, or an unresolved repair issue. It usually isn't one person stalling the process. It's the chain waiting for one missing link.
The Escrow Timeline A Step-by-Step Guide
You sign the purchase agreement, send your deposit, and then the waiting starts. For many first-time buyers and sellers, escrow can feel quiet on the surface while a lot is happening underneath. The clearest way to reduce that anxiety is to know the sequence, who is working on what, and which delays are normal.
In California, a residential escrow often moves in a matter of weeks, but the calendar depends on financing, title issues, inspections, and how quickly each party responds. The date on the contract matters. Understanding the work between day one and closing matters more.
A quick visual can make the sequence easier to follow.
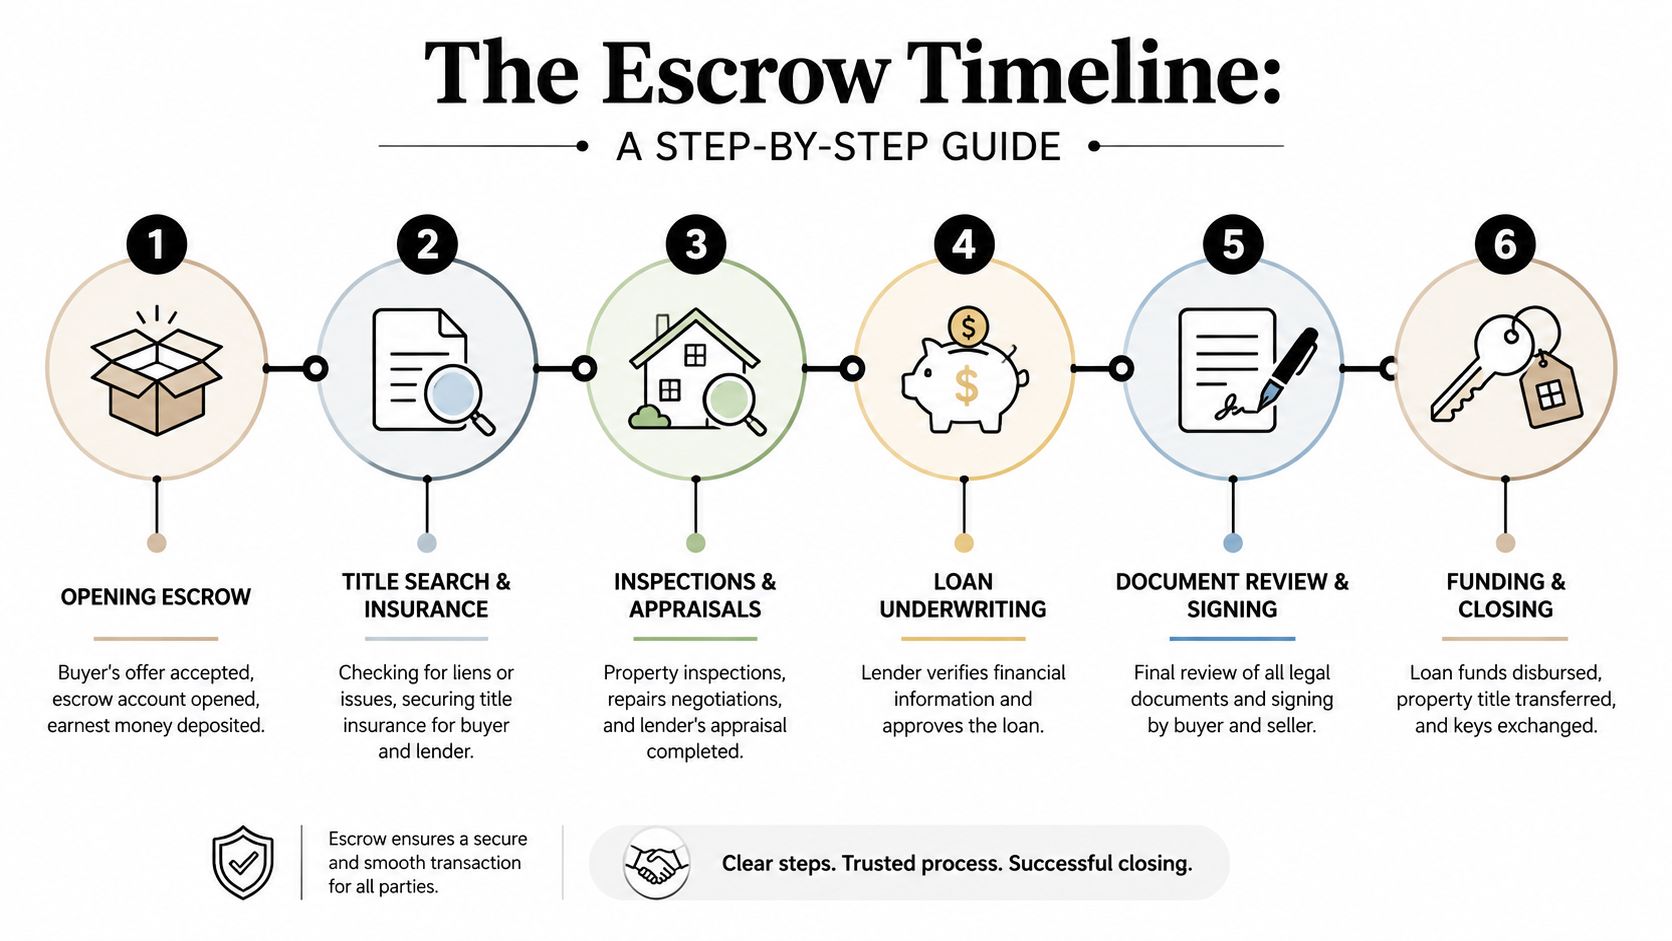
1. Opening escrow
Escrow opens after the seller accepts the contract. The escrow holder receives the agreement, creates the file, and begins following the written instructions tied to the sale. The buyer then delivers the initial deposit based on the contract terms.
If you want a plain-English refresher on that deposit, this guide to the earnest money deposit in a home purchase helps.
This stage works like opening a secure folder for the transaction. Money, signatures, and instructions now have one controlled place to go. That protects both sides because no one is relying on informal promises alone.
2. Title work and seller paperwork
Next, the title side reviews the property's history. They look for liens, unpaid taxes, recording errors, easements, or ownership questions that could interfere with transfer.
At the same time, the seller completes disclosures and provides the documents required by the contract. In California, that paperwork can feel heavy, but the reason is simple. Buyers need a fair picture of the property before they take ownership, and sellers want clear proof that they disclosed what they were required to disclose.
If you have seen property transfers handled outside the U.S., the timing can look different. This comparison of how long conveyancing takes in UK shows how another system handles the legal side of a closing.
3. Inspections, appraisal, and contingencies
This is the buyer's investigation period. Inspectors evaluate the home's condition. The buyer reviews reports, the seller may answer repair requests, and the lender orders an appraisal if financing is involved.
A lot of first-time buyers confuse a home inspection with an appraisal. They serve different jobs. The inspection helps the buyer understand condition and future repair risk. The appraisal helps the lender decide whether the property supports the loan amount.
This is also a good place to clear up another common mix-up. Transaction escrow is the closing process described here. Mortgage escrow is different. That is the account some lenders use after closing to collect property taxes and insurance with the monthly payment. One helps close the deal. The other may help manage ongoing housing costs after the deal has already closed.
Some transactions stay on schedule here. Others slow down because the parties need to resolve a roof problem, negotiate a credit, or respond to a low appraisal.
4. Loan processing and underwriting
For financed purchases, the lender now examines income, assets, credit, and the property file in detail. Buyers often feel like they are sending the same bank statement or pay stub more than once.
That happens because documents can expire, underwriters may ask for updated versions, and one new item can create another condition. The lender is checking whether the file meets every lending requirement before funds are released.
Fast communication helps. So does organization.
For a short walk-through of the big stages, this video is helpful:
5. Final review and signing
Once the major conditions are satisfied, the closing figures are finalized and signing appointments are set. The buyer signs loan documents. The seller signs transfer documents and other escrow papers needed to complete the sale.
Before signing, slow down and check the details:
- Names and vesting: Confirm legal names and how title will be held.
- Wire instructions: Verify them through a trusted phone number or known contact.
- Property condition: Complete the final walk-through to confirm the home is in the agreed condition.
- Closing funds: Know what amount must be delivered and when.
Small mistakes at this stage can hold up recording. A missing signature, a vesting error, or funds sent late can delay closing even when everything else looks ready.
6. Funding, recording, and disbursement
Signing is a major milestone, but it is not the finish line. The lender still needs to fund the loan, escrow needs to confirm receipt of money, and the deed must be recorded with the county before ownership officially changes.
After recording, escrow disburses funds based on the written instructions. That usually includes paying off the seller's existing loan, sending commissions, paying closing costs, and delivering the seller's net proceeds.
In California, recording is the moment many buyers have been waiting for. It is also the point where the practical distinction matters again. Transaction escrow ends when the sale closes and funds are properly disbursed. Mortgage escrow, if the lender requires one, may begin after that and continue as part of the buyer's monthly payment for taxes and insurance.
If you want local help keeping those steps aligned, Edinhart Realty and Property Management works with buyers, sellers, and property owners in the Fresno area on purchase, sale, and management coordination.
Understanding Escrow Documents and Costs
People usually don't get nervous about escrow because of the concept. They get nervous when they see a stack of forms and a list of fees.
The simplest way to reduce that stress is to sort documents into two groups: papers that explain the deal, and papers that move the deal.
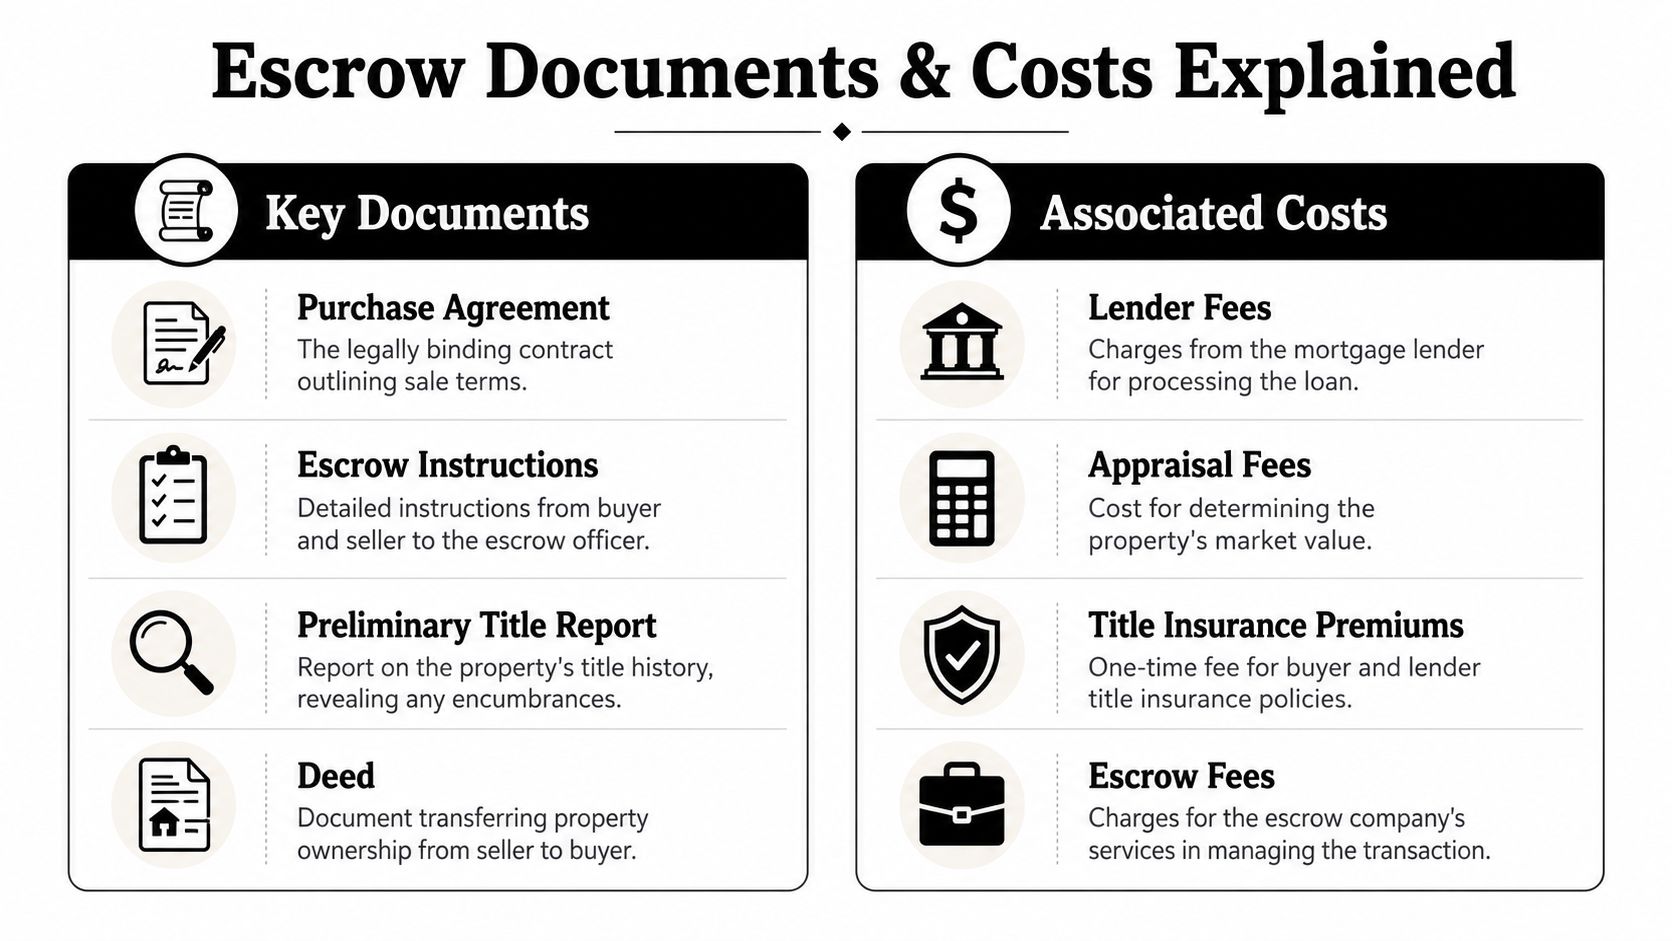
The documents that matter most
The purchase agreement is the roadmap. It spells out price, timelines, contingencies, and who is expected to do what.
The escrow instructions tell the escrow holder how to handle money and documents once conditions are satisfied.
The preliminary title report helps identify title issues before closing. If you're new to title coverage, this plain-English explanation of how land title insurance works for buyers is a useful companion read.
The deed is the transfer document that moves ownership from seller to buyer.
Buyers also need to pay close attention to the lender's final numbers. And if you want a separate primer on the deposit that starts the file, this explanation of earnest money deposit basics helps connect the contract stage to escrow handling.
Where the money goes
In a standard residential purchase, escrow acts as a neutral control layer that holds the buyer's earnest money, lender proceeds, and signed transfer documents until all contractual conditions are satisfied, and the earnest money is often 1% to 3% of the purchase price according to Freedom Title's buyer escrow guide.
Closing costs vary by transaction, loan, and local custom, but they commonly fall into a few buckets:
- Lender-related charges: These cover mortgage processing and loan setup.
- Title and escrow fees: These pay for settlement coordination, title review, and related closing services.
- Appraisal and inspection charges: These support the buyer's property and loan review.
- Recording and prepaid items: These include county recording and certain advance payments collected at closing.
Who pays what
In California, cost allocation often depends on local custom and the purchase contract. Some fees are negotiated. Others are tied to the buyer's financing or the seller's payoff obligations.
The question isn't “What do buyers always pay?” or “What do sellers always pay?” The better question is “What does this contract assign, and what does the settlement statement actually show?”
That's why reviewing final figures early matters. Small line items can add up, and the cleanest closings happen when both sides understand the settlement statement before signing day.
Navigating Contingencies and Common Delays
You are two weeks into escrow. The inspection report lands in your inbox, the lender asks for one more document, and the appraisal is still pending. For a first-time buyer or seller, that can feel like the deal is slipping. In reality, this is often the part where escrow does its real job. It holds the transaction in place while the loose ends are checked, documented, and resolved.
That distinction matters because people often mix up transaction escrow with mortgage escrow. Here, we are talking about transaction escrow, the temporary process that helps a sale close safely. Mortgage escrow is the ongoing account some owners have for property taxes and insurance after closing. Different purpose, different timeline.
A contingency is one of the main tools that keeps transaction escrow fair. It gives the buyer a defined period to confirm the property, financing, disclosures, or title before becoming fully committed. In plain terms, contingencies work like inspection points on a long road trip. You do not stop because the car is failing. You stop because checking the engine now is cheaper than dealing with a breakdown later.
Where delays usually come from
Some delays are ordinary and short. Others need quick judgment from both sides.
- Inspection findings: A report may uncover roof issues, plumbing leaks, or safety concerns. Then the parties need to decide whether the seller will repair, offer a credit, or hold firm.
- Low appraisal: If value comes in under the contract price, the buyer and seller may need to renegotiate price, change loan terms, or bring in additional cash.
- Loan conditions: Underwriters often ask for updated bank statements, payroll records, or explanations for large deposits. A buyer who responds slowly can stall the file.
- Title issues: Old liens, payoff errors, unreleased reconveyances, or vesting mistakes can delay signing or recording.
- Disclosure review: In California, disclosure packages are a major part of the timeline. Sellers who prepare early usually reduce last-minute conflict. Buyers who read everything early have more time to ask clear questions. Sellers can avoid some of those slowdowns by reviewing their California seller disclosure requirements before the property goes into contract.
Timing matters here. A problem found on day three is usually easier to solve than the same problem found the night before closing.
How buyers, sellers, and landlords can keep escrow on track
Each side has a job to do.
- Buyers: Send requested documents fast, schedule inspections early, and avoid major financial changes until the loan is fully approved and the deal has closed.
- Sellers: Complete disclosures carefully, answer repair requests with specifics, and make sure payoff information for any existing loans is accurate.
- Landlords and rental property sellers: Have leases, deposit records, rent ledgers, and tenant-related paperwork organized early. Those items can affect credits, prorations, and buyer review.
In California, escrow delays often come from preventable silence. Someone has the document. Someone assumes the other party already saw it. Then a deadline gets close. Good agents, escrow officers, and lenders keep the file moving by asking early, following up often, and clearing issues while there is still room to solve them.
Contingencies protect the investment because they turn assumptions into verified facts before money and title change hands.
For sellers, a buyer asking for time to inspect, confirm financing, and review title is usually doing exactly what the contract expects. For buyers, removing contingencies should feel less like a leap and more like checking off boxes you understand. That is the point of escrow. It creates a controlled process so decisions are made with evidence, not guesswork.
California Escrow Notes and Landlord Tips
California has its own rhythm. In many transactions here, buyers and sellers work with an independent escrow company that acts as the neutral holder of funds and documents, while agents, lenders, and title professionals each handle separate pieces of the file.
California transactions also come with a disclosure-heavy culture. If you're selling, those forms matter because they reduce surprises later. If you're buying, they're one of the best tools you have for understanding the property before contingencies are removed. Sellers who need a refresher on paperwork should review this guide to California seller disclosure expectations.
For landlords and investors
When a rental property changes hands, escrow can also become a bookkeeping bridge. Rent may need to be prorated between seller and buyer as of the close date. Security deposits and tenant-related credits may need to be transferred and accounted for correctly. Tenant communication should be coordinated so the resident knows where future rent payments go and who manages the property after closing.
Then there's the second kind of escrow discussed earlier: mortgage escrow. For landlords and owner-occupants alike, this can affect monthly cash flow long after the purchase closes. CFPB rules require servicers to analyze escrow accounts for surplus, shortage, or deficiency and allow shortages to be repaid over at least 12 months, which means monthly payments can rise even when principal and interest stay unchanged, as described in CFPB Regulation X escrow analysis rules.
That matters a lot for rental owners. Your mortgage payment can change because taxes or insurance changed, even if your rent didn't.
Escrow FAQs and Your Next Steps
What happens to my earnest money if the deal falls through
It depends on why the deal falls through and what the contract says. If a cancellation happens within a valid contingency period or under another contract right, the deposit is often handled according to those written terms. If there's a dispute, escrow won't usually guess. The escrow holder waits for signed instructions or other proper direction before releasing funds.
Can I back out during the contingency period
Sometimes, yes, if the contract gives you that right and you act within the required timeline. The key is not to assume. Deadlines matter, and so do the written notice procedures in the contract. Talk with your agent right away if you're considering cancellation.
What is an escrow holdback for repairs
An escrow holdback is an arrangement where part of the funds is held back to address a specific unresolved item after closing. It isn't part of every transaction. When it does come up, the terms need to be very clear about who does the work, how much money is held, and when those funds are released.
If you're buying your first home, selling one in Fresno or Clovis, or sorting out an investment property transfer, the escrow process gets easier when each deadline, document, and dollar has a clear owner.
If you want help navigating a purchase, sale, or rental transition in Central California, Edinhart Realty and Property Management can help you move through escrow with clear guidance on disclosures, timelines, local practices, and property-related decisions before and after closing.


