

You're probably looking at three different numbers right now. One from Zillow. One from a neighbor who “knows what homes are going for.” One from your own gut after remembering what you spent on upgrades.
That's where most pricing mistakes start in Fresno.
A homeowner in Fig Garden sees one estimate online, then hears a different number from a friend in Clovis, then wonders whether the remodel, the pool, or the corner lot should push the price higher. An investor with a rental near Fresno State has a similar problem. The question isn't just what the property could rent or sell for, but rather what the current market will support right now.
That's why a comparable market analysis matters. It replaces guesswork with a method. Instead of relying on broad estimates, it compares your property to homes that competed in the same local market. If you're selling, that helps you avoid sitting too high or giving the home away too low. If you're renting, it helps you position the property against current inventory instead of last year's memory.
Pricing correctly from day one has a big effect on how buyers and tenants respond, which is also the point behind LendingXpress hard money advice. For homeowners who want a practical look at sale pricing specifically, Edinhart's guide on how to price a home for sale is also useful.
How Much Is My Fresno Home Really Worth
In Fresno, that question usually shows up before a sign goes in the yard.
A seller might own a well-kept ranch home near Bullard and think the upgraded kitchen should carry the whole pricing decision. Another owner in North Fresno may assume their neighborhood alone guarantees a premium. A landlord may look at asking rents online and miss the difference between what owners hope to get and what qualified tenants are accepting.
What homeowners usually see first
A common starting point is public listing sites. That makes sense. They're fast, familiar, and easy to pull up on a phone. The problem is that they flatten important differences.
A house in the Tower District and a newer home in a planned Clovis-area community can share similar square footage and still attract very different buyers. One may win on character and lot feel. The other may win on layout, age, and finish level. If you price them like interchangeable boxes, you'll miss the market.
The market doesn't pay for features in the abstract. It pays for features in a specific neighborhood, at a specific moment, against specific competing homes.
What a real answer looks like
A useful value opinion has to answer practical questions:
- Who is the likely buyer or tenant? A family, an investor, a first-time buyer, or someone relocating from another part of Central California.
- What nearby properties created competition? Not just nearby homes, but nearby homes that were similar enough to influence a decision.
- How does your property compare once condition is stripped out from emotion? Fresh paint matters. So does deferred maintenance.
- What price creates activity instead of resistance? The goal isn't to “test the market.” It's to meet it.
In Fresno and the surrounding area, pricing isn't hard because the concept is complicated. It's hard because local variation is real. One street can trade differently from the next. A school boundary, lot orientation, or level of updating can change the conversation fast.
That's why professionals rely on a CMA instead of a rough estimate.
What Is a Comparable Market Analysis
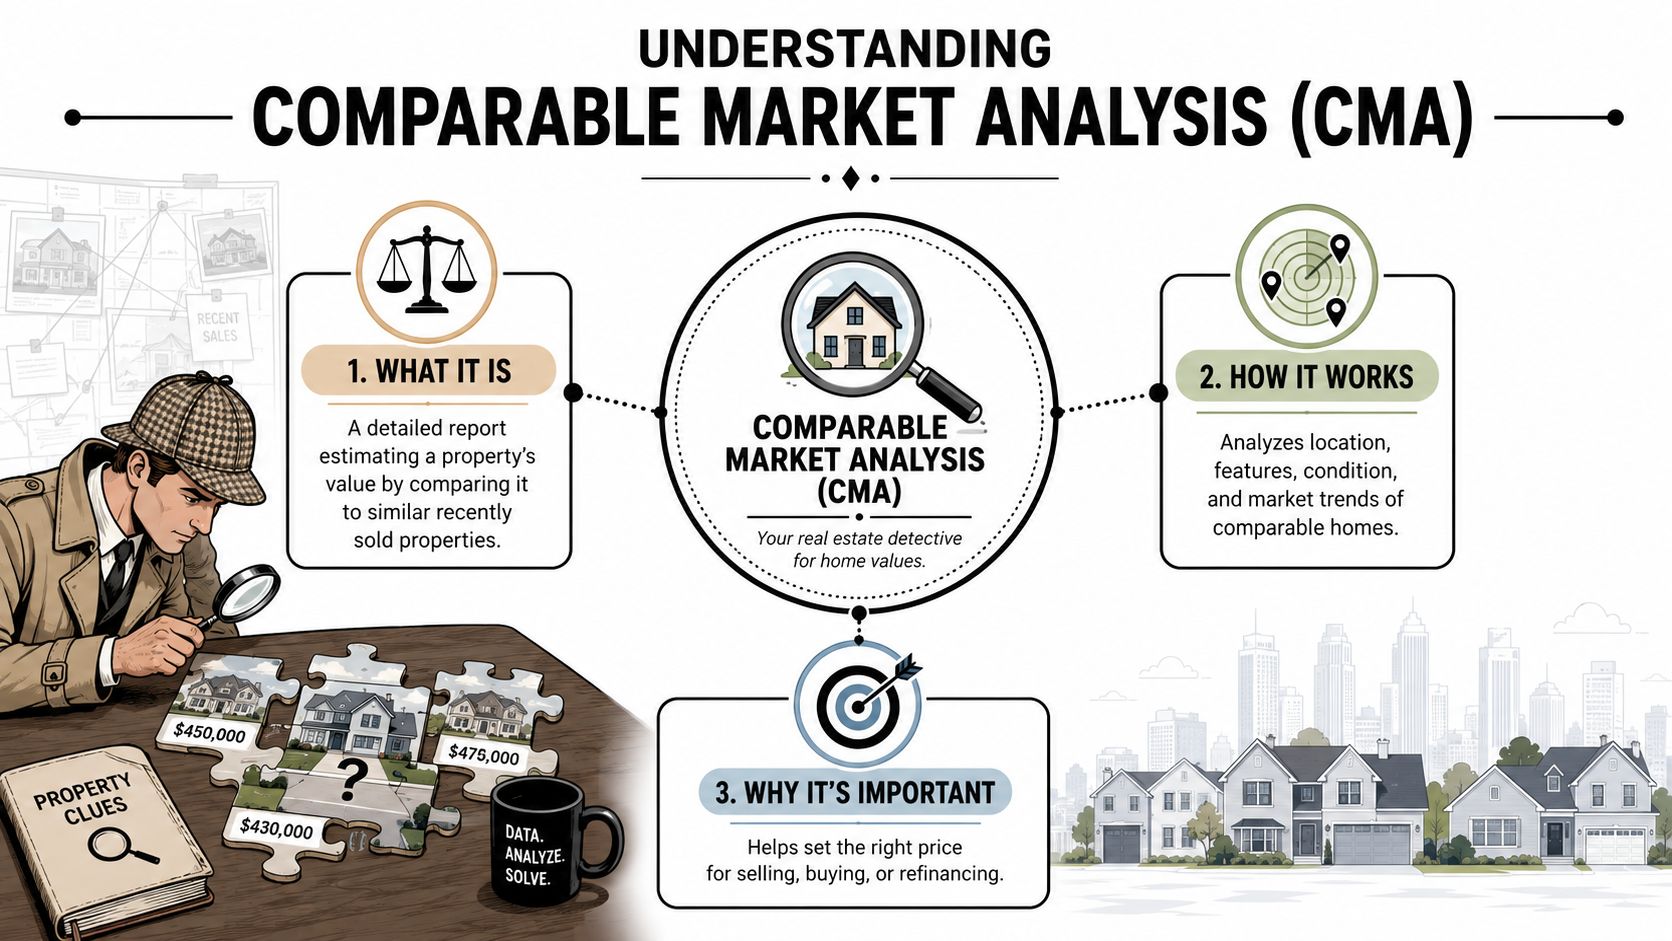
A comparable market analysis, or CMA, is a structured way to estimate a property's market value by comparing it to similar properties that have recently sold nearby. This process involves building a market profile for a unique product: your house.
A good CMA doesn't ask, “What would I like to get?” It asks, “What have buyers paid for homes that compete with this one?”
The core of the process
A high-quality CMA starts with a small, tightly matched comp set, usually 3 to 5 comparable properties sold within the last 3 to 6 months, because those sales reflect what buyers paid. Active and pending listings can also help show current competition and near-term direction, as Zillow explains in its guide to a high-quality comparable market analysis.
That matters in Fresno because pricing conditions can shift block by block and season by season. If a property near Woodward Park has stronger current competition than a similar home farther west, that affects strategy.
What goes into a CMA
A real CMA studies the details buyers react to, not just the headline square footage. The usual review includes:
- Location fit. Same neighborhood, school draw, street type, and surrounding feel.
- Physical match. Size, lot, bedroom and bath count, age, and style.
- Condition. Original finishes, partial updates, full remodel, or obvious wear.
- Features. Pool, garage setup, landscaping, patio use, and other selling points.
- Market context. What sold, what's pending, and what current listings are trying to compete.
Why this works better than broad estimates
Online estimates can be fine for a rough starting point. A CMA is where pricing becomes usable.
It connects value to actual behavior in the market. If buyers recently chose one type of layout over another, or consistently paid more for updated homes in one part of Fresno than another, the CMA catches that. It also helps investors think beyond sale price. The same comparison logic can shape rent positioning, turnover strategy, and renovation decisions.
Practical rule: If the properties you're comparing wouldn't realistically attract the same buyer or tenant, they probably aren't true comps.
That's the difference between a number and a pricing strategy.
CMA vs Appraisal vs Automated Valuation
Property owners mix these up all the time. They shouldn't. A CMA, an appraisal, and an automated valuation model all deal with value, but they serve different jobs.
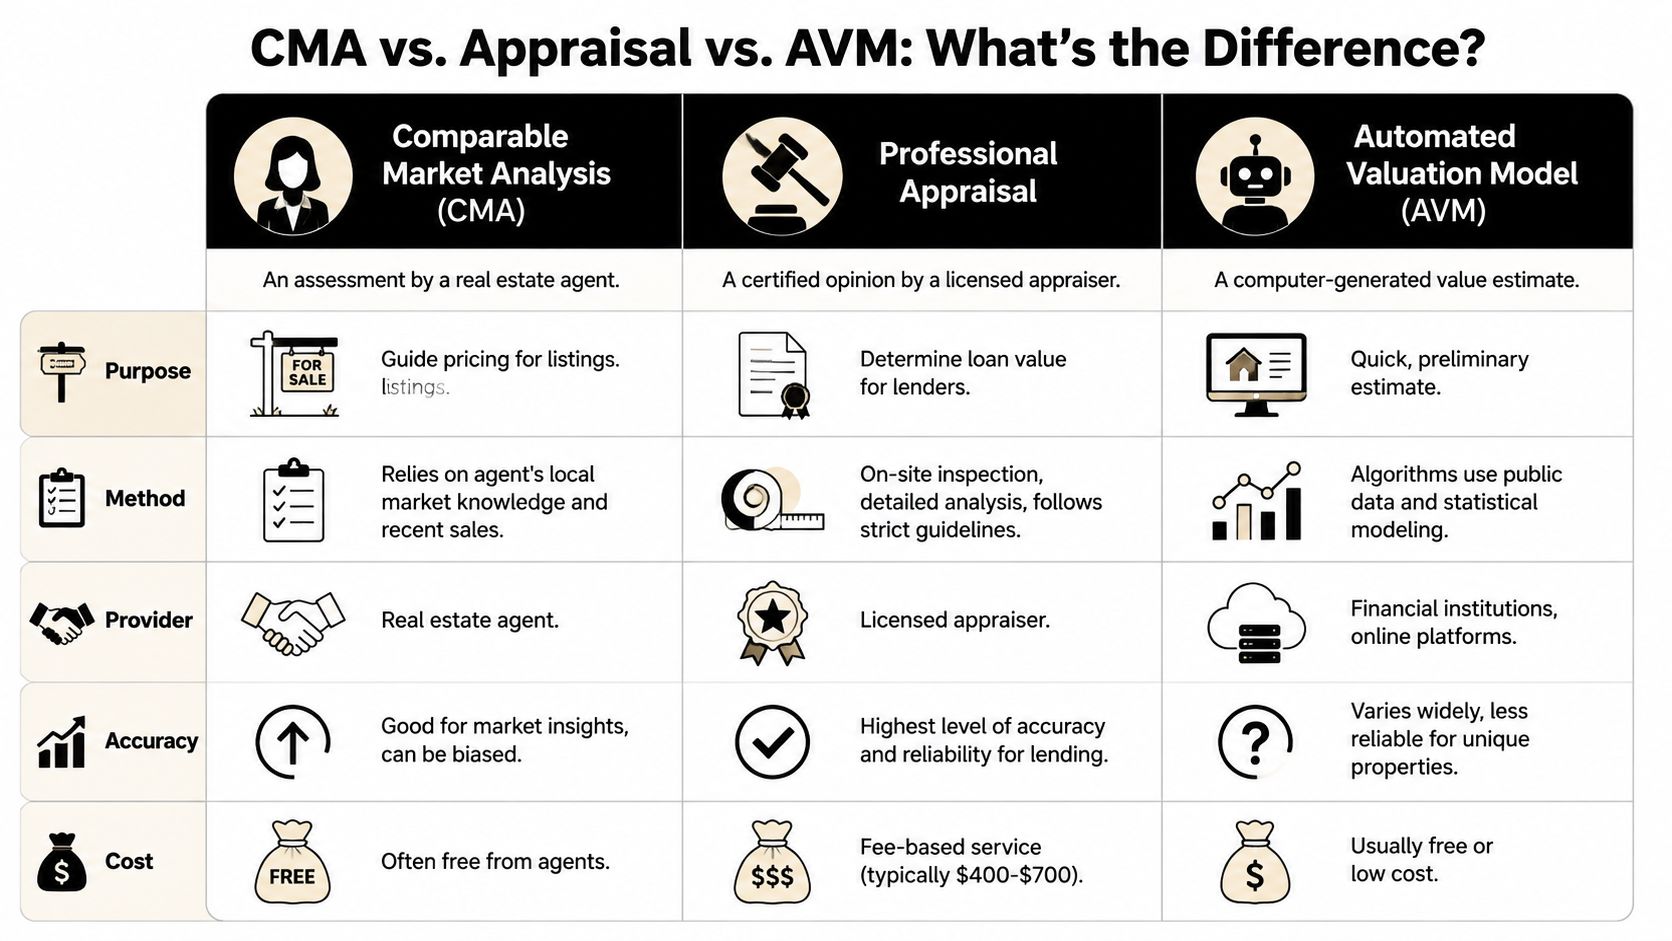
Start with the simplest distinction. A CMA is a pricing tool. An appraisal is a formal valuation for lending. An automated valuation model, or AVM, is a machine-generated estimate based on available data.
Here's the side-by-side view most owners need.
The main difference in plain language
A CMA is usually prepared by a real estate agent or broker to help set a listing price, evaluate an asking price, or support a rental strategy. A formal appraisal is completed by a licensed appraiser and is commonly required by lenders. That distinction is outlined clearly by Kaplan in its discussion of CMA versus appraisal.
In practice, that means each tool answers a different question.
| Tool | Best use | Who creates it | What to watch for |
|---|---|---|---|
| CMA | Listing strategy, offer planning, rental pricing logic | Agent or broker | Quality depends on comp selection and local judgment |
| Appraisal | Loan underwriting and formal value opinion | Licensed appraiser | Built for lender requirements, not always marketing strategy |
| AVM | Fast estimate for early research | Algorithm or platform | Can miss condition, layout, micro-location, and upgrades |
A Zestimate-style number can be useful at the very beginning. It can tell you where to start asking questions. It shouldn't be the final answer for a Fresno property with unique condition, lot characteristics, or neighborhood nuance.
Where owners get tripped up
Sellers often treat the highest number they see as the “real” value. That's backwards. Different tools produce different numbers because they're built for different purposes.
A lender's appraiser isn't trying to help you attract showings in the first week of marketing. An AVM isn't walking through your kitchen, noticing your deferred maintenance, or seeing the traffic pattern on your street. A CMA should account for those things because it's built around competition and positioning.
Here's a useful explainer if you want a quick visual breakdown before reading further.
Which one should you rely on
That depends on the decision in front of you.
- Selling soon. A CMA is usually the practical first step.
- Refinancing or financing a purchase. The lender's appraisal will carry the formal weight.
- Checking value casually online. An AVM is fine as a rough snapshot, but not as a pricing plan.
If you're deciding how to enter the market, use the tool built for strategy, not the tool built for convenience.
That one distinction saves a lot of Fresno owners from expensive pricing mistakes.
How to Select Great Comps in Central California
Good pricing starts with good comps. Weak comps ruin the whole analysis.
In Central California, local knowledge matters most. A house can look “close enough” on paper and still be a bad comp because the buyer pool is different. That happens all the time between older established neighborhoods and newer tract developments.
Start tight, then widen only if needed
For a comparative market analysis, analysts usually look for properties within about 300 square feet of the subject property, using sales from the last 3 to 6 months and often within about a one-mile radius in active markets, according to Chase's guide on comparable market analysis comp selection.
That gives you a practical screen. Don't start with every home in Fresno that has the same bedroom count. Start with the homes a buyer would have considered as real alternatives.
What makes a Fresno comp strong
Use this filter before you accept any property as a comp:
- Neighborhood match. A home in Woodward Park should usually be compared to homes competing in that same buyer lane, not to a property in the Tower District just because both are attractive.
- Style consistency. A mid-century ranch, a newer suburban two-story, and a custom home on acreage don't trade the same way.
- Similar age and condition. Original cabinets versus recent renovation changes the value discussion fast.
- Functional layout. Same square footage doesn't always mean same utility. Buyers care how the space lives.
- Sale timing. A recent closed sale is more useful than stale historical data.
Fresno examples that show the difference
A 1950s home near the Tower District may appeal to buyers who want charm, walkability, and architecture. A newer home in an area like Loma Vista may attract buyers prioritizing newer systems, open layout, and lower immediate maintenance. Even if the sizes are close, the comps shouldn't cross over casually.
The same thing happens with Clovis versus Fresno addresses. Some buyers shop across both areas. Some don't. School preferences, commute habits, and neighborhood expectations can narrow the buyer pool more than owners expect.
A comp isn't just “another house that sold.” It's a house your likely buyer would have seriously considered instead of yours.
A working comp selection method
If you're building your own shortlist, use a sequence like this:
Pin the subject property first
Write down the basics before searching. Size, lot, age, bed and bath count, condition level, and standout features.Pull the closest recent solds
Focus on properties that are geographically close and functionally similar. Sold data matters most because it reflects completed decisions.Screen out false matches
Remove homes with a different style, a very different lot experience, or a condition gap that would distort the number.Check active and pending listings
These don't replace sold comps, but they do show current competition. They matter when you're deciding whether to come in aggressively or more conservatively.
What doesn't work
A few habits almost always produce bad pricing:
- Using only the highest sales because they're encouraging.
- Ignoring condition differences because they're inconvenient.
- Mixing neighborhoods too casually across Fresno, Clovis, or nearby communities.
- Relying on list prices alone instead of closed sales.
That's how owners end up chasing the market instead of meeting it.
Adjusting Values and Interpreting the Results
No comp is perfect. That's why selection is only half the job.
Once you have a reasonable set of comparables, the next step is adjustment. At this stage, you stop treating homes as identical and start accounting for differences that influence price. In a strong CMA, each comp is adjusted against the subject property feature by feature.
What gets adjusted
Robust CMAs use a feature-by-feature adjustment model that compares properties on items such as square footage, lot size, bedroom and bath count, age, and condition, then assigns monetary adjustments to produce a more defensible adjusted price per square foot, as described in Innago's overview of feature-by-feature comparable market analysis adjustments.
That sounds technical, but the logic is simple. If a comp has something your property doesn't, you adjust that comp downward. If your property has something the comp lacks, you adjust that comp upward.
A simple way to think about adjustments
Suppose your Fresno subject property has an updated kitchen, but one of your comps sold with original finishes. That comp may need an upward adjustment to better reflect how it would have sold if it matched your property's condition.
Now reverse it. If the comp has a pool and your subject property doesn't, that comp may need a downward adjustment before you use it as a value indicator.
The point isn't to force every comp into agreement. The point is to normalize the set so the final range is based on comparable utility, not superficial similarity.
Buyers don't pay the same price for the same square footage when one home feels move-in ready and the other feels like a project.
The adjustment categories that matter most
In day-to-day practice, these tend to shape the analysis most:
Condition and upgrades
Fresh remodels, worn interiors, dated systems, and visible maintenance issues all change buyer response.Living area and layout
Extra space matters, but usable space matters more. An awkward addition doesn't carry value the same way a well-integrated floor plan does.Lot and exterior appeal
Corner lots, privacy, yard usability, and outdoor improvements can move buyer interest.Amenities
Pools, garages, covered patios, or other features can matter a lot in some Fresno submarkets and much less in others.
How to read the adjusted results
After adjustments, each comp should give you a more meaningful signal than its raw sale price did. What you want to see is a rational cluster, not one magic number.
If the adjusted range is tight, your pricing recommendation can be tighter. If the adjusted range is wide, one of two things is usually true. Either the comp set isn't clean enough, or the property itself is harder to price because it's more unique.
That's one reason professionals rely on actual analysis tools rather than guesswork. If you want a broader look at the systems agents use when comparing properties and evaluating price trends, Edinhart's review of real estate market analysis tools gives helpful context.
What works and what doesn't
What works
- Comparing each comp line by line
- Being honest about dated condition
- Giving more weight to the closest functional matches
- Letting the adjusted range guide the list price
What doesn't
- Pricing off emotion
- Assuming every upgrade returns full value
- Forcing a target number because an owner “needs” it
- Ignoring current competition
A CMA becomes useful when the adjustments lead to a price range you can defend in a real conversation with buyers, tenants, appraisers, and agents.
Your Simple CMA Checklist
If you're reviewing your own numbers before calling an agent, keep the process simple. The goal isn't to turn yourself into an appraiser. It's to ask better questions and spot weak pricing logic before it costs you time.
Comparable Market Analysis Checklist
| Step | Action Item | Notes |
|---|---|---|
| 1 | Define the subject property clearly | Note size, bed and bath count, age, lot, condition, and standout features |
| 2 | Pull a small set of likely comps | Focus on recent nearby sold properties that would compete for the same buyer or tenant |
| 3 | Remove poor matches | Exclude homes from very different neighborhoods, styles, or condition levels |
| 4 | Review active and pending competition | Use these to understand current pressure, not as substitutes for sold data |
| 5 | Mark feature differences | Compare upgrades, layout, lot utility, parking, pool, and overall presentation |
| 6 | Apply practical adjustments | Normalize the comp set so you aren't comparing mismatched homes at face value |
| 7 | Look for an adjusted range | A range is more useful than chasing one perfect number |
| 8 | Stress-test the result | Ask whether the price fits current competition and likely buyer response |
| 9 | Prepare questions for a broker or manager | Bring any concerns about rent strategy, list timing, and property improvements |
How to use this checklist well
Treat it as a filter, not a formula. If one comp keeps forcing too many adjustments, drop it. If your chosen range only works when you ignore obvious negatives, it probably isn't the right range.
For investors who want to compare broader workflows and software categories before choosing how they analyze deals, this overview of compare real estate deal-making tools is a helpful companion.
The best checklist result is clarity. You should know which properties truly compete with yours and which ones were only flattering distractions.
That alone puts you ahead of many sellers and landlords.
Let an Expert Handle Your Market Analysis
A CMA looks straightforward until the local details pile up. In Fresno, those details matter. Condition, neighborhood fit, school draw, street appeal, current competition, and buyer expectations all shape the final number.
That's why many owners decide not to do the last mile alone.
Where professional help earns its keep
A broker or property manager doesn't just gather comps. They judge which ones deserve weight, which adjustments make sense, and how the current market is likely to respond to the final price.
That matters whether you're selling a home or setting rent on an investment property. Overpricing can stall activity. Underpricing can leave money on the table. Both mistakes are hard to fully recover from once the market has formed an opinion.
For owners who want support with leasing, Edinhart Realty & Property Management offers two practical models. A Placement-Only Service fits owners who want help with marketing, applicant screening, and lease drafting but plan to handle the property themselves. Full-Service Monthly Management covers ongoing operations such as rent collection, repair coordination, tenant communication, move-in and move-out coordination, lease renewals, and detailed accounting statements.
Why this matters for sales and rentals
On the sales side, pricing drives the entire launch strategy. Photography, staging, and showing activity work better when the number is right. On the rental side, market analysis affects not just asking rent but also the quality and speed of applicant interest.
A precise CMA also helps owners make smarter renovation calls. Some upgrades improve marketability immediately. Others look expensive but don't move pricing much in that neighborhood.
If you're weighing whether to handle pricing on your own or bring in representation, this breakdown of the benefits of hiring a realtor adds useful perspective.
A strong market analysis isn't paperwork. It's the foundation for a better decision.
If you want a no-obligation review of your property's likely sale or rental position in the Fresno area, contact Edinhart Realty and Property Management. A professional CMA can help you price with more confidence, whether you're preparing to sell, lease, renovate, or decide what to do next.


