

So, are mobile homes a good investment?
The short answer is a solid "yes," but with a major string attached: it all hinges on whether you own the land the home sits on.
It helps to think of mobile home investing less like a traditional house—where you wait for appreciation to build wealth—and more like a cash-flow machine.
The Real Story on Mobile Home Investing
For years, mobile homes have been the misunderstood corner of the real estate world. Many investors write them off immediately, thinking of them as a depreciating asset like a car, not a piece of property. And while the physical structure can lose value, that's not where the real money is made.
The modern housing market has completely flipped this old way of thinking. With the ongoing affordability crisis, traditional homes are simply out of reach for a huge chunk of the population. This has created a massive, growing demand for lower-cost alternatives, and manufactured housing is perfectly positioned to meet that need.
This affordability crunch creates a reliable and consistent tenant pool for investors. When you compare it to traditional renting, you can see why this niche is so powerful; this infographic explains in more detail why buying a home may make more sense than renting in today's economy.
Weighing the Pros and Cons
Before you jump in, it’s crucial to get a balanced, high-level view. Investing in mobile homes isn't a passive "set it and forget it" venture. It demands a specific strategy that prioritizes generating monthly income over waiting for the property's value to skyrocket.
For most people who succeed in this space, the goal is simple: create a steady stream of rental income that delivers a high return on a relatively small initial investment.
The core strategy is this: Buy an asset with a low entry cost that serves a high-demand need for affordable housing. The profit is found in the monthly cash flow, not necessarily in the long-term sale price of the structure.
This mindset shifts the investment from a simple property flip into a durable, income-generating business. Before we get into the nitty-gritty of ROI and risk, let's lay out a clear snapshot of what you’re getting into.
A Quick Look at Mobile Home Investing
Here's a straightforward summary of the main advantages and disadvantages to give you a balanced perspective right from the start.
| Investment Aspect | Potential Advantage (The 'Pro') | Potential Disadvantage (The 'Con') |
|---|---|---|
| Cost of Entry | Significantly lower initial capital required compared to traditional single-family homes. | Financing can be more challenging, with fewer lenders and potentially higher interest rates. |
| Rental Demand | High and consistent demand due to the nationwide need for affordable housing options. | The tenant base may have lower income levels, potentially increasing the risk of rent delinquency. |
| Asset Value | When land is owned, the entire property can appreciate like traditional real estate. | The physical home itself often depreciates in value over time, similar to a vehicle. |
| Operating Costs | Maintenance, insurance, and property taxes are typically much lower than for site-built homes. | If the lot is rented, unpredictable lot rent increases can significantly erode profitability. |
As you can see, the opportunity is clear, but so are the potential pitfalls. The key is understanding how to leverage the pros while actively managing the cons.
Understanding the True Cost of Entry
To really figure out if mobile homes are a good investment, you have to look past that tempting, low sticker price. While the initial cost is what gets most people interested, it’s just one piece of a much larger financial puzzle. Getting a handle on the full scope of expenses is what separates a profitable venture from a costly mistake.
Here’s a helpful way to think about it: a mobile home without land is kind of like a car. It's an asset, sure, but it's one that typically depreciates. But when you buy the mobile home and the dirt it sits on, you transform it from personal property into a genuine real estate asset. That’s where you unlock the potential for appreciation, and this one distinction changes everything that follows.
The Initial Cash Outlay
Naturally, your first big check is for the home itself. This number can swing wildly depending on whether you're buying new or used, a single-wide or a double-wide, and the unit's overall condition. The cost advantage is still massive, though. For instance, in Florida, a new single-wide might run you $50,000 to $80,000. Compare that to the state’s median price for a traditional home, which is hovering around $439,000. If you want a deeper dive, you can explore more manufactured housing insights to see just how significant this affordability gap is.
But buying the unit is just the beginning. You’ll have a few other major one-time costs to get the home livable and legal.
- Land Acquisition: If you’re buying the land, this will be your largest expense right after the home. If you're placing it in a park, you’ll need to budget for the first month's lot rent and any security deposits.
- Transportation Fees: Getting a mobile home from point A to point B isn't cheap. Moving it from a dealership or a previous owner's lot can cost anywhere from $3,000 to over $10,000, based on the home's size and how far it has to travel.
- Setup and Installation: This isn't a simple drop-off. A professional crew has to level the home, anchor it to a foundation, and connect the sections if it’s a multi-wide unit. Plan on this adding another $2,000 to $5,000 to your startup budget.
- Utility Connections: You’ll also have to pay to get the lights on and the water running. Hookup fees for essentials like water, sewer (or septic), electricity, and gas can easily run into the thousands, especially if you’re setting up on undeveloped land.
Ongoing and Recurring Expenses
Once the home is set up, your focus shifts from one-time costs to the recurring expenses that will hit your bank account every month. These are the numbers that directly affect your cash flow, and you have to factor them into your ROI calculations. Overlooking them is probably the most common rookie mistake I see.
The success of your investment isn't just about the initial price; it's about accurately predicting and managing the ongoing costs that determine your net rental income month after month.
Here’s a quick checklist of the recurring costs you absolutely must account for:
- Lot Rent: If you don't own the land, this will be your biggest monthly bill, often landing between $300 and $800. A word of caution: park owners can—and do—raise the rent, which will eat directly into your profit margin.
- Property Taxes: When you own the land, you pay traditional property taxes. If you just own the home, you'll likely pay a smaller personal property tax, which is usually quite a bit lower.
- Insurance: You need a solid homeowner's insurance policy to protect your asset from storms, fires, and other damage. The rates depend on the home's age, location, and how much coverage you get.
- Maintenance and Repairs: Things break. It's a fact of life for any landlord. A good rule of thumb is to set aside 1-2% of the property's value every year for things like plumbing issues, a leaky roof, or HVAC trouble.
- Utilities: Even if your lease makes the tenant responsible for their own usage, you’re on the hook for utilities during vacancies.
By building a comprehensive budget that includes every single one of these items, you stop being someone who just bought a property and become someone making a calculated, strategic investment.
Calculating Your Potential Return on Investment
Alright, let's get down to brass tacks. Turning a list of potential expenses into a real, predictable profit is where a good idea becomes a great investment. If you're going to answer the question "are mobile homes a good investment?" for yourself, you have to master the numbers.
This isn’t about some crazy Wall Street formula. It's about simple, powerful math that lays bare a property's true potential.
Your profit really comes from two main sources: the steady rental income you collect each month, which we call cash flow, and the chance for the property's value to go up over time, known as appreciation. While both are nice, seasoned mobile home investors are obsessed with cash flow. It's the lifeblood of the investment.
Key Metrics You Need To Know
To quickly gauge the health of a potential deal, you'll want to get comfortable with a couple of key metrics. Think of these as the financial dashboard for your property, giving you an at-a-glance look at its performance.
- Capitalization Rate (Cap Rate): This is the raw, unleveraged annual return on the property. You find it by dividing the Net Operating Income (NOI) by the purchase price. A higher cap rate often means a better return, but it can also signal more risk. It’s a great way to compare different properties on an apples-to-apples basis.
- Cash-on-Cash Return: Honestly, this is the number most investors care about most. It tells you how much cash you're getting back each year based on the actual cash you pulled out of your pocket to buy the place (your down payment, closing costs, etc.). It answers the most important question: how hard is my money working for me?
For example, if you put down $30,000 of your own money to buy a mobile home and your annual cash flow (after all expenses) is $6,000, your cash-on-cash return is a fantastic 20%. This is where mobile homes can really shine, often delivering much higher returns for a smaller upfront investment compared to traditional houses.
This visual breakdown really highlights the financial argument for mobile homes.
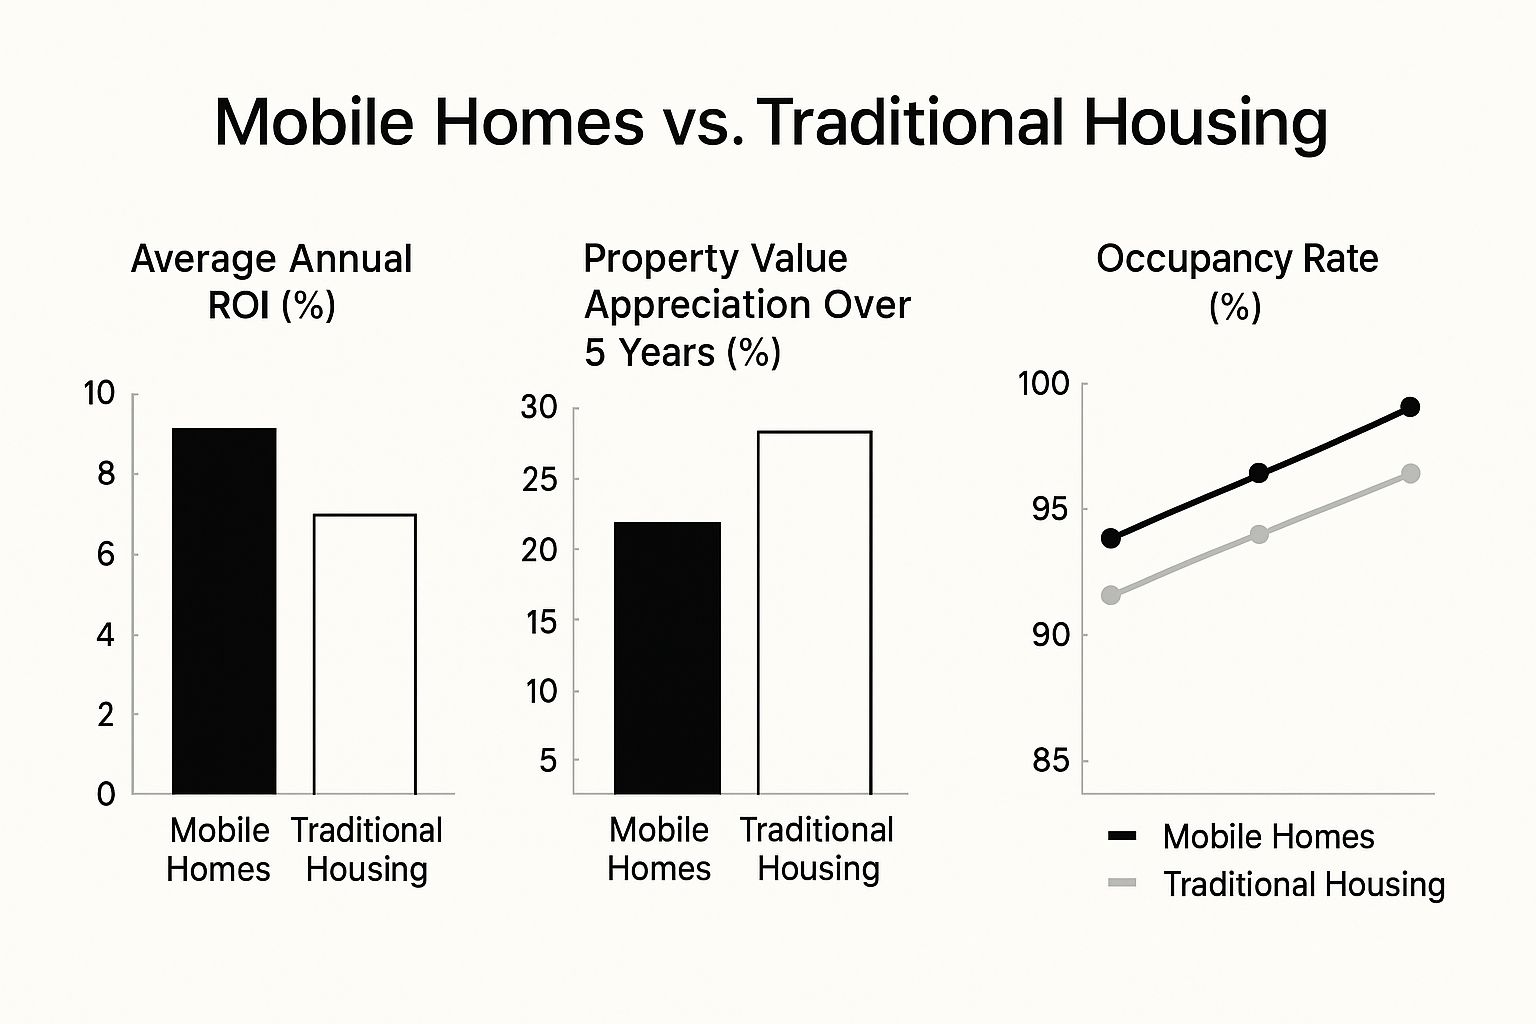
As you can see, even though appreciation might not be as dramatic as with a single-family home, the powerful combination of higher ROI and rock-solid occupancy rates makes a very compelling case.
Putting It All Together: A Sample Calculation
Let's walk through a simple, real-world example to see how these numbers actually work. Once you see the income and expenses laid out, it becomes crystal clear how the profit is made. Plus, understanding the different 8 ways to boost your rental property's ROI can make a huge difference in your final numbers, no matter what kind of property you own.
Here's a breakdown for a hypothetical rental mobile home where you own both the unit and the land it sits on.
Sample ROI Calculation for a Rental Mobile Home
This table shows how a modest property can generate powerful returns.
| Financial Metric | Example Calculation | Amount |
|---|---|---|
| Purchase Price | N/A | $90,000 |
| Gross Annual Rent | $1,200/month x 12 | $14,400 |
| Annual Expenses | Taxes + Insurance + Maintenance + Vacancy | -$5,400 |
| Net Operating Income (NOI) | Gross Rent – Expenses | $9,000 |
| Cap Rate | $9,000 / $90,000 | 10% |
| Your Down Payment (25%) | $90,000 x 0.25 | $22,500 |
| Annual Mortgage Payments | Principal + Interest | -$4,800 |
| Annual Cash Flow | NOI – Mortgage Payments | $4,200 |
| Cash-on-Cash Return | $4,200 / $22,500 | 18.67% |
With a cash-on-cash return of over 18%, you can see why investors are so drawn to this niche. The constant demand for affordable housing helps keep vacancy rates low, which is the secret sauce for consistent income.
The numbers back this up. Major manufactured housing REITs reported sky-high occupancy rates between 87.9% and 97.5% in early 2025, with rental income jumping 5.5% to 8.1% in just one year.
By mastering these simple calculations, you gain the power to analyze deals with confidence. You’ll be able to quickly separate the winners from the losers and build a portfolio of profitable https://edinhart.com/investment-homes/ that provides reliable income for years to come.
How to Secure Financing for Your Investment
Getting a loan for a manufactured home isn't the same as financing a traditional house. The path is different, and as an investor, you need to know the landscape before you dive in. The kind of loan you'll get hinges on one critical question: do you own the dirt underneath the home?
When the home is treated like personal property—think of it more like an RV or a car—you’re headed down one financing path. But when the home and the land are bundled together as a single piece of real estate, a whole different world of conventional lending opens up. Picking the right route is a make-or-break decision for your investment.
Chattel Loans for the Home Only
Let's say you're buying a mobile home to place in a park where you'll pay lot rent. In this scenario, you're not buying the land, so you'll most likely be looking at a chattel loan. This is essentially a loan for a large piece of personal property, not real estate.
Because there's no land for the lender to use as collateral, these loans are seen as riskier. That risk usually shows up in the loan terms.
- Higher Interest Rates: You can expect rates to be noticeably higher than what you’d see on a standard mortgage.
- Shorter Loan Terms: Forget 30-year terms. You're more likely to see repayment periods of 10, 15, or perhaps 20 years at the most.
- Tougher Credit Scrutiny: Lenders will look very closely at your credit score and financial history.
A chattel loan gets you the physical home, but it treats it like a depreciating asset. It’s a practical way to acquire the unit itself, but it lacks the long-term wealth-building power you get when land is part of the deal.
This is a common entry point for investors who want to rent out a single unit in an established community without a huge upfront cost. It gets your foot in the door, but be prepared for less-than-ideal terms.
Conventional Mortgages for Real Property
Everything changes when you buy the mobile home and the land it sits on. Once the home is permanently attached to a foundation on land you own, it gets classified as real property. This is the key that unlocks the door to much better financing.
When your investment is considered real property, you can apply for a conventional mortgage, just like you would for a stick-built house. The advantages here are huge.
- Lower Interest Rates: Your rates will be competitive with the rest of the real estate market.
- Longer Loan Terms: You can now access 15-year or 30-year fixed-rate mortgages, which keeps your monthly payments much lower and more predictable.
- Appreciation on Your Side: The loan is secured by an appreciating asset—the land—which is a massive boost to your investment's long-term value.
Government-Backed and Alternative Options
Beyond those two main avenues, there are a few other smart options to consider. Government programs can make it easier to get started, and a little creativity can help you close a deal when traditional banks won't play ball.
- FHA and VA Loans: These government-insured loans are a fantastic option for manufactured homes that meet certain standards, like being on a permanent foundation on owned land. They often come with low down payment requirements and more forgiving credit standards.
- Seller Financing: Sometimes, the seller is willing to act as the bank. This can be a very flexible arrangement where you negotiate the terms directly, which is a lifesaver if the seller is a motivated investor looking to close quickly.
- Cash Purchase: If you have the capital, paying with cash is the simplest route. It wipes out interest payments and loan fees. For savvy investors, it can also be a strategic move to defer taxes by rolling the proceeds into a 1031 exchange on a subsequent property.
Your financing choice isn't just a hurdle to clear—it's a core part of your investment strategy. The path you take will directly shape your cash flow, your overall return, and how quickly you can grow your portfolio.
Navigating the Risks and Common Pitfalls
While the numbers on mobile home investments can look fantastic on paper, a seasoned investor knows to always flip the coin over and examine the other side. Understanding the real risks isn't about being negative; it's about being prepared.
When you know what can go wrong, you can build a strategy to protect your investment and avoid the common traps that snag so many first-timers. Mobile homes have their own unique set of challenges, and ignoring them is the fastest way to turn a promising deal into an expensive lesson.
The Depreciation Dilemma
Let's start with the biggest one you'll hear about: depreciation. Unlike a traditional stick-built house that appreciates with the land it sits on, the physical structure of a mobile home can lose value over time, much like a vehicle driving off the lot.
This is especially true if you don't own the land underneath it. When a home is on a rented lot, it's classified as personal property, not real estate. Its value is completely separate from the local land market. Without that anchor, the home's age and condition are the main drivers of its worth, which often means a slow and steady decline.
However, owning the land changes the game entirely. Once a manufactured home is permanently attached to a foundation on land you own, the whole package becomes real estate. In this scenario, the rising value of the land can easily outpace the depreciation of the structure itself.
The most critical question to ask is: "Am I buying an asset or a liability?" A mobile home on rented land can become a depreciating liability, while a mobile home on owned land becomes an appreciating asset.
The Unpredictability of Lot Rent
If you buy a home in a mobile home park to rent out, you wear two hats: you're a landlord to your tenant, but you're also a tenant to the park owner. This introduces a major risk that is completely out of your hands: unpredictable lot rent increases.
Imagine your rental is cash-flowing a nice $400 a month. Then, you get a notice—the park is hiking lot rent by $75. Just like that, your annual profit is chopped by $900. These increases hit your bottom line directly and can sour a good investment in a hurry.
Before you ever buy a home in a park, you need to do your homework:
- Dig into the Park's History: Talk to other residents. Ask the park manager about past rent increases. Are they small and annual, or are they sudden and steep?
- Read the Lease Agreement: Scrutinize the terms for rent adjustments. Some states put caps on how much and how often lot rent can be raised, so know the local laws.
- Budget for the Future: Don't just run your numbers with the current lot rent. Smart investors build in a buffer for future increases to see if the deal still makes sense. A good rental property ROI calculator is perfect for stress-testing your investment against these kinds of rising costs.
Unique Maintenance and Zoning Hurdles
Manufactured homes have their own maintenance quirks. You'll run into issues like leveling problems, managing moisture under the home, and dealing with plumbing or electrical systems that might require a specialist. These repairs aren't always more expensive, but they are different, and not every handyman knows how to handle them.
Beyond that, local zoning laws can be a massive headache. Many towns have strict rules about where manufactured homes can be placed, what type of foundation they need, and even how old they can be. You could find an incredible deal on a home, only to learn you're not legally allowed to move it where you want.
Always, always check with the local planning and zoning department before you even think about making an offer. Getting ahead of these risks is what separates a successful investment from a cautionary tale.
Final Verdict: Is This Investment Right for You?
So, after digging into the costs, the potential returns, and the real-world risks, we’re back to the big question: are mobile homes a good investment for you? The answer isn’t just in the spreadsheets; it’s about your personal goals, your tolerance for risk, and how you want to build wealth.
Let's be clear: this isn't a "set it and forget it" kind of deal. Investing in mobile homes can be an incredible way to generate cash flow, especially with an entry cost that's a fraction of traditional real estate. That alone makes it a compelling option for new investors or anyone looking to add a high-yield asset to their portfolio. But making it work requires active management and smart decisions.
The Land is the Lynchpin
If there's one thing to take away from this entire guide, it's the critical difference between owning the home and owning the land it sits on. When you own the land, you're investing in a genuine real estate asset—something that has the potential to appreciate over time. If you only own the home and rent the lot, you're buying a cash-flow stream from an asset that, like a car, will depreciate.
The core decision is this: Are you seeking long-term wealth through property appreciation or immediate, high-yield monthly income? Your answer will determine whether you prioritize deals that include land.
Both approaches can be very profitable, but they are fundamentally different strategies. Owning the land gives you stability and long-term growth potential. Just owning the home and renting the lot can offer faster and higher cash-on-cash returns, but you sacrifice a great deal of control.
Your Personal Investor Checklist
Before you jump in, run through these questions. Be honest with yourself—your answers will tell you if this niche fits your investor profile.
- What's my main goal here? Am I looking for extra monthly income to cover my bills, or am I trying to build a portfolio that grows in value for the next 20 years?
- How much risk can I stomach? Am I okay with the uncertainty of lot rent increases and dealing with a more transient tenant pool? Or do I need the security that comes with a traditional real estate asset?
- How hands-on do I want to be? Am I ready to handle tenant issues, find specialized repair people, and deal with park management? Or am I really looking for something more passive?
- What's my starting capital? Is my budget better suited for a lower-cost home-only purchase, or can I realistically afford the bigger down payment needed to buy both the home and the land?
At the end of the day, a well-chosen manufactured home can be a brilliant and profitable investment. It directly addresses the affordable housing crisis, which means demand is built-in and consistent. If you're a proactive, hands-on investor who's laser-focused on generating cash flow, this just might be the opportunity you've been looking for.
Common Questions from New Investors
Getting into mobile home investing brings up a lot of questions. I hear the same ones all the time from people just starting out, and getting these fundamentals right is crucial before you put any money on the table.
Let's walk through the big ones.
Do Mobile Homes Actually Go Up in Value?
This is the million-dollar question, isn't it? And the answer is a firm it depends.
A mobile home on a rented lot in a park? That's going to depreciate, much like a car does over time. But when you own the land underneath it, the game changes completely. A home permanently fixed to a foundation on land you own is treated as real estate, and that entire package—the home and the land—can absolutely appreciate in value.
Owning the land is the single most important factor that transforms a mobile home from a depreciating personal asset into an appreciating real estate investment.
What's the Difference Between "Mobile Home" and "Manufactured Home"?
You'll hear people use these terms interchangeably, but there's a technical distinction that matters.
Officially, a "mobile home" is a factory-built house constructed before June 15, 1976. On that date, the federal government stepped in with the HUD code, which established much stricter standards for safety and construction. Any home built after that date is technically a "manufactured home."
So, while day-to-day conversation lumps them together, knowing the difference is key when you're looking at older properties.
Should I Start with One Home or Buy a Whole Park?
Your budget and how much hands-on work you want to do will answer this for you.
- Buying a single unit is a fantastic, low-cost way to dip your toes into real estate. It's perfect for learning the ropes and generating some solid cash flow without a massive upfront investment.
- Buying an entire park is a different beast entirely. This is a serious commercial real estate play that demands a ton of capital and professional management skills. The upside? The potential for scaling your income is enormous.
Ready to maximize your rental income or find the perfect investment property? Edinhart Realty and Property Management offers expert guidance and professional services to help you achieve your real estate goals. Learn more about how we can help.


