

If you're a real estate investor, you've probably heard about the 1031 exchange. It's a powerful tool that allows you to defer capital gains taxes when you sell an investment property, as long as you reinvest the proceeds into a new, similar one.
The core idea behind the 1031 real estate exchange rules is simple: you must swap one investment property for another of "like-kind" within a very strict timeline. When done right, this move keeps your capital working for you instead of going to the IRS, seriously accelerating your portfolio's growth.
What Is a 1031 Exchange for Real Estate Investors?

Think of a 1031 exchange as a strategic way to upgrade your investment portfolio without the immediate tax hit. Instead of selling a property and handing over a huge chunk of your profit to Uncle Sam, you get to roll those gains directly into your next purchase.
It’s a lot like trading in your old car at a dealership. You don't get a check for your old car's value—that value is applied directly to the price of the new one. In a 1031 exchange, the process is similar: the proceeds from your sale are held by a neutral third party and then funneled straight into the new property, pushing that tax bill down the road.
To give you a quick overview, here are the core components you'll be dealing with.
1031 Exchange At a Glance
| Component | Requirement | Purpose |
|---|---|---|
| Like-Kind Property | Must be real property held for investment or business use. | Ensures the investor remains in a similar type of investment. |
| Qualified Intermediary | A neutral third party must hold the sale proceeds. | Prevents the investor from taking "constructive receipt" of the funds. |
| 45-Day Identification | Identify potential replacement properties in writing within 45 days. | Forces a quick and definitive decision on the next investment. |
| 180-Day Closing | Acquire the replacement property within 180 days of the original sale. | Completes the exchange cycle within the IRS-mandated timeframe. |
| Value & Debt Rules | New property's value and debt must be equal to or greater than the old. | Avoids triggering a taxable event by "trading down." |
This table just scratches the surface, but it lays out the non-negotiable pillars of a successful exchange.
The Foundation of Tax-Deferred Investing
The 1031 exchange isn't some new tax loophole; it's a cornerstone of real estate strategy that's been around for decades. This provision comes from Section 1031 of the U.S. Internal Revenue Code, which dates all the way back to the Revenue Act of 1921. It was created to encourage investors to keep their money in the market and continue improving properties.
This powerful tax-deferral strategy is built on a few core principles every investor needs to get right:
- Continuous Investment: The whole point is to help investors who plan to stay in the game, allowing them to move from one property to the next without losing a slice of their capital to taxes each time.
- Property Must Be for Business or Investment: This is crucial. Your personal home or a property you bought just to flip quickly won't qualify. The IRS needs to see a clear intent to hold the property for productive use in a business or for long-term investment.
- Strict Adherence to Rules: The IRS doesn't mess around here. There's no leniency. If you miss a deadline or mishandle the funds, the exchange is immediately disqualified, and you’ll get hit with the full tax bill from the sale.
At its heart, a 1031 exchange recognizes that an investor's capital remains tied up in a similar investment. Since they haven't "cashed out" in a real sense, the tax event is postponed until they finally do.
Why Mastering the Rules Is Critical
For any serious investor, understanding the fine print of the 1031 real estate exchange rules is non-negotiable. A successful exchange can preserve hundreds of thousands of dollars in equity that you can then use to buy bigger and better assets. This creates a compounding effect that can dramatically accelerate the growth of your real estate portfolio over time.
Of course, navigating federal tax law is just one piece of the puzzle. For investors in dynamic markets, staying on top of local regulations is just as important. You can get a head start by reading our complete guide on landlord-tenant law in California. With that foundation, we can now dive into the detailed mechanics of the exchange itself.
Navigating the Critical 45 and 180 Day Timelines
When you're doing a 1031 exchange, the calendar becomes your toughest boss. The entire deal lives and dies by two iron-clad, overlapping deadlines that have absolutely no wiggle room: the 45-day identification period and the 180-day closing period.
Getting a handle on how these two timelines work together is everything. A lot of investors mistakenly think they run one after the other, but they don't. Both clocks start ticking at the exact same moment: the day you close the sale on your original property.
If you miss either deadline by a single day—just one—the whole exchange is off. The fallout is serious. Your deal turns back into a regular taxable sale, meaning you'll be on the hook for capital gains tax on every dollar of profit.
The 45 Day Identification Period Explained
The second you finalize the sale of your property, you have precisely 45 calendar days to officially identify potential replacement properties. And this isn't just a list you jot down for yourself; it's a formal, written notice that has to be delivered to your Qualified Intermediary (QI).
This 45-day window is usually the most pressure-packed part of the whole exchange. It demands fast, confident decisions in what’s often a very competitive market. You simply can't afford to hesitate. The smartest investors I've seen start looking for their next property long before their current one even hits the market.
Key Takeaway: That 45-day deadline is set in stone. Weekends, holidays, or any other delay won't get you an extension. The IRS is a stickler for the rules here, so being prepared and acting early is your best defense.
The IRS does give you a few options for identifying properties, which adds some welcome flexibility. You just have to follow one of these three rules.
The Three-Property Rule: This is the one most people use because it’s simple and direct. You can name up to three potential replacement properties, no matter what they cost. The plan is to then buy one (or more) of them to finish the exchange.
The 200% Rule: Need more options? This rule lets you identify more than three properties. You can list as many as you like, just as long as their total market value doesn't go over 200% of what you sold your property for. So, if you sold a building for $500,000, you could identify five properties with a combined value up to $1 million.
The 95% Rule: This one is the least common and typically comes into play for really complex, multi-property deals. You can identify an unlimited number of properties with no value cap, but there’s a big catch: you have to end up buying at least 95% of the total value of everything you identified.
This simple infographic gives you a great visual of the core steps to qualify for a 1031 exchange.
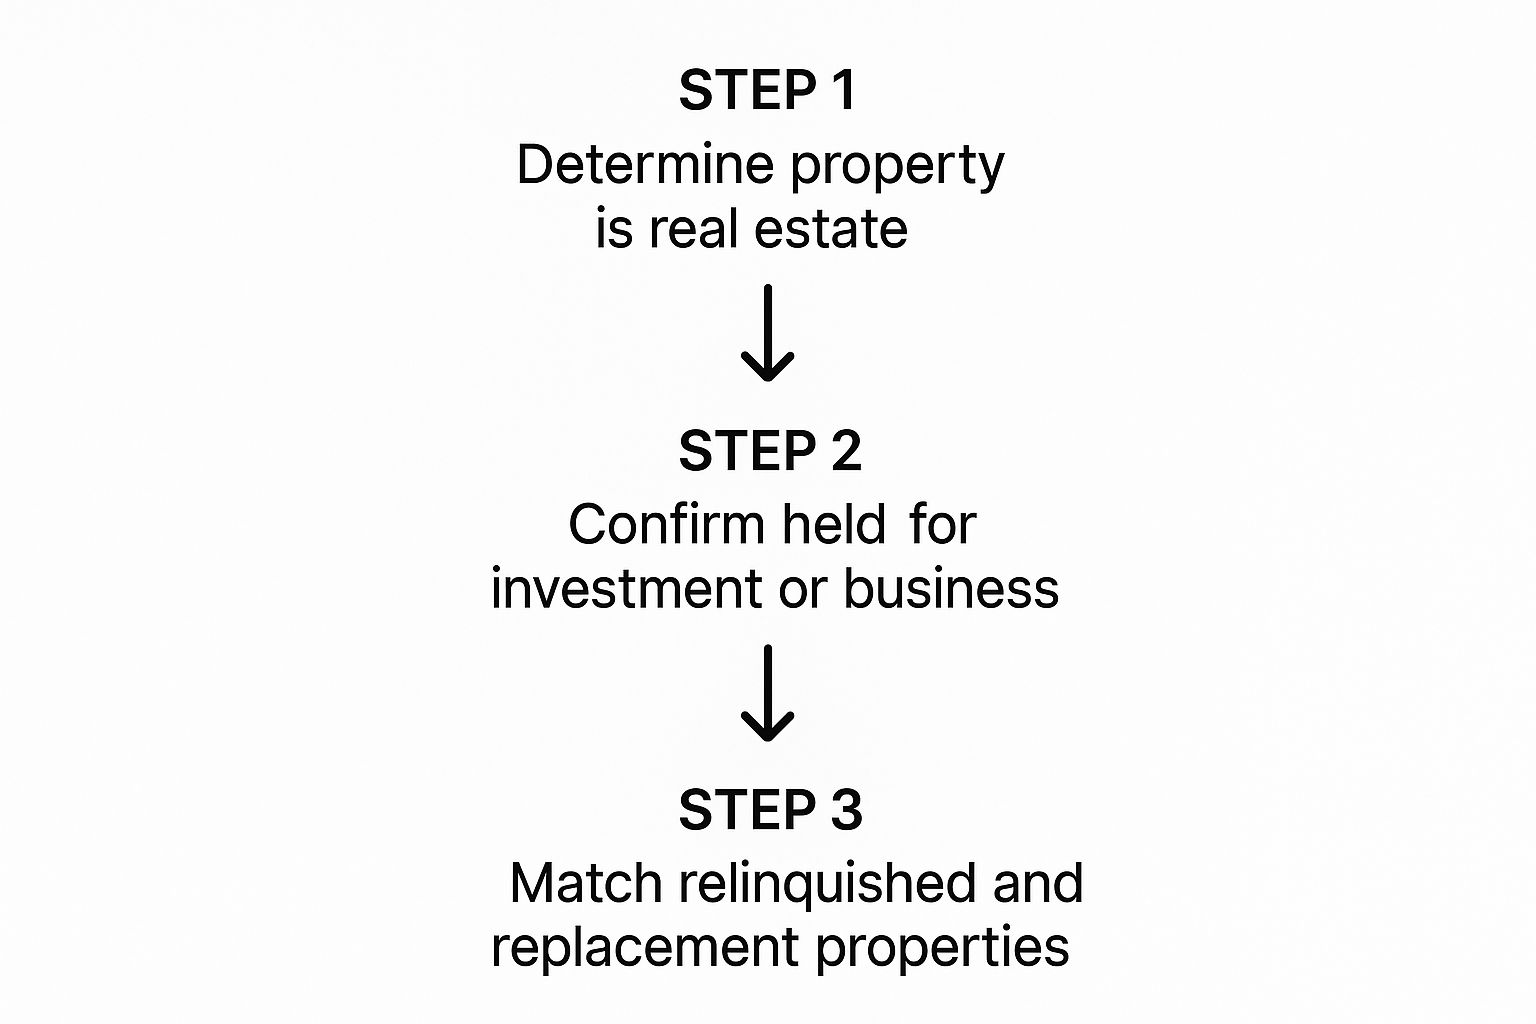
As you can see, it all starts with making sure your property is the right type and held for the right purpose before you even think about finding its replacement.
The 180 Day Closing Period Requirement
The second non-negotiable deadline is the 180-day closing period. You have to buy and take title to your new replacement property (or properties) within 180 calendar days of selling your original one.
It’s crucial to remember that the 45-day identification period is part of this 180 days. Once your 45 days are up, you have the next 135 days left to negotiate the deal, line up your financing, do all your inspections, and get to the closing table.
Let’s look at a quick example of how it plays out.
Example Timeline Calculation:
- Day 0: You sell your property on June 1st. This is the starting gun for both timers.
- Day 45: Your deadline to identify new properties is July 16th. Your written list has to be in your QI's hands by midnight.
- Day 180: Your final closing deadline is November 28th. You must officially own the new property by this day to complete the exchange successfully.
The timelines are tight, and there's no room for error. Solid planning and a proactive approach are what separate a successful tax-deferred exchange from a painful tax bill. Make sure you're on top of all the 1031 real estate exchange rules.
Understanding the Like-Kind Property Rule
When you first hear the term "like-kind," it's easy to get the wrong idea. It's probably the most misunderstood part of the entire 1031 real estate exchange rulebook. Many investors think it means you have to do a direct swap—a single-family rental for another single-family rental, or an office building for a nearly identical one down the street.
Thankfully, the rule is far more flexible than it sounds.
"Like-kind" isn't about the property's physical appearance or quality. It’s all about its nature or character and, most importantly, how you plan to use it. Under the current IRS guidelines, any real property you hold for productive use in a business or for investment is considered "like-kind" to any other real property held for the same general purpose.
This simple distinction opens up a whole world of strategic possibilities for investors looking to pivot or diversify their real estate holdings.
The True Meaning of Like-Kind Real Estate
A good way to think about it is like trading vehicles. You could absolutely trade a sleek sports car for a rugged pickup truck. They look nothing alike and serve very different functions, but at their core, they are both motor vehicles. The same exact logic applies to real estate in a 1031 exchange.
As long as the property you’re selling (the relinquished property) and the one you’re buying (the replacement property) are both held for business or investment purposes, they almost always qualify as like-kind.
Here are just a few examples of qualifying exchanges that might surprise you:
- Raw Land for an Apartment Complex: You can sell a vacant lot and roll the proceeds into an income-generating multifamily property.
- A Single-Family Rental for an Industrial Warehouse: Trading a residential rental for a commercial warehouse is a perfectly legitimate exchange.
- An Office Building for a Portfolio of Rental Condos: You can consolidate a single large asset into several smaller, more manageable ones.
- Retail Space for Agricultural Farmland: The specific use can change dramatically, as long as both are held for investment.
The one major geographical rule is that both properties have to be within the United States. You can’t, for instance, exchange a property in California for one in Mexico. This incredible flexibility is a big reason why 1031 exchanges are such a powerful tool for building wealth.
What Is Not Considered Like-Kind Property
While the definition is generous, the IRS draws a very firm line in the sand for certain types of property. These are strictly excluded from 1031 exchanges, and knowing what they are is critical to avoiding a failed exchange and a massive, unexpected tax bill.
The most common mistake people make is trying to exchange property that isn't truly held for investment. Your intent is what really counts here.
Here’s a quick rundown of what doesn't qualify:
- Your Primary Residence: The home you live in is personal property, not an investment asset.
- Fix-and-Flip Properties: If you bought a property with the sole intention of a quick resale, the IRS sees it as inventory, not a long-term investment.
- Vacation Homes (with heavy personal use): Using a second home too often for your own getaways can disqualify it as a genuine investment property in the eyes of the IRS.
- Partnership Interests: You can't exchange your share in a real estate partnership for a direct ownership of a property.
- Stocks, Bonds, or Notes: These are considered personal property and are not "like-kind" with real estate.
The crucial test is your intent. You must be able to demonstrate that you acquired and held the property with the primary goal of generating income or for long-term appreciation, not for personal use or a quick resale.
And this isn't just a strategy for big corporations. Data shows it's widely used across the entire market. The median price of relinquished properties was around $575,000, and 75% of all properties involved in exchanges were valued below $1.5 million. This shows just how accessible a 1031 exchange is for a wide range of investors. You can explore more economic impacts of Section 1031 to see its full scope.
Structuring Your Finances for Full Tax Deferral
Pulling off a 100% tax-deferred 1031 exchange doesn't happen by accident—it’s all about precise financial planning. The main idea is simple: to put off paying all capital gains tax, you have to buy a replacement property that's worth the same or more than the one you just sold. You also have to reinvest every penny of the cash proceeds.
Think of it like trading up in a board game. To skip the penalty, your new property piece must have a price tag at least as high as your old one. You also have to use all the game money from the sale to buy it. If you slip any cash in your pocket or buy a cheaper property, you've just created a taxable event.
The Two Core Financial Rules
To make sure your exchange is completely tax-free, you need to hit two critical financial targets. Missing either of these doesn't necessarily blow up the whole deal, but it will definitely create a tax bill you have to pay.
- Equal or Greater Value: The total purchase price of your new property (or properties) has to be equal to or greater than the net selling price of your old one.
- Reinvest All Equity: Every single dollar of equity from the property you sold must be rolled into the new property. Any cash you take out is considered taxable.
These two rules go hand-in-hand to ensure your investment position either holds steady or gets stronger. Any step down in value or equity is seen by the IRS as a gain you’ve “cashed out,” and they'll want their cut.
The goal is simple: trade across or trade up. If the net sales price of your old property was $700,000, your new property must be purchased for $700,000 or more to fully defer the tax.
Avoiding Taxable Boot
In the lingo of 1031 exchanges, any non-like-kind property you get out of the deal is called "boot." Boot is what turns a tax-deferred exchange into a partially taxable one. It isn't a penalty; it’s just the part of your gain that you didn’t reinvest according to the rules.
There are two main kinds of boot you need to watch out for.
Cash Boot: This is the most straightforward type. It’s any cash from the sale that you don’t put toward the new property. If your Qualified Intermediary cuts you a check for $50,000 at closing, that $50,000 is cash boot and is now taxable income.
Mortgage Boot (Debt Relief): This one’s a bit sneakier. It happens if the mortgage on your new property is less than the loan you paid off on the old one, and you don’t add your own cash to cover the difference. Say you had a $300,000 mortgage on the old place but only get a $250,000 loan for the new one. You now have $50,000 in mortgage boot unless you bring an extra $50,000 in cash to the purchase.
Figuring out how to juggle these financial pieces is just as important as managing the property itself. Staying on top of your numbers is crucial, especially when tax time comes. We've got more helpful advice on our blog detailing how to prepare for tax season when you own a rental property.
A Practical Example of Calculating Boot
Let’s walk through a real-world scenario to see how this all shakes out.
Imagine you sell an investment property with these numbers:
- Sales Price: $800,000
- Closing Costs: $40,000
- Mortgage Payoff: $300,000
- Net Equity (Cash Proceeds): $460,000
To defer all your taxes, the property you buy needs to have a purchase price of at least $800,000. But let's say you find a new property and buy it for $750,000.
Because your new property is worth $50,000 less, you’ve just received a $50,000 taxable boot. It doesn’t matter that you reinvested all $460,000 of your equity—you still "traded down" in total value, which makes that difference taxable. For a wider look at reducing tax hits across different asset classes, you can find some great insights in this article on general strategies for minimizing tax on investments.
By carefully planning your target purchase price and your financing, you can make sure every dollar of your gain stays deferred, maximizing your investment power for years to come.
Why a Qualified Intermediary Is Non-Negotiable
Let's get one of the most critical 1031 real estate exchange rules straight right from the start: you, the investor, are absolutely forbidden from touching the money from your sale. If those funds hit your bank account, even for a split second, the exchange is dead on arrival.
This is exactly why a Qualified Intermediary (QI) isn't just a good idea—they're the essential gatekeeper for your entire transaction.
Think of the QI as a highly specialized, neutral escrow agent built specifically for 1031 exchanges. Their entire purpose is to hold the proceeds from your first property sale and then, on your behalf, use that money to buy your replacement property. This isn't just a best practice; it's the IRS-mandated structure to avoid what’s known as "constructive receipt."
Constructive receipt is the legal tripwire that says if you have control over the funds, it's the same as having them in your pocket. Using a QI is the official safe harbor the IRS gives you to prove you never had access to the cash, keeping your tax-deferred status locked down and secure.
The Core Responsibilities of Your QI
A good Qualified Intermediary does a lot more than just babysit your money. They act as the central coordinator, making sure every move you make follows IRS rules from beginning to end.
Here’s what they handle:
- Preparing Exchange Documents: They draft the all-important legal paperwork, like the Exchange Agreement, that officially frames your deal as a 1031 exchange.
- Holding and Securing Funds: The QI gets the sale proceeds directly from the closing of your old property and keeps them in a separate, secure account until you're ready to pull the trigger on the new one.
- Facilitating the Replacement Purchase: They coordinate with the closing agent on your new property, wiring the funds directly to seal the deal.
This role is a cornerstone of the real estate market. Just look at the numbers: from 2010 to mid-2020, like-kind exchanges made up 12% to 20% of all commercial real estate deals in the country. In that period, a single major QI handled around 123,000 exchanges, showing just how central they are. You can discover more about the economic impacts of Section 1031 to see how big this really is.
Choosing the Right Qualified Intermediary
Not all QIs are created equal, and a bad choice can jeopardize your entire investment. The industry is surprisingly unregulated, so doing your homework isn't optional. Your agent or attorney can point you in the right direction, but you have the final say.
Crucial Insight: The person or company acting as your QI cannot be a "disqualified person." This means you can't use your attorney, your real estate agent, your accountant, or anyone who has worked for you professionally in the last two years. They must be a genuinely independent third party.
Here’s a quick checklist to vet a potential QI and protect your investment:
- How are exchange funds secured? You need to hear "segregated accounts" for each client. Ask what kind of insurance they carry, like Fidelity Bonds and Errors & Omissions (E&O) coverage.
- How long have you been in business? You want a firm with a long, proven track record. In this business, experience is the best sign of reliability.
- What are your fees? Good QIs have transparent, flat-fee pricing. If they charge based on a percentage of the exchange or have fuzzy costs, walk away.
- Do you have in-house legal counsel? Having attorneys on staff is a huge plus. It shows they're serious about compliance and can navigate tricky situations.
Picking a skilled and secure Qualified Intermediary is one of the single most important decisions you'll make in the 1031 process. It’s what lets you sleep at night.
Avoiding the Most Common 1031 Exchange Mistakes
Pulling off a successful 1031 exchange really comes down to sidestepping a few common, but very costly, errors. Knowing the 1031 real estate exchange rules is one thing, but actually applying them under the pressure of a real estate deal is another beast entirely. I've seen too many investors stumble over details that seem small at first but end up torpedoing their entire tax deferral.
Think of this guide as your playbook for avoiding those unforced errors. By seeing where others have gone wrong, you can build a solid strategy to protect your investment and make sure your exchange is smooth and compliant from start to finish.
Let's dive into the most frequent mistakes and, more importantly, how to steer clear of them.
Missing the Strict Timelines
This is, without a doubt, the most common and unforgiving mistake. That 45-day identification period flies by faster than you can imagine. Many investors make the critical error of waiting until their old property closes before they even start looking for a new one. That's a recipe for disaster.
Prevention Strategy:
- Start Early: Get a head start. Begin your search for potential replacement properties weeks, or even months, before your sale is a done deal.
- Have Backups: Never bet on just one horse. Always identify more than one property, using the Three-Property or 200% Rule. This protects you if your first choice falls through at the last minute.
- Calendar Everything: The moment your property closes, get out your calendar. Mark the 45-day and 180-day deadlines in bright red and work backward from those dates to plan your every move.
Mishandling Funds and Constructive Receipt
Here’s a cardinal rule you can't break: you cannot touch the sale proceeds. If the money from your relinquished property hits your personal or business bank account, even for a second, the exchange is toast. It's called constructive receipt, and once it happens, there’s no going back.
I once saw a case where an investor had their attorney hold the exchange funds in the firm’s trust account. The IRS ruled that since the attorney was their agent, it was considered constructive receipt. The exchange failed. Using a proper Qualified Intermediary is the only safe harbor—period.
You also have to be careful about how you handle closing costs. Using exchange funds to pay for things that aren't standard closing expenses can be seen as taking cash "boot." This can mess with your financial picture, so it’s crucial to know your obligations. To get a better handle on managing property finances, check out our guide on common rental property tax deductions for some valuable tips.
Violating the Same Taxpayer Rule
This one sounds simple but trips people up all the time. The entity or individual who sells the relinquished property must be the exact same one who buys the replacement property. You can't sell a property held in your name and then buy the new one under a new LLC you just created.
Prevention Strategy:
- Plan Ahead: Before you even list the property, make sure you know how the title is held and that it will be identical on the new property.
- Consult Experts: Need to change your ownership structure? Don't try to wing it. Talk to your legal and tax advisors about complex maneuvers like a "drop and swap" long before the exchange process ever begins.
Your Top 1031 Exchange Questions, Answered
When you get into the weeds of a 1031 exchange, a lot of practical questions pop up. Getting straight answers is the key to moving forward with confidence and, more importantly, avoiding a costly mistake. Let’s tackle some of the most common questions investors run into.
Every deal has its own quirks, but if you get the core principles down, you'll be in a much better position to make smart, compliant moves. Here’s some clarity on the trickiest parts of the process.
Can I Use a 1031 Exchange for a Vacation Home?
This is a big one, and the answer is a solid maybe. The IRS is very clear: a 1031 exchange is strictly for investment or business property. Personal use is a no-go. So, to make your vacation home qualify, you have to prove its main purpose was generating income.
That means you need a paper trail showing you rented it out at fair market value and kept your personal stays to a minimum—usually no more than 14 days a year. Your primary home will never qualify for a 1031 exchange, but don't forget it has its own tax break under Section 121.
It all comes down to your intent in the eyes of the IRS. If you have rental records and limited personal stays that prove the property was an investment first and a vacation spot second, you've got a good shot at qualifying it for an exchange.
What Happens If I Can't Find a Replacement Property?
You absolutely need a backup plan for this scenario. If you don't officially identify a potential replacement property within that strict 45-day window, the exchange is dead in the water. No extensions, no exceptions.
Once that deadline passes, your Qualified Intermediary is required to send your funds back to you. The sale of your old property instantly becomes a taxable event, and you're on the hook for all the capital gains. This is exactly why you should start hunting for a new property long before you even close on the one you're selling.
Can I Do an Exchange Without a Qualified Intermediary?
Not a chance. A Qualified Intermediary (QI) is absolutely mandatory for any delayed exchange. The whole point of the rule is to prevent you from having "constructive receipt" of the money.
The second the cash from your sale hits your personal or business bank account—even for a minute—the exchange is blown. The QI acts as a legally required, neutral third party to hold those funds, creating a "safe harbor" that keeps you compliant.
Does My New Loan Amount Have to Be the Same?
Not necessarily, but you do have to replace the debt you paid off. If the new loan on your replacement property is less than the mortgage you had on your old one, you'll need to bring more of your own cash to the table to cover the difference.
If you don't, you've created what's called "mortgage boot," and that portion becomes taxable. The guiding principle is simple: the total value of your new property (your cash plus the new loan) has to be equal to or greater than the value of the property you sold.
Navigating the complexities of a 1031 exchange requires expert guidance. At Edinhart Realty and Property Management, we help investors maximize their returns and seamlessly manage their real estate portfolios. Whether you're buying, selling, or need professional management, let our team help you achieve your investment goals.


